Pressure, Progress, and the Price of Staying Prepared

This week delivered a useful reminder that health and wealth rarely move on separate tracks. Interest rates, energy prices, public-health concerns, and advances in mental-health treatment can all affect the same household… sometimes simultaneously.

The larger lesson is not to predict every headline. It is to build enough margin into our health, finances, and daily routines that one difficult week does not knock us completely off course.

The Federal Reserve Raises Rates Again

The biggest financial story came from the Federal Reserve. On September 16, the Fed raised its target range for the federal funds rate by a quarter percentage point, bringing it to 3.75%–4.00%. The vote was unanimous.

For consumers, another rate increase can translate into higher borrowing costs on credit cards, variable-rate debt, auto loans, and eventually some mortgages. Savers may benefit if banks and money-market funds pass along higher yields, but that benefit can be offset when household expenses rise at the same time.

Investors should resist making an all-or-nothing move based on one Fed meeting. Higher rates can pressure richly valued growth stocks, real estate, and other rate-sensitive assets. However, they can also create opportunities in cash-equivalent investments, short-term Treasuries, and financially strong companies that generate dependable cash flow.

My approach remains simple: stay diversified, keep some cash available, dollar-cost average into high-conviction positions, and avoid chasing whatever moved the most this week. Volatility is uncomfortable, but it can also reward patience and preparation.
Illustrated editorial style artwork showing a large Federal Reserve building with dramatic upward-pointing arrows symbolizing rising interest rates. Stylized like a newspaper or health-economics publication illustration. Bold lines, limited color palette, serious tone.

Energy Costs Are Becoming a Household Issue Again

Rising gasoline and diesel prices are more than a transportation story. Diesel powers the trucks, equipment, and supply chains that move much of what Americans buy. When those costs increase, businesses often pass at least part of the expense to consumers.

That means higher energy prices can appear in grocery bills, delivery fees, airfare, household goods, and corporate profit margins. They can also complicate the Fed’s inflation fight because energy touches nearly every part of the economy.

For households, this is a good week to review spending rather than panic. Small adjustments combining errands, checking insurance and subscription costs, using fuel rewards wisely, and directing extra cash toward high-interest debt can help absorb rising prices without abandoning long-term investing goals.

Investors should watch companies with heavy transportation, manufacturing, or distribution costs. Revenue growth may look healthy while margins quietly weaken. In this environment, balance-sheet strength and pricing power matter.
Illustrated editorial artwork of a fuel pump nozzle with a price display showing high numbers, and a household in the background with utility bills. Stylized like a newspaper editorial illustration. Bold, expressive lines, limited warm color palette.

Mental-Health Treatment Continues to Evolve

On September 14, the FDA held a public hearing on the potential future therapeutic use of psychedelic drug products in supervised and supportive settings. The agency gathered perspectives on possible benefits, risks, clinical standards, patient protections, and the evidence that would be required.

This does not mean psychedelic treatments have received broad approval. It does show that federal regulators are seriously examining how emerging therapies might fit into a safe, evidence-based medical framework.

That matters to me personally. After completing TMS and reaching remission from depression, I understand how meaningful it can be when a treatment finally helps after a long struggle.

Innovation deserves hope but also discipline. New mental-health therapies require careful research, qualified medical supervision, honest discussions about risk, and strong protections for vulnerable patients.

The encouraging trend is that mental health is increasingly being treated like health: something worthy of scientific investment, open conversation, and individualized care.
Illustrated editorial artwork of a person sitting in a calm therapy session, warm light, a therapist listening attentively. Stylized like a health publication illustration — hopeful, human, and warm. Soft colors, clean editorial lines.

Public-Health Awareness: Rare Does Not Mean Ignorable

Rabies concerns also received attention this week following several unusual animal-exposure incidents. Human rabies remains rare in the United States, but it is almost always fatal after symptoms appear. The good news is that prompt wound cleaning, medical evaluation, and post-exposure vaccination can prevent the disease when treatment begins in time.

The practical takeaway is straightforward: never dismiss a bite, scratch, or possible saliva exposure involving a bat or an unfamiliar wild or domestic animal. Wash the area thoroughly and contact a healthcare professional or local health department promptly. Pet owners should also keep their animals’ vaccinations current.

Preparedness is not fear. It is knowing what deserves immediate action.
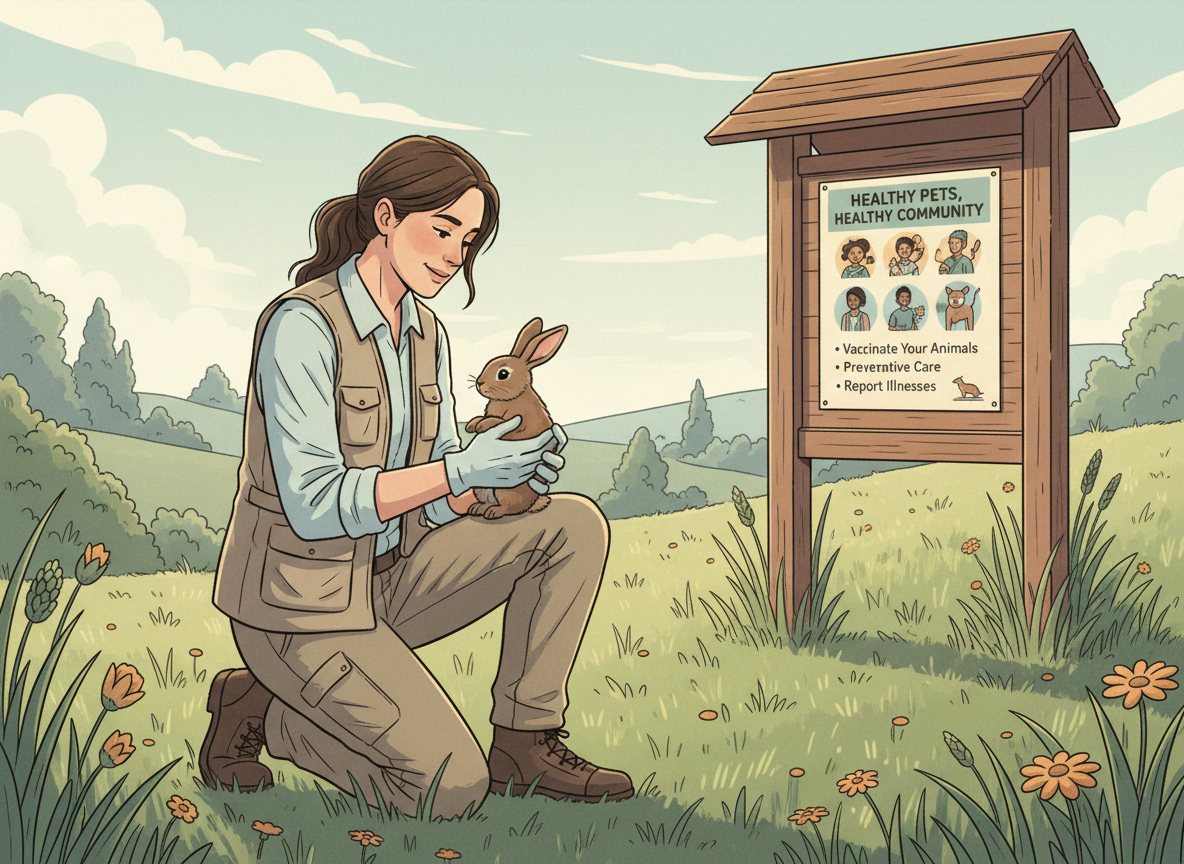
Illustrated editorial artwork of a veterinarian or public health worker in a natural outdoor setting, examining a small animal, with a community awareness poster in the background. Informative, calm, and reassuring editorial illustration style. Clean lines, muted natural colors.

One Step Forward

This week’s health and wealth stories point toward the same principle: protect your margin.

Financial margin means maintaining emergency savings, controlling expensive debt, diversifying investments, and leaving room to take advantage of opportunities.

Health margin means keeping appointments, following treatment plans, remaining active, sleeping as well as possible, and responding promptly when something feels wrong.

My one step forward this week is to review one area of vulnerability instead of trying to fix everything at once. That could mean checking the interest rate on a credit card, adding a little to an emergency fund, scheduling a delayed medical appointment, or simply getting outside for a daily walk.

Progress is rarely one giant decision. More often, it is a series of small choices that make us harder to knock down.
Illustrated editorial artwork of a person taking a confident step forward on a path — symbolic and hopeful. Could show someone walking, journaling, or making a phone call. Warm, optimistic editorial illustration style, like a health or wellness publication. Clean lines, uplifting color palette.

References

Disclaimer: This article is for educational and informational purposes only. It is not medical, investment, tax, or financial advice. Consult qualified professionals regarding your individual circumstances.

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
After TMS: The Finish Line Became a New Starting Point

On September 16, 2026, I completed my 36th and final TMS session.

After weeks of treatments, early-morning walks, difficult days, small victories and honest reflection, I reached the finish line. More importantly, I reached it feeling like my depression had finally entered remission.

I use the word “remission” carefully. Mental health recovery does not come with guarantees, and I cannot predict what the months ahead will bring. But today, I feel better. I am thinking more clearly, laughing again and returning to parts of life that depression had slowly pushed into the background.

That deserves to be celebrated.

But finishing TMS also taught me something important: completing treatment is not the end of the journey. It is the beginning of learning how to live again with intention.

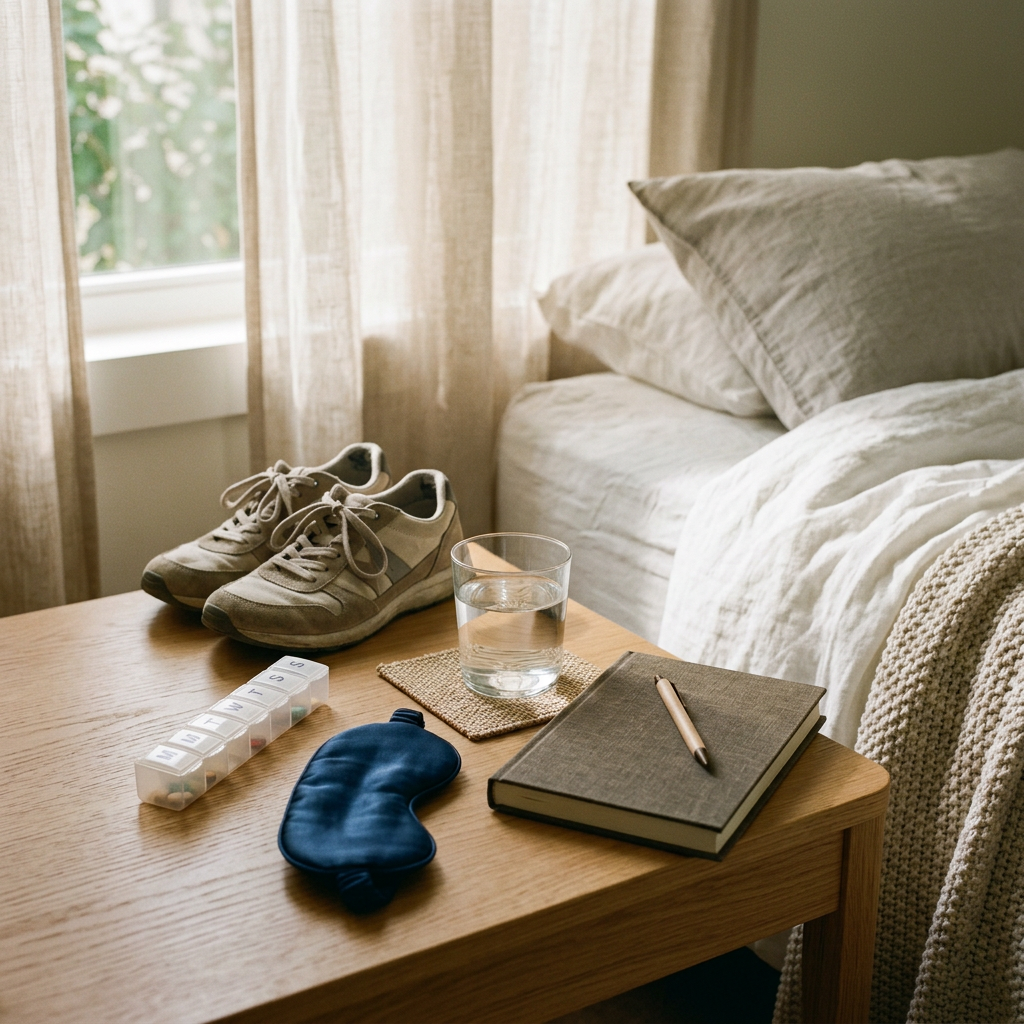
Bedside table with sneakers, pill organizer, water, sleep mask, and journal
A sunlit bedside table gathers everyday essentials for sleep, wellness, and a fresh start.

TMS Did Not Make Life Perfect

My TMS journey took place during a complicated season of life.

I lost Dolly, my dog of 17 years. I watched people I love struggle with their own emotions. I dealt with health problems, disrupted sleep and the uncertainty surrounding my return to work. Some days I felt strong. Other days, simply completing my treatment session was the victory.

TMS did not remove grief, stress or responsibility from my life. What it appeared to do was help create enough space for me to face those things without being completely overwhelmed by depression.

That distinction matters.

Recovery does not mean that nothing hurts anymore. It means the pain no longer controls every thought, decision and moment of the day. It means being able to experience a difficult event without automatically losing yourself inside it.

For me, progress began showing up in ordinary moments.

I started walking again. I made breakfast. I worked out. I prepared lunch. I spent time with my family. I took a trip to Las Vegas to celebrate my son Aidan’s 21st birthday and walked nearly 10 miles on some days.

None of those things sound extraordinary on their own. But when you have experienced depression, returning to ordinary life can feel extraordinary.

Returning to Work Without Trying to Prove Everything

Just two days after completing TMS, I prepared to return to work following an extended medical leave.

Part of me wanted to come back at full speed and prove that I was completely healed. But recovery is not something we prove through exhaustion. I do not need to make up for every difficult day by pushing myself beyond reasonable limits.

The better goal is consistency.

That means showing up, doing the work in front of me and allowing myself time to adjust. It means recognizing that returning to work is another step forward not a test of whether treatment “worked.”

This lesson applies beyond mental health. Whenever we recover from an illness, loss, financial setback or major disruption, there can be pressure to reclaim everything immediately. But sustainable progress usually happens through structure, patience and small decisions repeated over time.

My Routine Is Part of My Recovery

During treatment, I learned how much I benefit from structure. When I have too much unplanned time, my thoughts can begin racing. When my day has purpose, movement and manageable goals, I generally function better.

My post-TMS routine does not need to be complicated. It can begin with a few basic commitments:

  • Maintain a consistent sleep and wake schedule.
  • Use my CPAP and continue paying attention to sleep quality.
  • Walk or exercise regularly without treating every workout like a test.
  • Eat regular meals and stay hydrated.
  • Take medications only as prescribed and discuss concerns with my healthcare providers.
  • Keep follow-up appointments even when I am feeling well.
  • Pay attention to changes in mood, sleep, energy, impulsivity or anxiety.
  • Stay connected with my wife, family and trusted friends.
  • Continue writing honestly about the journey.

The National Institute of Mental Health recommends maintaining routines for sleep, meals and physical activity while staying connected to trusted people. For people living with bipolar disorder, it also emphasizes ongoing treatment, regular appointments and tracking changes in mood.

These habits are not replacements for professional care. They are ways to support the care I am already receiving.

Remission Is Not Permission to Stop Paying Attention

Feeling better can create its own temptation: the belief that continued treatment, medication management or follow-up care is no longer necessary.

That is a conversation for a qualified medical professional, not a decision to make alone.

Because I live with bipolar disorder, depression, ADHD, PTSD and anxiety, I know that changes in sleep, energy or behavior deserve attention. Feeling productive and energetic may be a sign of improvement, but dramatic changes such as needing much less sleep, racing thoughts, unusual irritability or impulsive decisions should not simply be dismissed as having a few great days.

The goal is not to live in fear of another episode. The goal is to know myself well enough to recognize meaningful changes early and ask for help when I need it.

Tracking a few daily indicators may help:

  • Hours and quality of sleep
  • Overall mood
  • Energy level
  • Anxiety
  • Exercise or movement
  • Medication consistency
  • Any unusual changes noticed by family

This is not about obsessing over every emotion. Everyone has good and bad days. It is about looking for patterns.

Glowing winding path through blue hills toward a sunrise
A sunlit bedside table gathers everyday essentials for sleep, wellness, and a fresh start.

One Step Forward

My “One Step Forward” campaign on Instagram began as a reminder that progress does not have to be dramatic to matter.

That message feels even more meaningful now.

Finishing TMS was a major step. Returning to work was another. But the steps that sustain recovery may be much smaller: taking a walk, getting enough sleep, eating breakfast, attending an appointment or telling someone when I am struggling.

I do not know exactly what the future holds. None of us do. What I know is that I feel hopeful again and hope is something I refuse to take for granted.

My depression may be in remission, but my commitment to my health continues.

Treatment helped me reach this point. Routine, support, follow-up care and self-awareness can help me protect the progress I have made.

Health is not separate from wealth. It is the foundation that allows us to work, create, invest, connect and enjoy the life we are trying to build.

Today, I am not promising perfection. I am choosing consistency.

One walk. One workday. One healthy decision. One honest conversation.

One step forward.

Author’s note: This article reflects my personal experience and is intended for general education and encouragement. TMS outcomes and mental health needs vary by individual. It is not medical advice and should not be used to start, stop or change treatment or medication. Speak with a qualified healthcare professional about your personal care. If you are in crisis or experiencing thoughts of self-harm, call or text 988 in the United States.

Sources: National Institute of Mental Health: Depression and National Institute of Mental Health: Bipolar Disorder.

GLP-1 Drugs Are Changing American Healthcare & Employers Are Feeling the Financial Pressure

The weight-loss revolution is no longer just about losing weight. It is becoming a major financial issue for employers, insurers and American families.

GLP-1 medications have rapidly transformed the treatment of obesity and related health conditions. Drugs such as Wegovy and Mounjaro have moved from being relatively specialized treatments to becoming some of the most closely watched medications in the healthcare industry.

Now, the financial impact is becoming impossible for employers to ignore.

Recent healthcare industry reporting shows that GLP-1 medications are forcing employers to reconsider how they structure and finance employee healthcare benefits. The growing demand for these medications has created a difficult balancing act: employers want to provide effective treatment for obesity and chronic disease, but they also have to manage rapidly increasing pharmacy costs.

Why GLP-1 medications matter

The appeal of GLP-1 medications goes far beyond the number on the bathroom scale.

Obesity is associated with numerous health conditions, including cardiovascular disease, type 2 diabetes and other chronic illnesses. As a result, employers and insurers increasingly have to consider whether paying for obesity treatment today could potentially reduce healthcare costs associated with complications later.

That creates an important question:

Is a more expensive medication today actually an investment in lower healthcare costs tomorrow?

The answer isn’t simple.

GLP-1 therapy can be expensive, and patients may require long-term treatment. That means employers could face substantial recurring pharmacy expenses if large numbers of employees gain coverage.

At the same time, preventing or improving chronic conditions could potentially generate savings elsewhere in the healthcare system.

This is where the health and wealth sides of the equation collide.

The employer healthcare dilemma

For decades, employers have struggled with rising healthcare premiums, hospital costs, specialty drugs and chronic disease management.

GLP-1 medications add another layer to the problem.

Companies must determine whether to:

  • Cover GLP-1 medications broadly.
  • Require prior authorization or other utilization-management strategies.
  • Limit coverage to specific medical indications.
  • Pair medication coverage with nutrition, exercise and behavioral-health programs.
  • Exclude coverage entirely.

None of these choices is easy.

Restricting access can reduce short-term spending, but employers may worry about employee satisfaction and long-term health outcomes. Providing unrestricted access may improve treatment availability but create significant pharmaceutical expenses.

The challenge is finding a sustainable middle ground.

Healthcare is moving toward a broader definition of value

One of the most interesting developments is that GLP-1 treatment is increasingly being viewed as part of a broader healthcare strategy rather than simply a weight-loss benefit.

The federal government’s CMS BALANCE model, announced in August, is designed to expand access to GLP-1 medications for eligible Medicare and Medicaid beneficiaries while combining medication with lifestyle interventions such as diet and physical activity.

That approach highlights an important principle:

Medication may be most effective when it is part of a larger health strategy.

Instead of viewing obesity treatment as simply paying for a prescription, healthcare organizations are increasingly examining the potential benefits of combining medication with nutrition, physical activity and behavioral support.

That could ultimately change how employers design wellness programs.

The financial opportunity & risk

From an investment perspective, GLP-1 medications have created an enormous pharmaceutical market.

Companies developing obesity treatments are competing to improve effectiveness, reduce side effects, extend dosing intervals and develop alternatives to injections.

The next phase could be particularly important: oral medications and next-generation treatments could make obesity therapy more convenient and potentially expand the market even further.

But investors should remember that a booming healthcare market does not automatically mean every company involved will be a winner.

Drug pricing, insurance coverage, regulatory decisions, competition and patient retention can dramatically affect pharmaceutical companies’ revenue and profitability.

There is also a growing concern about consumers obtaining weight-loss medications through unregulated channels.

A Reuters report published August 31 highlighted the growing black market for GLP-1 drugs in Brazil, where demand for lower-cost alternatives has contributed to the circulation of smuggled and unregulated products. Health officials have linked these products to serious complications and deaths.

That serves as an important reminder:

When demand for healthcare becomes enormous, the economics can create both innovation and unintended consequences.

What this means for consumers

For individuals considering GLP-1 therapy, the conversation shouldn’t begin and end with weight loss.

Patients should discuss the potential benefits, risks, costs and long-term treatment strategy with a qualified healthcare professional.

The cheapest medication isn’t necessarily the best option, and the newest medication isn’t automatically the best option either.

The real value comes from finding a treatment strategy that improves health while remaining financially sustainable.

The Health to Wealth takeaway

The GLP-1 revolution represents something much bigger than a pharmaceutical trend.

It is a case study in how health and wealth are interconnected.

If these medications help millions of people improve their health, the potential benefits could extend beyond individual patients to employers, insurers and the broader healthcare system.

But somebody has to pay for that treatment.

That is why the next chapter of the GLP-1 story may be less about whether these medications work and more about who pays, how much they pay, and whether the long-term health benefits justify the enormous financial investment.

For consumers, employers and investors alike, GLP-1 medications may be one of the most important healthcare-and-finance stories of the decade.

At Health to Wealth Ventures, we believe better health and better financial decisions go hand in hand. The future of healthcare isn’t just about what medicine can do… it’s about whether we can make those advances accessible, sustainable and financially responsible.

This article is for informational and educational purposes only and should not be considered medical, financial, investment or insurance advice.

References

Reuters. (2026, August 31). GLP-1 drugs are almost single-handedly forcing employers to reconsider workers’ health care.

Centers for Medicare & Medicaid Services. (2026, August 14). BALANCE: Better Approaches to Lifestyle and Nutrition for a Healthy America.

Reuters. (2026, August 31). Booming weight-loss drug demand in Brazil fuels thriving black market and health fears.

Health Update: My TMS Journey

At Health to Wealth Ventures, I’ve always believed that true wealth begins with good health. That’s why I’ve made the decision to openly document my experience with Transcranial Magnetic Stimulation (TMS) as I work toward recovery from depression and reclaiming the best version of myself.

Hiker on rocky mountain trail at sunrise with sun rising behind distant peaks
A hiker walks along a rocky mountain trail at sunrise with a stunning mountain range ahead.

This week marked the completion of another week of treatment.

The journey hasn’t been easy, but it has been worthwhile. Like many people beginning TMS, I’ve experienced moments of hope, fatigue, mental fog, and emotional ups and downs. While I’m still early in the process and not expecting overnight results, I’ve already noticed small signs that encourage me to keep moving forward.

One lesson this experience has reinforced is that recovery is rarely linear. Healing takes patience, consistency, and the willingness to trust the process even on the difficult days.

Outside of treatment, I’ve remained committed to healthy habits that support both my physical and mental well-being. Daily walks, exercise, preparing healthy meals, maintaining routines, and leaning on family and friends have all become important pieces of my recovery. TMS is one tool, but lasting wellness comes from caring for the whole person.

By sharing this journey, my hope is that others battling depression realize they are not alone. Mental health deserves the same attention and compassion as physical health, and seeking treatment is a sign of strength not weakness.

Glowing river flowing through green hills at twilight with starry sky.
A glowing, ethereal river winds through lush green hills under a twilight sky.

As Dwayne “The Rock” Johnson once said, “Depression never discriminates.” Those simple words remind us that mental illness can affect anyone, regardless of success, background, or circumstance.

I’m optimistic about the weeks ahead and committed to seeing this treatment through. Once I complete my full course of TMS, I’ll publish a comprehensive update sharing my experience, what I’ve learned, and whether the treatment helped me achieve the recovery I’ve been working toward.

Thank you for following along and for your continued encouragement. If sharing my story helps even one person take the first step toward getting help, then this journey will have an impact far beyond my own recovery.

Remember: Your health is your greatest investment, and investing in your mental health is one of the most valuable decisions you can make.

From Family History to Healing: Understanding Mental Health

Mental health is often a topic that families struggle to talk about. We may know about physical illnesses that run in our families heart disease, diabetes, cancer but we don’t always discuss depression, anxiety, trauma, or other mental health challenges with the same openness.

Recently, I found myself reflecting on my father’s story and how family experiences can shape the way we understand mental health.

Tree with roots forming a heart shape on forest floor
A large tree with roots naturally forming a heart shape in a sunlit forest

My father suffered a heart attack at a relatively young age. He was a heavy smoker, and his heart health was something that impacted our family. After that heart attack, he told me he had taken lithium, explaining that it was for his heart. Looking back, I now understand that lithium is not typically used as a heart medication. It is most commonly associated with mood stabilization, particularly for conditions such as bipolar disorder and certain forms of treatment-resistant depression.

The truth is, I may never know exactly why he took it. Medical records are not always available, and sometimes family members remember medications or diagnoses differently than they were documented. But the conversation made me think about something deeper: the connection between trauma, mental health, and family history.

My father experienced a devastating loss when his brother was shot and killed by his wife. They were extremely close, and a tragedy like that can leave a lasting emotional impact. Severe trauma and grief can contribute to depression, anxiety, PTSD, and other mental health struggles. While we cannot assume exactly what my father experienced or what treatment he needed, it reminds me that emotional wounds can be just as real as physical ones.

That realization has also caused me to reflect on my own mental health journey.

I have been working through depression and other challenges, and I am now beginning a new chapter by starting Transcranial Magnetic Stimulation (TMS) therapy. TMS is a noninvasive treatment that uses magnetic pulses to stimulate specific areas of the brain involved in mood regulation. For many people who have not found enough relief through medication alone, TMS can provide another option.

Starting TMS is not about giving up on previous treatments it is about continuing to search for what works. Mental health treatment is often a process of finding the right combination of therapies, medications, lifestyle changes, support systems, and self-awareness.

Glowing human brain with light beams breaking through surrounding dark rocks
A glowing brain surrounded by radiant light beams breaking through darkness

As I begin this journey, I want to share a few lessons I have learned:

1. Family history matters.
Understanding the experiences, struggles, and challenges within our families can provide important context for our own health journeys.

2. Trauma can affect generations.
Painful events do not always end when the event is over. Grief, loss, and trauma can influence how people cope, communicate, and seek help.

3. Mental health deserves the same attention as physical health.
We would never tell someone with heart disease to simply “push through it.” Depression and other mental health conditions deserve compassion, treatment, and support.

4. Healing is not always a straight line.
Sometimes progress comes from trying something new, adjusting course, and being willing to ask for help.

At Health to Wealth Ventures, the goal has always been to look at the complete picture of health, mind, body, finances, safety, and quality of life. True wealth is not just measured by what we own; it is also measured by our ability to enjoy life, maintain relationships, and take care of ourselves.

My TMS journey is just beginning. I don’t know exactly what the outcome will be, but I do know this: seeking help is a sign of strength, not weakness.

By sharing our stories, we can help remove the stigma around mental health and remind others that they are not alone in their journey toward healing.

Health is the foundation. Wealth is the opportunity. Together, they create a life worth living.

Rising Homeowners Insurance Costs: What You Need to Know

Rising Costs Are Changing the Homeowners Insurance Conversation

Homeowners are facing some of the highest insurance premiums in decades for homeowner’s insurance. Inflation, severe weather events, increased construction costs, and rising litigation expenses have forced many insurers to reevaluate their risk exposure. In states such as Florida, Texas, California, and Louisiana, homeowners have experienced significant premium increases and, in some cases, reduced carrier availability.

As insurance costs continue to rise, many homeowners are asking the same question: “Am I carrying the right coverage, or am I paying for protection I may never use?”

The answer depends on your individual situation, but understanding the major components of a homeowners policy can help you make informed decisions.

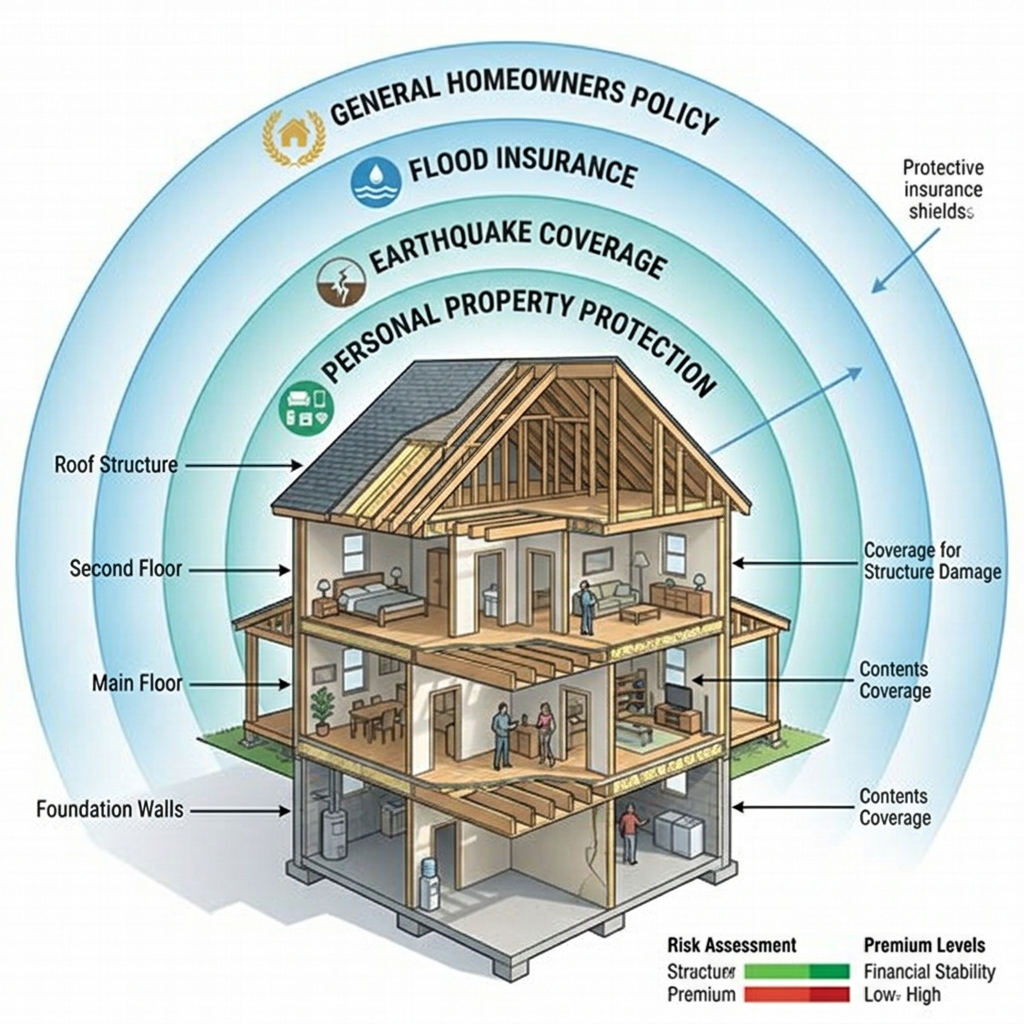
Cross-section of house with labels for roof structure, second floor, main floor, foundation walls, and insurance coverage types including general homeowners policy, flood insurance, earthquake coverage, and personal property protection.
A cross-section of a home illustrating various insurance coverage layers and protections.

Coverages Most Homeowners Should Consider Keeping

Dwelling Coverage

Dwelling coverage protects the structure of your home from covered losses such as fire, wind, hail, and other insured perils.

One of the biggest mistakes homeowners make is underinsuring their property. Construction costs have risen dramatically over the last several years, making it more expensive to rebuild a home after a total loss.

Consider: Reviewing your dwelling limit annually to ensure it reflects current rebuilding costs—not necessarily the market value of your home.

Personal Property Coverage

Furniture, electronics, clothing, appliances, and personal belongings can add up quickly. Many homeowners underestimate the value of their possessions until they experience a major loss.

Consider: Creating a home inventory and verifying that your coverage limits are sufficient.

Liability Coverage

Liability coverage protects you if someone is injured on your property or if you accidentally cause damage to another person’s property.

Medical expenses and lawsuits can quickly become expensive.

Consider: Increasing liability limits to $300,000 or $500,000 if your insurer offers affordable options.

Loss of Use Coverage

If your home becomes uninhabitable due to a covered loss, loss-of-use coverage helps pay for temporary housing and living expenses.

This coverage can be invaluable following major storms, fires, or water damage claims.

Coverages Worth Reviewing

High Deductibles vs. Low Deductibles

Many homeowners carry deductibles established years ago when premiums were much lower.

Increasing your deductible from $500 to $2,500 or even $5,000 could significantly reduce annual premiums.

Trade-Off: You’ll pay more out-of-pocket if a claim occurs.

Personal Property Limits

Some homeowners may be carrying higher limits than necessary if they have downsized or replaced expensive items.

Consider: Reviewing current belongings and adjusting coverage accordingly.

Scheduled Personal Property

Items such as jewelry, collectibles, artwork, firearms, and high-end electronics often require additional endorsements.

If you no longer own these items, removing unnecessary endorsements may reduce premium costs.

Additional Structures Coverage

Coverage for detached garages, sheds, fences, and other structures may be higher than needed if structures have been removed or reduced in value.

A periodic policy review can identify potential savings.

Important Coverages Many Homeowners Overlook

Water Backup Coverage

Standard homeowners policies typically do not cover sewer or drain backup losses.

A relatively inexpensive endorsement can help protect against costly water damage.

Flood Insurance

Many homeowners incorrectly assume flood damage is covered under a standard homeowners policy.

In reality, flood losses are generally excluded.

Even homes outside designated flood zones can experience flooding due to heavy rainfall, hurricanes, or drainage issues.

Ordinance or Law Coverage

Building codes change over time. If your home suffers significant damage, you may be required to rebuild portions of it to current code standards.

Ordinance or law coverage helps pay these additional expenses.

Equipment Breakdown Coverage

Many insurers now offer protection for HVAC systems, electrical panels, water heaters, and other major home systems.

This coverage can provide value for homeowners concerned about unexpected repair costs.

When Filing Small Claims May Cost More Than It Saves

A common misconception is that insurance should be used for every loss.

In reality, frequent claims can impact eligibility, renewal options, and future premiums.

For example, filing multiple water damage claims within a few years could make it more difficult to obtain favorable rates in the future.

Homeowners should evaluate whether a smaller loss justifies filing a claim or whether paying out-of-pocket may be the better financial decision.

Miniature house on one side of scale balanced with stacks of coins on the other side.
A scale balancing a miniature house and stacks of coins representing home value.

Final Thoughts

Homeowners insurance should not be viewed as a “set it and forget it” product. As property values, rebuilding costs, and personal circumstances change, coverage needs evolve as well.

A yearly policy review can help identify gaps in protection, uncover potential savings opportunities, and ensure your home remains adequately insured against today’s risks.

The goal is not necessarily to buy the cheapest policy available. Instead, homeowners should focus on balancing affordability with meaningful protection because saving a few dollars today could become extremely costly after a major loss.

Disclosure: This article is for informational purposes only and should not be considered insurance, legal, or financial advice. Coverage availability, exclusions, and policy terms vary by insurer and state. Consult a licensed insurance professional regarding your specific situation.

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
Why Uninsured Motorist, Comprehensive, and Collision Coverage May Be Worth the Cost

Understanding the Coverages That Protect More Than Just Your Car

When shopping for auto insurance, many drivers focus on finding the lowest premium possible. While saving money is important, reducing coverage can sometimes create much larger financial risks down the road. Three coverages that often generate questions are Uninsured Motorist Coverage, Comprehensive Coverage, and Collision Coverage.

These coverages can add cost to a policy, but they may also provide critical protection when life throws an unexpected curveball.

Gray car surrounded by glowing electric blue shield in a storm with rain and lightning
A car is shielded by a glowing electric barrier during a storm.

Uninsured Motorist Coverage: Protection From Other Drivers’ Mistakes

Despite laws requiring auto insurance in most states, millions of drivers continue to operate vehicles without coverage or with limits too low to fully pay for damages they cause.

Uninsured Motorist (UM) Coverage helps protect you if you’re injured by a driver who has no insurance. In many states, Underinsured Motorist Coverage (UIM) may also help when the at-fault driver’s policy limits are insufficient to cover your losses.

Example

Imagine you’re stopped at a red light and another driver rear-ends your vehicle. You suffer injuries requiring physical therapy and miss several weeks of work. Later, you discover the other driver has no insurance.

Without Uninsured Motorist Coverage:

  • You may have to rely on your health insurance.
  • Lost wages may not be fully covered.
  • Recovering damages could require legal action against someone who may have limited assets.

With Uninsured Motorist Coverage:

  • Your own policy may help pay medical expenses, lost wages, and other covered damages.

Reasons You Might Consider Leaving It Off

  • You have substantial personal assets and alternative protection strategies.
  • You live in an area with relatively low uninsured driver rates.
  • Budget constraints make affordability the top priority.

However, many insurance professionals consider UM coverage one of the most valuable protections available because it safeguards you from risks you cannot control.

Comprehensive Coverage: Protection Against Life’s Surprises

Comprehensive Coverage protects against losses that are generally not caused by a collision.

Common examples include:

  • Theft
  • Vandalism
  • Falling objects
  • Fire
  • Flooding
  • Hail damage
  • Animal strikes

Example

You walk outside one morning and discover a large tree branch has fallen on your parked vehicle during a storm.

Without Comprehensive Coverage:

  • You pay the repair bill entirely out of pocket.

With Comprehensive Coverage:

  • Your insurance company may cover repairs after your deductible is applied.

Another Example

A vehicle owner in Florida parks overnight and wakes up to find their car submerged after a major storm causes flash flooding.

Comprehensive Coverage may help cover the damage, while basic liability insurance would not.

Reasons You Might Consider Leaving It Off

  • Your vehicle has a very low market value.
  • The annual premium approaches the value of the vehicle itself.
  • You could comfortably replace the vehicle from savings if it were totaled.

For many drivers, comprehensive coverage provides peace of mind against unpredictable events that occur when the vehicle isn’t even being driven.

Collision Coverage: Protection for Your Vehicle

Collision Coverage helps pay for damage to your vehicle when it collides with another vehicle or object, regardless of fault.

Example

You’re backing out of a parking space and accidentally strike a concrete pole.

Without Collision Coverage:

  • You are responsible for all repair costs.

With Collision Coverage:

  • Your policy may pay for repairs after your deductible.

Another Example

A driver loses control during heavy rain and slides into a guardrail. The vehicle sustains $12,000 in damage.

With Collision Coverage:

  • The policy may cover repairs, less the deductible.

Without Collision Coverage:

  • The owner must absorb the entire loss.

When It May Make Sense to Drop Collision Coverage

There are situations where removing collision coverage can be financially reasonable.

Consider:

  • The vehicle’s value has significantly declined.
  • You have sufficient savings to replace the vehicle.
  • The premium and deductible together provide little financial benefit compared to the vehicle’s actual cash value.

For example, carrying collision coverage on a vehicle worth only $2,500 may not always make economic sense if the annual premium is high.

A Simple Rule of Thumb

Many insurance professionals suggest periodically reviewing your vehicle’s value. As vehicles age, the cost-benefit analysis of comprehensive and collision coverage changes.

Ask yourself:

  • What is my vehicle worth today?
  • Could I afford to replace it tomorrow?
  • How much would a major repair affect my finances?
  • Am I comfortable assuming more risk in exchange for lower premiums?
Blue car with digital icons indicating theft, fire, flood, and collision protection
A blue car parked with digital icons showing theft, fire, flood, and collision coverage

Final Perspective

Auto insurance isn’t just about satisfying state requirements, it’s about protecting your financial future. Uninsured Motorist, Comprehensive, and Collision Coverage each address different risks that can lead to significant out-of-pocket expenses.

While there are legitimate reasons to decline these coverages, drivers should carefully evaluate the potential savings against the financial consequences of a major accident, theft, storm, or uninsured driver. The cheapest policy is not always the least expensive option when an unexpected loss occurs.

As with any insurance decision, reviewing your coverage annually and discussing your needs with a licensed insurance professional can help ensure your protection keeps pace with your changing circumstances.

Disclaimer: This article is for educational purposes only and is not insurance, legal, or financial advice. Coverage availability, policy terms, exclusions, and requirements vary by state and insurance carrier. Consult a licensed insurance professional regarding your specific situation.

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
From Insurance Insights to Everyday Life: A Look Back at Conversations That Matter

Over the past few years here, one thing has become clear: the topics that matter most are the ones that impact everyday people in real life. From protecting families financially to improving personal health and building long-term wealth, the conversations shared across social media have focused on practical advice, real experiences, and personal growth.

Here’s a look back at some of the biggest themes that resonated with readers and followers alike.

Dirt path winding through grassy hills toward a city skyline at sunset with glowing navigation icons.
A scenic dirt path leads to a city skyline at sunset, with glowing navigation and connectivity icons along the trail.

Insurance Isn’t Just a Bill… It’s a Financial Safety Net

One recurring topic has been the importance of understanding insurance beyond the monthly premium. Conversations around auto insurance scores, homeowner protection, life changes, and shopping for coverage highlighted how important it is to make informed decisions.

Many drivers don’t realize that constantly switching insurance companies can sometimes hurt their long-term pricing and stability. Insurance history, payment consistency, claim frequency, and credit-related factors often play a role in how rates are calculated. The key message shared over time has been simple:

✅ Shop smart
✅ Compare coverage… not just price
✅ Understand what you’re buying
✅ Protect yourself before problems happen

There were also important discussions about protecting families after the loss of a spouse. Topics included updating estate documents, reviewing beneficiaries, adjusting homeowners and auto insurance policies, and making sure financial accounts are organized during difficult times.

Health and Sleep Matter More Than We Admit

Another major focus centered around health and quality of life, especially sleep.

Personal experiences discussing CPAP therapy opened conversations for many people struggling silently with exhaustion, poor sleep quality, and untreated sleep apnea. The message was relatable because it focused on real-life improvements instead of medical jargon.

Many readers connected with the idea that better sleep can improve:

  • Energy levels
  • Mood and mental clarity
  • Blood pressure
  • Productivity
  • Overall quality of life

The discussions also honestly addressed the adjustment period that comes with CPAP use, reminding people that long-term health improvements often require patience and consistency.

Mental Health Conversations Continue to Break Stigma

Mental health awareness became another important topic throughout the years. Rather than focusing only on diagnoses or labels, the message centered around perseverance, growth, and finding purpose despite difficult seasons.

The overall tone remained encouraging:

Every day is another opportunity to keep moving forward.

Readers responded positively to honest conversations about stress, emotional struggles, and the importance of seeking support while continuing to pursue productive and meaningful lives.

Investing Conversations Focused on Long-Term Thinking

Investment-related discussions also attracted strong engagement, especially around dividend-paying companies and emerging growth opportunities.

Articles and commentary involving companies like General Mills (GIS) and Ondas Holdings (ONDS) explored the balance between stability and growth potential.

Topics included:

  • Dividend investing
  • Market volatility
  • Long-term portfolio strategy
  • Risk management
  • Emerging technology opportunities

One consistent theme stood out:

📈 Investing is not about chasing hype every day it’s about building disciplined habits over time.

Transparency also remained important, with disclosures shared whenever positions in discussed companies were personally owned.

Vintage balance scale weighing health symbols, money, tech devices, and family icons.
A vintage scale balancing symbols of health, money, technology, and family.

Technology, Sustainability, and Everyday Innovation

Discussions around sustainability and technology showed how rapidly the world is changing. Topics ranged from electric vehicles and smart homes to how innovation is reshaping the insurance industry itself.

As more households adopt connected devices and cleaner technologies, conversations emphasized how these changes may impact:

  • Insurance pricing
  • Risk assessment
  • Home safety
  • Driving habits
  • Long-term financial savings

The growing overlap between technology and personal finance continues to create opportunities for consumers willing to stay informed.

Why These Conversations Connected With People

The reason these topics gained attention is because they were grounded in real life.

They weren’t just about headlines or trends they focused on:

✔ Protecting families
✔ Improving health
✔ Building financial stability
✔ Encouraging personal growth
✔ Preparing for the unexpected

In a social media environment often dominated by negativity and noise, practical conversations that educate, encourage, and empower people continue to stand out.

Key Takeaway

Over the years, these discussions have shown that everyday decisions can have a lasting impact. Whether it’s reviewing an insurance policy, improving sleep, investing for the future, or simply finding ways to stay positive during difficult times, small steps often create meaningful long-term results.

The conversations will continue because life keeps evolving, and staying informed matters more than ever.

Understanding Auto Insurance Scores: Key Factors Impacting Rates

As auto insurance premiums continue to rise across the country, many drivers are asking the same question: What actually affects my insurance score, and why did my rate increase? While most consumers focus only on accidents and tickets, insurance companies evaluate far more data when determining premiums.

Understanding how insurers calculate risk can help drivers lower costs, avoid common mistakes, and make smarter decisions when shopping for coverage.

What Is an Auto Insurance Score?

An auto insurance score is a rating system insurers use to estimate the likelihood that a driver may file claims in the future. It is different from a traditional credit score, although credit-related factors can influence it in many states.

Insurance carriers analyze multiple variables to determine risk exposure and pricing. The higher your insurance score, the more favorable your premiums may become.

Futuristic sports car with digital speedometer and secure payment icons
A futuristic sports car speeding with digital security and payment elements

Key Factors That Impact Your Auto Insurance Score

Driving History

Your driving record remains one of the largest rating factors. Insurance companies review:

  • Speeding tickets
  • At-fault accidents
  • DUI or reckless driving violations
  • Frequency of claims
  • License suspensions

Drivers with clean records generally receive the best rates because they statistically present lower risk.

Credit-Based Insurance Factors

In many states, insurers use credit-based insurance scoring models. While controversial, studies have shown correlations between credit behavior and claims frequency.

Factors may include:

  • Payment history
  • Outstanding debt
  • Length of credit history
  • Credit utilization
  • Collection accounts

Late payments or high debt levels may negatively impact premiums even if your driving record is spotless.

Coverage Lapses

One of the most overlooked rating factors is a lapse in insurance coverage.

Drivers who allow policies to cancel due to nonpayment or gaps between companies are often viewed as higher risk. Even a short lapse can significantly increase premiums when obtaining a new policy.

Maintaining continuous coverage is one of the easiest ways to protect your insurance score.

Frequency of Insurance Shopping

Many consumers assume switching insurance companies every six months always saves money. While comparison shopping is smart, excessive switching can sometimes work against you.

Insurance companies often reward long-term policyholders with:

  • Loyalty discounts
  • Accident forgiveness
  • Lower renewal increases
  • Multi-policy savings
  • Enhanced underwriting consideration

Frequent changes may reset some of these benefits and can signal instability to insurers.

That does not mean drivers should stay with a company charging unreasonable premiums. Instead, consumers should evaluate whether savings outweigh the long-term advantages they may lose.

Vehicle Type Matters

The vehicle you drive heavily influences rates. Insurance companies analyze:

  • Repair costs
  • Theft rates
  • Safety ratings
  • Horsepower
  • Claim frequency for that model

Sports cars, luxury vehicles, and certain electric vehicles may carry higher premiums due to expensive repairs or increased accident statistics.

Location and ZIP Code

Where you live affects rates more than many realize.

Urban areas with:

  • Heavy traffic
  • Higher theft rates
  • More uninsured drivers
  • Increased accident frequency

typically experience higher premiums than rural communities.

Even moving a few miles can change insurance pricing.

Why You Should Not Change Insurance Companies Too Often

While shopping periodically is healthy, constantly jumping between carriers can create unintended consequences.

Loss of Loyalty Benefits

Some insurers reserve their best perks for customers who stay multiple years. Leaving too soon may eliminate:

  • Claim-free rewards
  • Vanishing deductibles
  • Preferred pricing tiers
  • Renewal stability

Underwriting Red Flags

Frequent switching may cause some insurers to question whether:

  • Policies lapsed previously
  • Claims history is unstable
  • Payments were inconsistent

Even if none of those issues exist, some carriers still prefer customers with longer tenure histories.

Constant Rate Fluctuations

Introductory pricing sometimes expires after the first term. Consumers who repeatedly chase teaser rates may find themselves trapped in a cycle of temporary discounts followed by unexpected increases.

When It Makes Sense to Shop for New Insurance

Drivers should still review coverage regularly, especially after:

  • Major rate increases
  • Vehicle purchases
  • Marriage or divorce
  • Moving to a new state
  • Teen drivers entering the household
  • Credit improvement
  • Accidents aging off records

Industry experts generally recommend comparing quotes every 1–3 years instead of every few months.

How to Shop Smart for Auto Insurance

Notebook with monthly growth chart and notes, smartphone showing revenue and traffic charts, calculator, keys, and a coffee mug on wooden desk
A workspace featuring charts, notes, and financial tools for monthly growth analysis

Compare Equal Coverage

One of the biggest mistakes consumers make is comparing policies with different limits.

Always compare:

  • Liability limits
  • Deductibles
  • Collision coverage
  • Comprehensive coverage
  • Rental reimbursement
  • Roadside assistance

A cheaper quote may provide significantly less protection.

Research Company Reputation

Price matters, but service quality matters too.

Look for:

  • Claims satisfaction ratings
  • Financial strength
  • Customer reviews
  • Local agent availability
  • Mobile app functionality

A low premium means little if claim handling becomes difficult after an accident.

Bundle Policies

Many insurers provide discounts when combining:

  • Auto insurance
  • Homeowners insurance
  • Renters insurance
  • Umbrella policies

Bundling can sometimes reduce total insurance costs substantially.

Ask About Discounts

Consumers are often surprised by the number of available discounts, including:

  • Safe driver programs
  • Defensive driving courses
  • Low mileage discounts
  • Good student discounts
  • Vehicle safety features
  • Automatic payment enrollment

Avoid Minimum Coverage Mistakes

State minimum coverage may not fully protect your finances after a serious accident.

Medical bills, lawsuits, and vehicle damage can easily exceed minimum liability limits. Many financial professionals recommend carrying higher liability protection if affordable.

Key Takeaways for Drivers

Your auto insurance score is influenced by far more than accidents alone. Credit behavior, coverage consistency, vehicle choice, and long-term insurance history all play important roles in determining premiums.

While shopping around occasionally can help consumers find better value, constantly changing insurance companies may cost drivers valuable loyalty benefits and long-term stability.

The smartest strategy is balancing competitive pricing with strong coverage, reliable customer service, and consistent insurance history. Drivers who understand how insurers evaluate risk are often in the best position to secure affordable protection for years to come.

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
How CPAP Changed My Sleep and Why Others Should Consider It

For years, sleep felt more like survival than recovery. Waking up exhausted, struggling through the day with fatigue, headaches, irritability, and brain fog became normal. Like many people dealing with sleep issues, I thought poor sleep was simply part of getting older, stress, or working too much. What I did not realize was that the quality of sleep matters just as much as the number of hours spent in bed.

That changed after beginning therapy with a Continuous Positive Airway Pressure device, more commonly known as a CPAP machine.

Today, CPAP therapy continues to improve my sleep, energy levels, and overall quality of life. While the adjustment was not always easy, the long-term benefits have made the experience worthwhile and could help many others who struggle with chronic fatigue, loud snoring, or interrupted sleep.

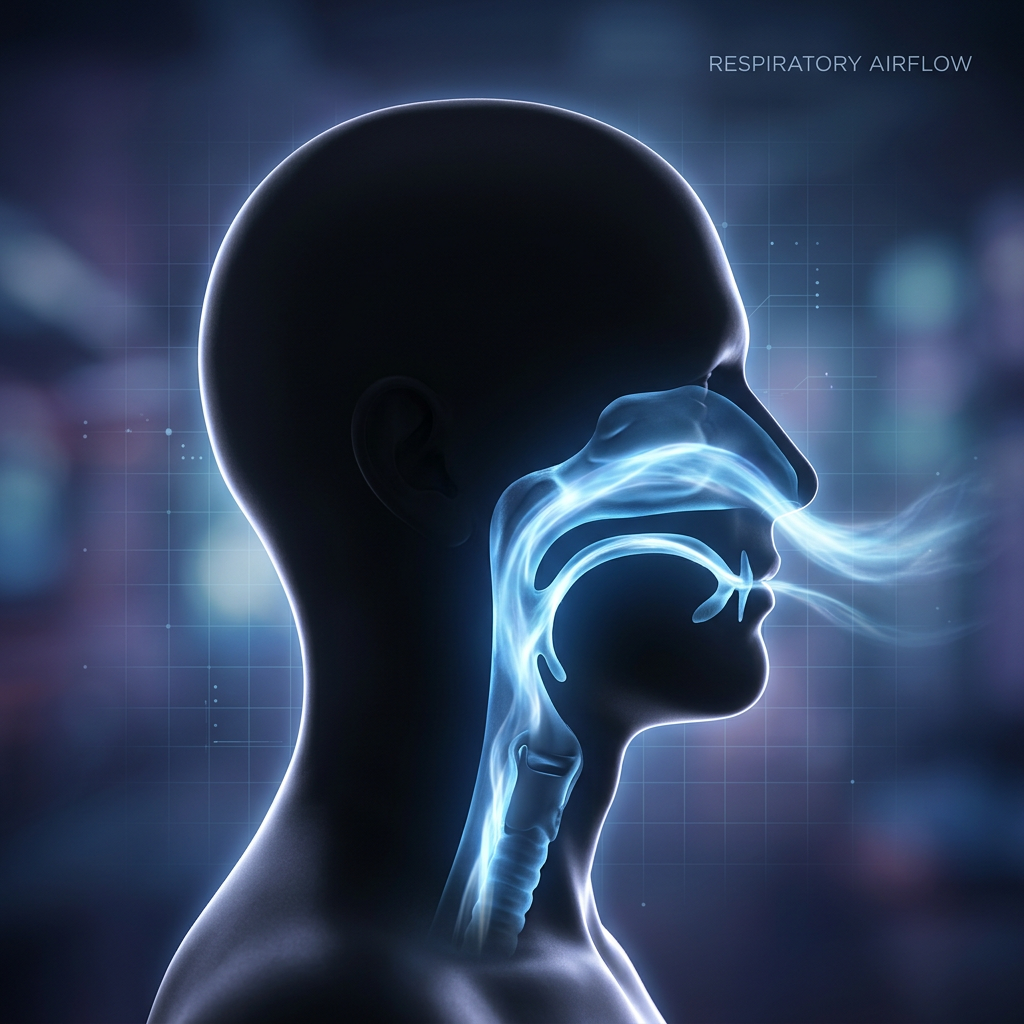
Side profile of a human head with airflow moving through nasal and oral passages into the throat.
Illustration showing the flow of air through the human respiratory tract.

Understanding CPAP Therapy

A CPAP machine is commonly prescribed for people suffering from Obstructive Sleep Apnea, a condition where breathing repeatedly stops and starts during sleep. The machine delivers steady air pressure through a mask to help keep the airway open throughout the night.

For many people, untreated sleep apnea can lead to serious health risks including high blood pressure, heart problems, diabetes complications, daytime exhaustion, and poor concentration.

In my experience, I did not fully understand how often my sleep was being interrupted until treatment began.

The Difference CPAP Made

One of the first noticeable changes was waking up feeling more alert. Before CPAP therapy, even a full night of sleep could leave me drained. After consistent use, mornings became easier and daytime fatigue gradually improved.

Other benefits became noticeable over time:

  • Improved focus and mental clarity
  • Reduced daytime sleepiness
  • Better mood and patience
  • Fewer morning headaches
  • More consistent energy throughout the day
  • Improved breathing during sleep
  • Less tossing and turning at night

Perhaps one of the biggest improvements was realizing what restful sleep actually feels like. Many people with untreated sleep apnea adapt to exhaustion without realizing how much it affects daily life.

Why Others Should Consider a CPAP Machine

Millions of people live with undiagnosed sleep disorders. Someone who snores heavily, wakes up gasping, feels constantly tired, or struggles to stay awake during the day may benefit from speaking with a healthcare provider or sleep specialist.

Common signs that may indicate sleep apnea include:

  • Loud or chronic snoring
  • Waking up choking or gasping
  • Morning headaches
  • Poor concentration
  • Excessive daytime fatigue
  • Irritability or mood swings
  • Difficulty staying asleep
  • High blood pressure
  • Feeling unrested after a full night’s sleep

Sleep studies have become more accessible in recent years, with many providers offering at-home testing options in addition to traditional sleep labs.

Split image showing a stressed woman working late and the same woman sleeping peacefully
A woman stressed while working contrasts with her peaceful sleeping self.

The Benefits of CPAP Therapy

For people diagnosed with sleep apnea, CPAP therapy can provide significant health benefits when used consistently.

Better Sleep Quality

CPAP therapy helps reduce breathing interruptions, allowing deeper and more restorative sleep cycles.

Improved Cardiovascular Health

Treating sleep apnea may help reduce strain on the heart and lower risks associated with untreated breathing interruptions during sleep.

Increased Energy Levels

Many users report improved daytime energy and reduced fatigue after adapting to therapy.

Enhanced Mental Health

Consistent sleep can positively impact mood, anxiety levels, memory, and concentration.

Reduced Snoring

For many households, CPAP therapy also improves sleep quality for partners affected by loud snoring.

The Drawbacks and Challenges

While CPAP therapy offers many benefits, it is not perfect and does require adjustment.

Initial Discomfort

Wearing a mask during sleep can feel awkward or uncomfortable at first. Some users may experience claustrophobia or irritation.

Dryness and Congestion

Dry mouth, nasal congestion, or skin irritation can occur, especially during the adjustment period.

Noise and Maintenance

Although modern CPAP devices are quieter than older models, the machine still requires regular cleaning and maintenance.

Travel Challenges

Traveling with a CPAP machine can be inconvenient, especially during flights or overnight trips.

Adjustment Period

Some people adapt quickly while others may need weeks or months to become fully comfortable using the device nightly.

Despite these challenges, many long-term users believe the health benefits far outweigh the drawbacks once the routine becomes established.

The Importance of Taking Sleep Seriously

Sleep is not a luxury. It is one of the most important foundations of physical and mental health. Poor sleep impacts nearly every aspect of daily life, from work performance and mood to heart health and overall longevity.

For anyone struggling with constant fatigue, loud snoring, or restless nights, seeking medical advice may be one of the most important health decisions they can make.

Using a CPAP machine may not be glamorous, but for many people, it can be life-changing.