The Fed Raised Rates Again: Here’s Your 15-Minute Money Checkup

The Federal Reserve raised interest rates again on September 16, 2026, increasing its target range for the federal-funds rate by a quarter of a percentage point to 3.75%–4.00%.

The decision was unanimous, and the Fed pointed to inflation that remains above its 2% goal. Economic activity has continued to expand, consumer spending has remained resilient and the labor market has shown stability but persistent inflation convinced policymakers that another rate increase was necessary.

That is the headline. But what does it actually mean for your money?

It does not mean you should immediately sell your investments, lock every dollar into a certificate of deposit or assume that every loan rate will rise overnight. The federal-funds rate is the overnight rate banks charge one another. It influences many other interest rates throughout the economy, but the effect on individual financial products can vary and may take time.

Instead of trying to predict the Fed’s next move, use this decision as a reason to complete a simple review of three areas: your cash, your debt and your investment portfolio.

You can complete the entire checkup in about 15 minutes.
Illustrated editorial image for the conclusion of a personal finance article: a friendly timer set to fifteen minutes beside three simple icons for cash, debt and portfolio, with a small checklist and a confident forward-moving path. Sophisticated newspaper or health-publication editorial art direction, clean shapes, textured print feel, optimistic navy, teal, coral and cream palette. No readable text, no logos, no photorealism.

First, Check Your Cash

Higher interest rates can be good news for savers, but banks do not automatically pass every rate increase along to their customers.

Open your banking app and look at the annual percentage yield, or APY, currently being paid on your checking and savings accounts. If you have a money-market account or certificates of deposit, review those rates and maturity dates as well.

Many people spend hours researching a stock but never check what their bank is paying on thousands of dollars in cash. If your emergency fund is sitting in an account earning very little, it may be worth comparing alternatives from FDIC-insured banks or federally insured credit unions.

The goal is not simply to chase the highest advertised rate. Your emergency savings should remain safe, accessible and free from unnecessary fees or restrictions.

Before moving money, ask:

  • Is the advertised yield temporary?
  • Is there a minimum balance requirement?
  • Are there monthly fees?
  • How quickly can I access the money?
  • Is the institution federally insured?
  • Would transferring the money affect any automatic payments?

You should also separate emergency savings from money that can remain untouched for a specific period. A competitive savings account may be better for funds you could need tomorrow, while a CD might be appropriate for money you are confident you will not need before its maturity date.

A higher yield is valuable, but liquidity has value too.

Next, Check Your Debt

An interest-rate increase can be more painful for borrowers, particularly those carrying variable-rate debt.

Start by making a quick list of your current balances, interest rates and minimum payments. Identify which debts have fixed rates and which have variable rates.

Credit cards deserve special attention. Many issuers calculate interest daily using the account’s average daily balance. That means paying down part of a carried balance sooner, not merely waiting until the due date, may reduce the total interest charged.

Look at the APR printed on each credit-card statement. If you are carrying balances on multiple cards, consider directing additional payments toward the highest-interest balance while maintaining the required minimums on the others.

However, do not drain your entire emergency fund just to eliminate debt. Without a cash cushion, the next car repair, medical expense or home emergency could send you right back to the credit card.

The right balance depends on your income, job stability, household expenses and access to other resources. For many people, the practical approach is to preserve a reasonable emergency reserve while steadily attacking expensive debt.

Also review home-equity lines of credit, adjustable-rate mortgages and other variable-rate loans. The Fed does not directly set your lender’s rate, but variable borrowing costs may respond to changes in broader market benchmarks.

If you have a fixed-rate mortgage, a Fed increase does not change the rate on your existing loan. New mortgage rates are influenced by several forces, including longer-term bond yields, inflation expectations and economic conditions, not just the latest Fed decision.

Then, Check Your Portfolio- Without Panicking

Interest-rate decisions can move the stock and bond markets, but one Fed meeting should not determine your entire investment strategy.

Higher rates can create pressure for companies that depend heavily on borrowing. They can also make bonds and cash-like investments more competitive with dividend stocks. Real estate investment trusts, utilities and other rate-sensitive investments may experience volatility because investors compare their income potential with yields available elsewhere.

At the same time, certain financial companies may benefit from aspects of a higher-rate environment. The results depend on funding costs, loan demand, credit quality and the structure of each business.

There is no simple rule that says one sector must rise while another must fall.

Rather than guessing which asset will react next, review the investments you already own.

Ask yourself:

  • Why did I originally buy this investment?
  • Has the company or fund’s underlying story changed?
  • Has the position grown too large compared with the rest of my portfolio?
  • Am I holding it for income, growth or a shorter-term trade?
  • Would I still buy it today at its current price?
  • Am I reacting to facts or to fear?

My own strategy includes dollar-cost averaging, dividend income, swing trades and occasionally rotating out of a position after taking profits. But rotation should have a reason behind it.

“Rates went up” is information. It is not, by itself, a complete investment thesis.

A quality company does not automatically become a bad investment because the Fed raised rates by a quarter point. Likewise, a struggling company does not become a bargain merely because its share price declined.

Review first. React second.
Illustrated editorial image for a personal finance article section about reviewing an investment portfolio without panic. Show a calm person at a desk examining a diversified pie chart, simple market lines and a magnifying glass, with balanced growth and caution symbols. Sophisticated newspaper or health-publication editorial art direction, clean shapes, textured print feel, navy, sage, mustard and cream palette. No readable text, no logos, no photorealism.

Avoid the Temptation to Predict Every Move

The Fed’s next scheduled policy decision is October 28, 2026. Between now and then, investors will analyze inflation, employment, consumer spending and comments from Federal Reserve officials.

Markets will attempt to price in the next decision before it happens. Those expectations may change several times as new information becomes available.

You do not need to predict every turn.

Trying to trade every headline can create unnecessary taxes, transaction costs and emotional decisions. A long-term investor may be better served by maintaining diversification, continuing appropriate contributions and rebalancing when allocations move beyond their intended ranges.

Shorter-term traders still need discipline. Before entering a position, decide what would prove the thesis wrong, where profits might be taken and how much capital is at risk.

The goal is not to be right about every Fed meeting. The goal is to make financial decisions that remain reasonable under more than one possible outcome.
Illustrated editorial image for a personal finance article section about checking debt, credit-card APRs, balances and repayment decisions. Show a stack of bills and a credit card balanced against a measuring scale, with a thoughtful rather than alarming mood. Sophisticated newspaper or health-publication editorial art direction, clean shapes, textured print feel, deep blue, coral, cream and muted green palette. No readable text, no logos, no photorealism.

Your 15-Minute Money Checkup

Set a timer and review these three areas:

Cash

Check the yield, fees, accessibility and insurance status of your savings. Determine whether your emergency fund is working as efficiently as it reasonably can without sacrificing safety.

Debt

Write down every balance and APR. Identify variable-rate debt and choose the highest-cost balance that deserves additional attention.

Portfolio

Review your largest positions. Confirm why you own them, whether their weight is appropriate and whether anything fundamental has changed.

You do not need to overhaul everything today. Find the one area with the clearest opportunity and take one measured action.

That could mean transferring idle cash to a more competitive insured account, increasing a credit-card payment or trimming a position that has grown beyond its intended allocation.

One Informed Move Beats Ten Emotional Trades

Interest rates matter. They influence borrowing, saving, business investment and market valuations. But the most important financial decisions are often the quiet ones that happen away from the daily headlines.

The Federal Reserve will continue making decisions based on changing economic conditions. Investors will continue debating what comes next. Markets will continue moving—sometimes rationally and sometimes emotionally.

Your advantage is not knowing the future.

Your advantage is knowing your own numbers.

Check your cash. Check your debt. Check your portfolio. Then make one informed decision that moves you closer to your financial goals.

One informed adjustment is worth more than ten emotional trades.

That is how we continue moving from health to wealth… one step forward at a time.
Illustrated editorial image for a personal finance article section about checking cash, savings yields, emergency funds, liquidity and bank fees. Show a calm open wallet or savings jar, a banking app-style chart without readable text, and a small safety net motif. Sophisticated newspaper or health-publication editorial art direction, clean shapes, textured print feel, navy, teal, cream and warm gold palette. No readable text, no logos, no photorealism.

Disclaimer: This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax or legal advice. Interest rates, account terms and investment risks vary. Consider your financial circumstances and consult an appropriately qualified professional before making significant financial decisions.

Sources
The Wealth Mindset Shift: Why Focusing on Positives Beats Fixating on Income

A growing number of professionals and behavioral economists are challenging the narrative: what if the real key to fulfillment isn’t how much you earn, but how you think about what you have?

This shift in perspective often referred to as a “wealth mindset reset” is gaining traction across industries, from finance to mental health. The premise is straightforward: when individuals focus less on income comparisons and more on positive drivers like stability, growth, and purpose, they tend to experience higher levels of satisfaction and long-term success.

The Problem with Income Obsession

For decades, income has been the most visible and measurable indicator of success. Promotions, bonuses, and salary benchmarks are easy to quantify. But that clarity comes with a downside.

“Constantly measuring yourself against others financially creates a moving target,” says one financial wellness expert. “There’s always someone earning more, which can lead to chronic dissatisfaction even when you’re objectively doing well.”

This phenomenon is closely tied to relative income theory, where happiness is influenced less by absolute earnings and more by how one stacks up against peers. The result? Even high earners can feel financially insecure.

Reframing Success

Instead of anchoring self-worth to income, experts recommend shifting focus toward controllable and meaningful metrics:

  • Financial Stability – Are your essential needs covered? Do you have a safety net?
  • Progress – Are you improving your skills, growing your career, or expanding your opportunities?
  • Autonomy – Do you have control over your time and decisions?
  • Purpose – Does your work align with your values or provide a sense of contribution?

These factors, while less tangible than a paycheck, have a stronger correlation with long-term well-being.

The Psychology of Positive Focus

Research in positive psychology suggests that gratitude and forward-looking thinking can significantly improve both mental health and productivity. When individuals focus on what’s working rather than what’s lacking they’re more likely to make better decisions, take calculated risks, and build sustainable habits.

In practical terms, this could mean recognizing consistent income instead of chasing sporadic spikes, or valuing flexibility in a job over a marginal salary increase.

A Financial Strategy Hidden in Plain Sight

Interestingly, this mindset isn’t just about feeling better it can also lead to smarter financial behavior.

People who aren’t fixated on income alone are more likely to:

  • Save consistently rather than spend to “keep up”
  • Invest with a long-term perspective
  • Avoid high-risk decisions driven by short-term gain
  • Build diversified income streams over time

In essence, focusing on positives creates a more disciplined and resilient financial strategy.

Real-World Application

Consider two individuals earning the same salary. One constantly compares themselves to higher earners, feels behind, and takes on unnecessary financial risks. The other focuses on steady growth, appreciates their progress, and makes calculated decisions.

Over time, the second individual is more likely to build sustainable wealth not necessarily because they earn more, but because they think differently.

In the End

Income will always matter it’s a fundamental part of financial security. But it’s not the full picture. By shifting attention away from “how much” and toward “how well,” individuals can unlock a more balanced, productive, and ultimately rewarding financial life.

In a world obsessed with numbers, the real advantage may belong to those who learn to look beyond them.

The Hidden Connection Between Health and Wealth – From Wall Street to Main Street

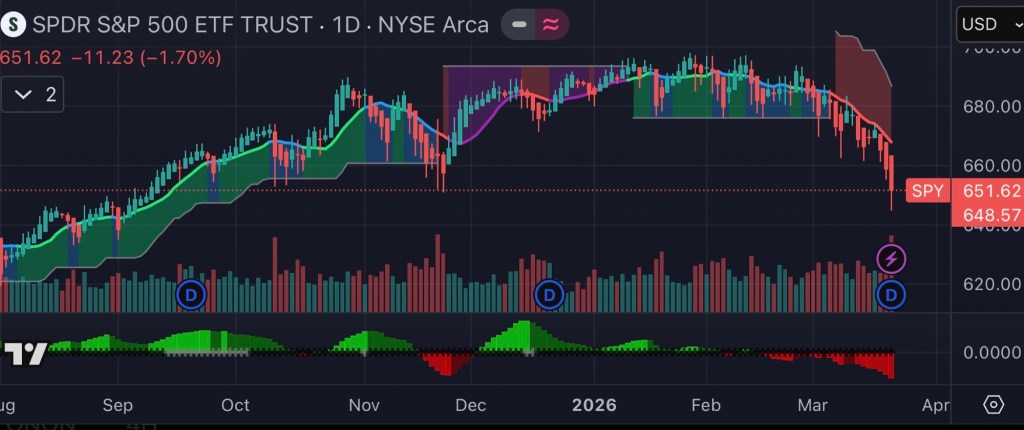
State Street SPDR S&P 500 ETF Trust (SPY) $648.57 -$11.81 (1.79%) • Today $653.51+$4.94 (0.76%) After Hours

By Industry Perspective

The relationship between financial strength and personal health is no longer theoretical, it’s measurable, observable, and, in many cases, predictable. Whether you’re analyzing the volatility of the market through vehicles like the SPDR S&P 500 ETF Trust or underwriting a homeowner’s policy, the same principle applies: risk management drives outcomes both financially and physically.

Market Volatility and Mental Health: The Silent Correlation

As illustrated in the market activity above, even broad-based investments can experience short-term declines. While seasoned investors understand this as normal market behavior, the psychological response is often anything but rational.

Periods of drawdown like recent fluctuations in the S&P 500 can trigger stress responses similar to those seen in high-risk professions. Elevated cortisol levels, poor sleep, and impulsive decision-making (panic selling, overtrading) are common. In financial terms, this is known as behavioral risk and it can erode long-term returns faster than market downturns themselves.

From a health standpoint, chronic stress is linked to:

  • Cardiovascular disease
  • Weakened immune response
  • Reduced cognitive performance

Translation: Poor financial discipline doesn’t just hurt your portfolio it can degrade your physical health.

Insurance: The Health Buffer You Don’t Think About

In the insurance industry, we view risk through a different but parallel lens. Policies aren’t just financial tools; they are health preservation mechanisms.

Consider this:

  • A homeowner without proper coverage facing a catastrophic loss (fire, hurricane, liability claim) doesn’t just experience financial strain it often leads to anxiety, depression, and long-term instability.
  • Conversely, a properly insured individual has risk transferred, which significantly reduces stress exposure.

This is especially relevant in markets like Florida, where environmental risk is high. Strategic coverage wind mitigation credits, flood insurance, liability umbrellas does more than protect assets. It protects peace of mind, which is directly tied to long-term health outcomes.

Wealth Building as a Health Strategy

There’s a growing body of thought especially among financial planners and risk professionals that wealth is a form of preventative medicine.

Here’s how:

  1. Liquidity Reduces Stress
    Emergency funds and accessible capital eliminate the “fight-or-flight” response during crises.
  2. Diversification Mirrors Healthy Living
    Just as a balanced diet prevents overexposure to one risk factor, diversified portfolios reduce systemic financial risk.
  3. Long-Term Planning Promotes Stability
    Retirement accounts, life insurance, and asset protection strategies create predictability one of the most powerful contributors to mental well-being.

The Discipline Overlap: Investors vs. Insureds

The most successful individuals in both investing and insurance share identical behavioral traits:

  • Consistency over intensity (dollar-cost averaging vs. regular policy reviews)
  • Risk awareness without fear-based decisions
  • Long-term thinking over short-term reactions

This overlap is not coincidental it’s structural. Both disciplines reward those who understand that risk isn’t something to avoid it’s something to manage intelligently.

Final Analysis: Health and Wealth Are Not Separate Systems

The traditional view separates financial planning and personal health into different domains. That view is outdated.

  • Poor financial decisions → Increased stress → Negative health outcomes
  • Lack of protection (insurance gaps) → Catastrophic loss → Long-term instability
  • Disciplined investing + proper coverage → Reduced stress → Improved overall well-being

Bottom line:
The same habits that build wealth discipline, planning, risk management are the exact habits that sustain long-term health.

Closing Thought

Whether you’re reviewing your investment portfolio or evaluating your insurance coverage, you’re not just making financial decisions you’re making lifestyle decisions that will compound over time.

Because in the end, the real ROI isn’t just measured in dollars… it’s measured in how well and how peacefully you live.

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.

Effective Money Management for Couples

Financial experts consistently emphasize that couples who treat money as a shared responsibility rather than an individual burden are better positioned to build wealth, reduce stress, and achieve long-term stability.

Research and guidance from organizations like the Consumer Financial Protection Bureau and the Federal Reserve suggest that transparency, planning, and shared accountability are among the strongest predictors of financial success in households.

Why Teamwork Matters in Financial Management

Money represents more than numbers it reflects priorities, values, and long-term aspirations. When couples align financially, they can:

  • Pool income to accelerate savings and investments
  • Share expenses, reducing individual financial strain
  • Build accountability through mutual oversight
  • Plan effectively for major milestones like homeownership, retirement, or raising children

Conversely, when partners operate independently without coordination, misunderstandings and inefficiencies can arise, often slowing progress toward shared goals.

Practical Tips for Managing Money Together

1. Establish Complete Financial Transparency

Each partner should disclose income, debts, assets, and credit obligations. Full transparency builds trust and allows for accurate planning.

2. Define Shared Financial Goals

Successful couples identify both short-term and long-term objectives, such as:

  • Emergency fund targets
  • Vacation savings
  • Retirement timelines
  • Major purchases (home, vehicle, education)

When goals are mutual, financial decisions become easier and more purposeful.

3. Create a Joint Budget Strategy

Couples may choose from several structures:

  • Fully joint accounts
  • Separate accounts with shared expense contributions
  • Hybrid approach (joint bills account plus individual discretionary accounts)

There is no single correct model—the key is consistency and agreement.

4. Assign Financial Roles Based on Strengths

One partner may excel at budgeting while the other focuses on investing or bill management. Dividing responsibilities improves efficiency while maintaining shared oversight.

5. Schedule Regular Financial Check-Ins

Monthly or quarterly discussions help ensure progress, address concerns, and adjust plans as circumstances evolve.

The Psychological Advantage of Financial Partnership

Couples who work together financially often experience reduced stress and improved emotional security. Shared financial clarity reduces uncertainty, one of the most significant drivers of financial anxiety.

Financial partnership also creates resilience. Unexpected events such as job loss or medical expenses are easier to manage when supported by combined resources and coordinated planning.

Comparing Financial Advantages: Couples vs. Singles

Financial FactorBenefits as a CoupleBenefits as Single
Income PotentialCombined income increases earning power and savings capacityFull control over personal income decisions
Living ExpensesShared housing, utilities, and insurance reduce per-person costsNo obligation to support another person financially
Risk ManagementDual income provides safety if one partner loses employmentGreater flexibility to adjust lifestyle quickly
Investment GrowthLarger combined contributions accelerate compounding returnsIndependent investment strategy without compromise
Financial AccountabilityMutual oversight reduces impulsive spendingComplete autonomy over financial decisions
Major PurchasesEasier qualification for mortgages and loans due to combined incomeSimpler approval process based solely on individual credit
Financial FlexibilityShared planning enables long-term stability and goal alignmentGreater freedom to relocate or change careers quickly

The Key to Success: Alignment, Not Perfection

Managing money as a couple does not require identical spending habits or financial philosophies. Instead, success depends on communication, mutual respect, and consistent planning.

Financial partnership is ultimately about alignment. Couples who approach money as a team rather than as individuals sharing expenses position themselves to build stronger financial foundations, navigate economic uncertainty, and achieve long-term goals more efficiently.

In an increasingly complex financial world, teamwork remains one of the most powerful wealth-building strategies available.

What Is the No. 1 Piece of Financial Advice I Wish I’d Known When I Was Younger?

If I could go back and give my younger self just one piece of financial advice, it would be this: start earlier no matter how small the amount and stay consistent.

When you’re young, money feels like something you’ll “figure out later.” Bills are manageable, time feels endless, and retirement sounds abstract. I believed that once I made more money, I’d start investing, saving, and planning seriously. What I didn’t understand then and understand clearly now is that time is the most powerful asset you will ever have in building wealth.

The difference between starting at 22 versus 32 isn’t just ten years of contributions. It’s decades of compounded growth that you can never fully recover. That realization reshaped how I think about money, risk, and discipline and it’s the foundation of every sound financial decision I make today.

To help others forge a smarter, more intentional path, here is a practical list I wish I had followed earlier.


1. Start Before You Feel Ready

You don’t need the perfect job, perfect budget, or perfect market conditions. Waiting for “ready” is often just procrastination disguised as prudence. Even small, imperfect steps compound into meaningful results over time.

2. Consistency Beats Brilliance

You do not need to be a stock-picking genius or market-timing expert. Regular contributions whether monthly, automatic, and boring will outperform most emotional or reactive strategies. Discipline matters more than intelligence.

3. Pay Yourself First

Saving what’s left over rarely works. Treat saving and investing like a non-negotiable bill. When money is set aside first, you learn to live well on what remains.

4. Understand Compound Interest Early

Compound interest is not linear… it accelerates. The early years do the heaviest lifting. Missing those years is far more damaging than missing higher contributions later in life.

5. Avoid Lifestyle Inflation

Earning more does not mean you need more. Every raise is an opportunity to strengthen your financial foundation, not weaken it with permanent new expenses.

6. Build an Emergency Fund Before Chasing Returns

Unexpected expenses are not rare they are guaranteed. An emergency fund prevents debt, protects investments, and buys peace of mind. It is a financial shock absorber.

7. Learn the Difference Between Good Debt and Bad Debt

Not all debt is equal. High-interest consumer debt quietly erodes your future. Understanding this early can save years of financial stress.

8. Invest in Financial Literacy

No one will care about your money more than you do. Learning the basics budgeting, investing, taxes, and risk pays dividends for life.

9. Ignore Noise, Focus on the Plan

Markets move. Headlines change. Emotions fluctuate. A long-term plan grounded in fundamentals is far more powerful than reacting to short-term fear or hype.

10. Time Is More Valuable Than Money

You can earn more income, but you cannot earn more years. Every financial decision should respect that reality.


The Payoff

The greatest financial advantage isn’t luck, timing, or even income it’s starting early and staying consistent. I wish I had known that wealth is built quietly, patiently, and long before it becomes visible.

If you’re younger and reading this, start now even if it feels small. If you’re older, start today. The best time may have been years ago, but the second-best time is always now.

Transform Your Spending: Smart Tips for Retirement Savings

Americans feel as though saving for retirement is becoming increasingly out of reach. Yet for most households, the problem is not income alone it is spending habits. Small, recurring expenses and lifestyle inflation quietly erode long-term wealth, often without people realizing the cumulative damage.

Understanding what people commonly waste money on and redirecting those dollars toward smarter priorities can be the difference between financial stress and financial security later in life.

Common Ways People Waste Money

1. Convenience Spending
Daily purchases such as coffee, food delivery, and grab-and-go meals are among the biggest silent budget killers. A $15 lunch or a $6 coffee may seem insignificant, but over the course of a year these habits can add up to thousands of dollars that could otherwise be invested.

2. Subscription Overload
Streaming platforms, premium apps, cloud storage, fitness apps, and unused memberships quietly drain bank accounts each month. Many consumers pay for services they rarely use or forget they even have.

3. Lifestyle Inflation
As income rises, spending often rises with it larger homes, newer cars, more expensive vacations. While lifestyle upgrades feel deserved, they frequently come at the expense of increased savings and investing.

4. High-Interest Debt
Interest on credit cards and personal loans represents money spent with no lasting benefit. Carrying balances month to month can severely limit the ability to save or invest for the future.

5. Impulse Purchases
Online shopping, flash sales, and “buy now, pay later” offers make it easier than ever to spend emotionally rather than intentionally.

What You Should Be Spending Money On Instead

Redirecting money away from waste does not mean deprivation it means prioritization. The goal is to spend in ways that build stability, flexibility, and long-term wealth.

1. Retirement Contributions
Consistently funding retirement accounts such as a 401(k), IRA, or Roth IRA should be a top priority. Employer matches, tax advantages, and compound growth make these contributions far more powerful than most short-term purchases.

2. Emergency Savings
A properly funded emergency fund typically three to six months of essential expenses prevents unexpected costs from turning into high-interest debt.

3. Debt Reduction
Paying down high-interest debt offers a guaranteed return on your money. Eliminating credit card balances improves cash flow and accelerates your ability to invest.

4. Health and Insurance Protection
Preventive healthcare, adequate insurance coverage, and wellness spending may not feel exciting, but they reduce the risk of catastrophic financial setbacks later in life.

5. Skills and Education
Spending money to improve earning potential through certifications, professional development, or continuing education often delivers a far greater return than consumer purchases.

6. Low-Cost Experiences That Align With Values
Intentional spending on experiences that bring lasting satisfaction rather than habitual convenience purchases can improve quality of life without undermining financial goals.

The Bigger Picture

Saving for retirement is not about cutting all enjoyment from your life. It is about recognizing trade-offs. Every dollar spent today is a dollar that cannot grow for tomorrow. By becoming more aware of where money is wasted and intentionally reallocating those funds, individuals can regain control of their financial future without waiting for a higher income or a perfect market environment.

The most effective financial plans are not built on drastic changes, but on consistent, thoughtful decisions made over time.

How to Build Wealth: 12 Timeless Financial Tips

With financial advice, most guidance comes with caveats, fine print, and a familiar refrain: “It depends.” While nuance has its place, long-term financial stability is built on a small set of non-negotiable principles. These rules hold up across income levels, market cycles, and life stages. They are not trendy. They are not complicated. And they work consistently.

Below is a clear, practical list of rock-solid financial rules that stand the test of time. Bookmark them. Revisit them. Live by them.


1. Spend Less Than You Earn… Always

This is the foundation of every sound financial plan. No investment strategy, side hustle, or tax trick can compensate for chronic overspending. If your expenses exceed your income, wealth accumulation is mathematically impossible.

Rule: Control spending first. Everything else is secondary.


2. Pay Yourself First

Saving what’s “left over” doesn’t work because there’s rarely anything left. Automating savings before discretionary spending removes willpower from the equation.

Rule: Savings is not optional. It is a fixed expense.


3. Build an Emergency Fund Before You Invest

Life will interrupt your plans, job loss, medical expenses, unexpected repairs. An emergency fund prevents short-term crises from becoming long-term financial damage.

Rule: Maintain 3–6 months of essential expenses in cash or cash equivalents.


4. Avoid High-Interest Debt Like the Plague

High-interest debt (especially credit cards) compounds against you, eroding progress faster than most investments can offset.

Rule: If the interest rate is double digits, eliminate it aggressively.


5. If You Don’t Understand It, Don’t Invest in It

Complexity is often used to disguise risk. If you cannot clearly explain how an investment works, how it makes money, and what could cause it to fail, you are speculating not investing.

Rule: Clarity beats excitement every time.


6. Time in the Market Beats Timing the Market

Consistently investing over time outperforms trying to predict short-term market movements. Emotional decision-making is the enemy of long-term returns.

Rule: Invest regularly. Stay invested. Ignore the noise.


7. Diversification Is Non-Negotiable

Concentration creates the illusion of wealth; diversification preserves it. No single stock, sector, or asset class deserves absolute confidence.

Rule: Spread risk intentionally without over complicating.


8. Lifestyle Inflation Is a Silent Wealth Killer

Earning more does not automatically mean living better unless the additional income is managed wisely. Increasing expenses in lockstep with income delays financial independence indefinitely.

Rule: Upgrade your savings rate before upgrading your lifestyle.


9. Protect What You’re Building

Insurance is not an investment it’s risk management. Adequate coverage safeguards years of progress from being wiped out by a single event.

Rule: Insure against catastrophic loss, not minor inconveniences.


10. Long-Term Thinking Wins Every Time

Short-term gratification often conflicts with long-term goals. Financial success favors patience, discipline, and consistency not impulse.

Rule: Make decisions today that your future self will thank you for.


11. Fees Matter More Than You Think

Small percentage fees compound just like returns only in the opposite direction. Over decades, high fees can cost hundreds of thousands of dollars.

Rule: Keep investment and advisory fees as low as reasonably possible.


12. Have a Plan and Review It Annually

A financial plan is not static. Life changes, goals evolve, and assumptions need updating.

Rule: Written plans create accountability. Annual reviews create alignment.


End Result

Financial freedom is not built on clever shortcuts or perfect timing. It is built on unbreakable rules applied consistently over time. These principles require discipline but not genius. Follow them without exception, and the results will follow with certainty.

When in doubt, return to the rules. They will not steer you wrong.

What “Healthy and Wealthy” Means to Me

Success is often measured in numbers—bank accounts, investments, or even social media followers—the deeper meaning of being both healthy and wealthy can sometimes get lost. For me, the phrase isn’t about chasing material excess, but about balance, fulfillment, and sustainability in both body and mind.

Health as the Foundation
Health is more than the absence of illness; it’s the daily practice of treating your body and mind with respect. For me, that includes maintaining energy to do the things I love, fueling my body with good food, and taking time to reduce stress. Without health, even the greatest fortune feels empty. Wealth is meaningless if you don’t have the strength or clarity to enjoy it.

Wealth Beyond Money
When I think of being “wealthy,” I don’t immediately picture luxury cars or sprawling mansions. Instead, I see freedom—the freedom to spend time with loved ones, pursue passions, and give back to the community. True wealth, to me, includes financial security, but also peace of mind, strong relationships, and opportunities to grow.

Healthy and Wealthy Together
The two go hand in hand. Being healthy allows me to work toward financial stability with focus and determination. Being financially stable allows me to invest in my health—whether that’s quality healthcare, nutritious food, or the ability to take time off when I need it. Together, they create a cycle that builds not just a lifestyle, but a legacy.

A Personal Vision
Ultimately, “healthy and wealthy” means living in a way that supports long-term happiness. It’s about waking up each day with energy, knowing I have the resources to handle life’s challenges, and feeling grateful for both the small and big wins. To me, that’s real success—being rich in health, rich in love, and rich in purpose.

How to Cut Costs and Save Money Everyday

When inflation continues to chip away at household budgets, finding ways to save on daily expenses can have a big impact over time. Fortunately, a few small changes to your routine can lead to significant savings without drastically altering your lifestyle.

Here are some practical strategies to cut costs on common daily expenses:

  1. Cut the Coffee Shop Habit
    If you’re stopping by your local café every day, you’re likely spending more than you think. Brewing your coffee at home can save hundreds per year, and with so many quality at-home brewers on the market, the taste doesn’t have to suffer.
  2. Switch to Generic Brands
    From groceries to medicine, store-brand products often offer the same quality as name brands at a fraction of the price. A weekly grocery trip can be trimmed by 20–30% just by switching brands.
  3. Reduce Energy Use
    Turn off lights when you leave the room, unplug electronics not in use, and consider upgrading to energy-efficient bulbs and appliances. Small efforts add up on your utility bill.
  4. Use Public Transportation or Carpool
    Gas, maintenance, and parking costs can eat into your budget. Using public transit or sharing a ride just a few times per week can make a noticeable difference.
  5. Cook at Home More Often
    Dining out “even fast food” can cost two to three times more than a home-cooked meal. Planning meals and prepping ingredients ahead of time can save both money and stress.
  6. Shop Smarter
    Use cashback apps, look for sales, and take advantage of store loyalty programs. Planning your shopping trips and making a list can prevent impulse buys.
Expense CategoryStrategyEstimated Monthly Savings
Coffee/DrinksBrew at home\$60
GroceriesSwitch to generic/store brands\$50
ElectricityUse LED bulbs, unplug devices\$30
TransportationCarpool/public transport\$80
Dining OutCook at home more frequently\$100
ShoppingUse discounts, avoid impulse buys\$40
Total Potential Savings\$360/month

While saving $360 per month may not sound dramatic at first glance, it adds up to $4,320 per year enough for a vacation, a healthy emergency fund, or investing in long-term financial goals.

Bottom line: Small, mindful changes to your daily routine can make a big difference. By identifying where your money goes and being proactive, you can take control of your finances one dollar at a time.

SOFI Stock: A Promising Investment Opportunity for the Future

SoFi Technologies Inc. (NASDAQ: $SOFI) has been making waves in the financial services industry with its innovative approach to digital banking and lending. As a disruptor in the fintech space, SoFi is well-positioned to capitalize on the evolving preferences of tech-savvy consumers and investors alike. Here’s why SOFI stock could be a strong addition to your portfolio for the future.

  1. Expanding Product Ecosystem

SoFi offers a comprehensive range of financial products and services, including student loan refinancing, personal loans, mortgages, investment management, and checking and savings accounts. This diversified product suite not only caters to various customer needs but also promotes cross-selling opportunities within its ecosystem. The company’s “SoFi Relay” and “SoFi Invest” platforms have particularly gained traction among younger consumers who seek a seamless, all-in-one financial solution.

  1. Strong Growth Metrics

SoFi has reported impressive growth in recent quarters, driven by its increasing customer base and expanding revenue streams. The company’s membership count recently surpassed the 10 million mark, reflecting a year-over-year growth of over 40%. Such robust growth metrics highlight the effectiveness of SoFi’s business strategy and its ability to scale operations efficiently.

  1. The Digital Banking Revolution

The global banking landscape is undergoing a significant transformation, with digital-first platforms gaining popularity over traditional brick-and-mortar institutions. SoFi’s fully digital infrastructure and user-friendly mobile app place it at the forefront of this revolution. As more consumers shift to digital banking, SoFi’s market share is expected to grow, further solidifying its position in the fintech industry.

  1. Unique Competitive Advantages

One of SoFi’s standout features is its recently acquired banking charter. This allows the company to offer banking services without relying on third-party partnerships, reducing costs and improving profit margins. Moreover, SoFi’s proprietary technology and data-driven insights give it a competitive edge in delivering personalized financial solutions.

  1. Tailwinds from Student Loan Refinancing

With the federal student loan moratorium ending, SoFi’s student loan refinancing segment is expected to see a surge in demand. This development could significantly boost the company’s revenue in the near term, adding to its already strong growth trajectory.

  1. Analyst Optimism

Many analysts remain bullish on SOFI stock, citing its growth potential and strategic initiatives. The company’s focus on profitability, coupled with its expanding market reach, has garnered positive sentiment from Wall Street. Some analysts have even raised their price targets, suggesting substantial upside potential for the stock.

Risks to Consider

While SoFi’s growth story is compelling, investors should be mindful of potential risks, such as regulatory changes, competition from other fintech players, and macroeconomic factors that could impact consumer borrowing trends. Additionally, the company’s path to sustained profitability remains a critical factor to monitor.

SoFi Technologies is revolutionizing the financial services industry with its innovative products and customer-centric approach. Its strong growth metrics, expanding product ecosystem, and strategic advantages make SOFI stock a promising investment for the future. While risks exist, the company’s long-term growth potential and market leadership position offer an attractive opportunity for investors seeking exposure to the burgeoning fintech sector.

Disclosure: I currently hold a position in SoFi Technologies, Inc. ($SOFI). This article reflects my personal opinions and analysis, and is not intended as financial advice. Please conduct your own research or consult a financial advisor before making any investment decisions.