Planning to Work After You Retire? Learn How Extra Income May Affect Your Benefits, Taxes and Medicare Costs

Retirement doesn’t necessarily mean the end of a paycheck. For millions of Americans, working part-time, consulting, starting a small business or even returning to a full-time career can provide additional income, social connection and a sense of purpose.

But there is an important financial catch: earning money after claiming retirement benefits can affect more than just your bank account.

Depending on your age and income, working in retirement can influence your Social Security benefits, federal taxes and even what you pay for Medicare.
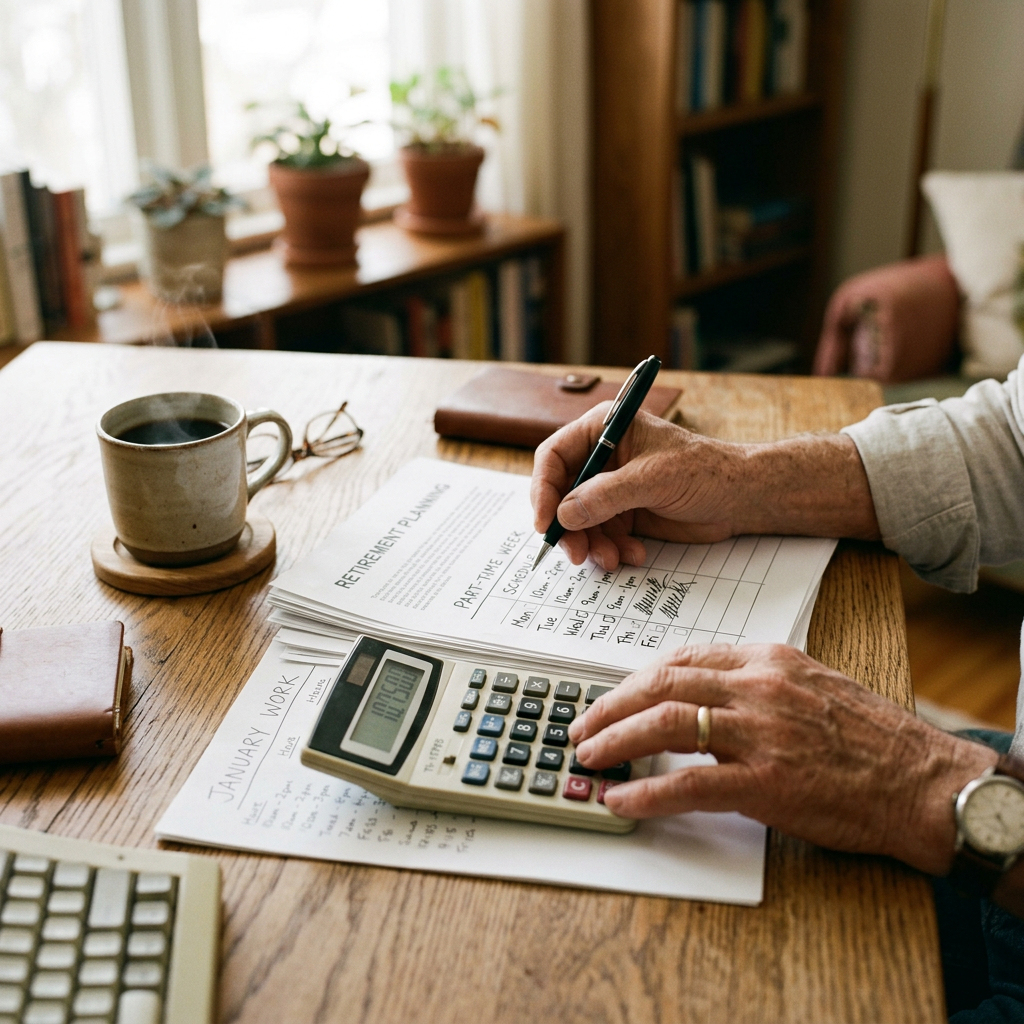
Person writing on retirement planning documents while using a calculator
A person reviews retirement plans and calculates finances at a warm, sunlit desk.

Working While Collecting Social Security

One of the biggest misconceptions about retirement is that you cannot work while receiving Social Security. You can.

However, if you claim Social Security before reaching full retirement age, your earnings may trigger the Social Security retirement earnings test.

For 2026, if you are under full retirement age for the entire year, Social Security will deduct $1 from benefits for every $2 earned above $24,480.

If you reach full retirement age during 2026, the limit increases to $65,160, with $1 withheld for every $3 earned above that amount until the month you reach full retirement age. Once you reach full retirement age, there is no earnings limit.

Importantly, money withheld under the earnings test isn’t necessarily gone forever. Social Security recalculates benefits at full retirement age to account for months when benefits were withheld because of excess earnings.

A simple example

Suppose a 64-year-old begins receiving Social Security and earns $40,000 from a job in 2026.

The first $24,480 is below the earnings limit.

That leaves $15,520 above the limit. Social Security would withhold approximately $7,760 in benefits under the $1-for-$2 rule.

That doesn’t necessarily mean working is a bad financial decision. The additional wages could still leave the individual substantially better off overall but the calculation needs to include the reduced current benefit.

Your Paycheck Can Also Increase Your Tax Bill

Retirement income isn’t automatically tax-free.

Wages, self-employment income, pensions, IRA withdrawals and other taxable income can increase your overall tax liability. In addition, Social Security benefits can become taxable when your combined income reaches certain levels.

The IRS generally looks at one-half of your Social Security benefits plus other income, including tax-exempt interest, when determining whether benefits may be taxable.

That means a retiree who takes a part-time job may unintentionally push more of their Social Security benefits into taxable income.

And don’t forget payroll taxes. Even when you’re already receiving Social Security, wages can still be subject to federal income-tax withholding, Social Security tax and Medicare tax.

Medicare Could Become More Expensive, Too

Here’s the part many retirees don’t see coming.

Higher income can affect Medicare premiums through something known as IRMAA the Income-Related Monthly Adjustment Amount.

IRMAA can increase what you pay for Medicare Part B and Part D when your income exceeds specified thresholds. For 2026, the standard Part B premium is $202.90 per month, although higher-income beneficiaries can pay substantially more.

For 2026, the initial IRMAA threshold is based on modified adjusted gross income above $109,000 for individuals or $218,000 for married couples filing jointly. Medicare generally uses tax information from two years earlier when determining these income-related premiums.

That creates an important planning issue.

The extra income you earn today could potentially affect your Medicare premiums two years from now.

Don’t Forget the Social Security Wage Tax

Working in retirement can also mean continuing to pay into Social Security.

In 2026, Social Security payroll taxes apply to earnings up to $184,500. Medicare taxes, however, continue to apply to earnings without that Social Security wage cap.

For someone returning to a high-paying career after retirement, that distinction can become significant.

Working Longer Can Have an Upside

The financial consequences aren’t all negative.

Continuing to work can provide several advantages:

  • Additional cash flow without immediately drawing as heavily from retirement savings.
  • More years of Social Security-covered earnings, which can potentially increase a benefit calculation.
  • Delayed withdrawals from retirement accounts, allowing investments more time to potentially grow.
  • Employer health coverage, if available and appropriate.
  • Social and psychological benefits from staying active and engaged.
  • The ability to potentially delay Social Security and receive a larger monthly benefit later. Social Security says retirement benefits can generally be claimed between ages 62 and 70, with monthly benefits increasing the longer you wait to claim, up to age 70.

For some retirees, working isn’t simply about making ends meet. It can be a deliberate part of a broader retirement strategy.

The Bottom Line: Don’t Look at Salary in Isolation

A $30,000 part-time job isn’t necessarily a $30,000 improvement to your retirement finances.

The real question is:

How much of that additional income will you actually keep after considering Social Security, federal and state taxes, Medicare premiums and other retirement-income sources?

Before accepting a job or starting a business in retirement, consider running several scenarios:

Work less → work more → delay Social Security → claim Social Security now.

Compare the after-tax income and long-term effects of each option rather than focusing solely on the paycheck.

And remember that everyone’s situation is different. Filing status, age, Social Security claiming date, retirement-account withdrawals, investment income and Medicare status can materially change the outcome.
Gravel garden path beside a river, bench, flowers, and briefcase at sunset
A quiet garden path leads toward a reflective river beneath a warm sunset sky.

Retirement Isn’t a Finish Line- It’s a Financial Transition

For today’s retirees, the traditional idea of completely stopping work at 65 is increasingly becoming just one option among many.

Working during retirement can be financially rewarding, but it requires coordination between Social Security, taxation, retirement savings and Medicare.

The smartest approach isn’t necessarily to avoid earning additional income.

It’s to understand what that income does to the rest of your financial picture before you earn it.

This article is for educational purposes only and is not individualized tax, legal, Social Security or financial advice. Consider consulting a qualified financial professional, tax professional or Social Security representative before making retirement-income decisions.

Sources: Social Security Administration, Medicare.gov and Internal Revenue Service.

Social Security Administration – Retirement Benefits
Medicare.gov – Medicare Costs
IRS – Social Security Income

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
Protecting Yourself Financially and Legally After the Death of a Spouse

The death of a spouse is one of life’s most difficult experiences emotionally, but it can also create immediate financial, legal, and insurance challenges. Experts say surviving spouses who take organized and timely action can avoid costly mistakes, reduce stress, and protect their family’s long-term financial future.

From estate administration to updating insurance policies and securing financial accounts, understanding the steps that should be taken after a spouse passes away is critical.

Desk with project binder labeled 'PROJECT ALANNAH - 2024', stack of papers, pen, daily notes notebook, keys, and desk lamp

The Importance of Acting Early

Many surviving spouses are unaware that insurance policies, bank accounts, mortgages, vehicle titles, and retirement accounts may need immediate attention after a death occurs. Delays can lead to denied claims, lapsed coverage, frozen accounts, missed bills, or probate complications.

Financial planners and estate professionals recommend starting with a structured checklist and keeping copies of all important documents in one secure location.

Key Areas That Need Immediate Attention

1. Obtain Multiple Certified Death Certificates

Funeral homes often assist families with ordering death certificates. Financial institutions, insurance carriers, and government agencies usually require certified copies.

Experts recommend obtaining at least 10 copies to simplify the process.

2. Contact Life Insurance Companies

If the deceased spouse had life insurance through work or an individual policy, beneficiaries should file claims as soon as possible.

Important items to gather include:

  • Policy numbers
  • Death certificate
  • Beneficiary information
  • Employer contact information

Life insurance proceeds are often paid tax-free and can help cover immediate expenses.

3. Review the Estate and Will

If a will or trust exists, the executor or trustee should begin the legal administration process promptly.

Key documents may include:

  • Last will and testament
  • Trust agreements
  • Power of attorney documents
  • Property deeds
  • Financial account information

Consulting an estate attorney may help avoid probate complications and ensure assets transfer properly.

Homeowners Insurance Should Never Be Ignored

One commonly overlooked issue is homeowners insurance. After a spouse dies, surviving family members should notify their insurance company immediately.

Why this matters:

  • The named insured may need to be updated
  • Vacant home provisions could apply
  • Coverage limits may need adjustment
  • Mortgage lender requirements could change

Failure to update a homeowners policy may create claim issues later.

Homeowners should also verify:

  • Current replacement cost coverage
  • Flood or hurricane insurance status
  • Mortgage escrow arrangements
  • Liability protection limits

Auto Insurance Updates Are Critical

Vehicle ownership and auto insurance policies often require updates after a spouse passes away.

Checklist items include:

  • Updating vehicle registration and title
  • Removing or adding drivers
  • Revising garaging address if necessary
  • Reviewing coverage levels
  • Confirming premium payment arrangements

If the deceased spouse handled finances, surviving spouses should confirm policies remain active to avoid accidental lapses in coverage.

Social Security and Government Benefits

The surviving spouse may qualify for benefits through the Social Security Administration.

Potential benefits may include:

  • Survivor benefits
  • Lump-sum death payment
  • Medicare updates
  • Dependent child benefits

Veterans and government employees may also have pension or survivor programs available.

Protecting Against Fraud and Identity Theft

Identity theft targeting deceased individuals is increasingly common.

Experts recommend:

  • Notifying credit bureaus
  • Monitoring financial statements
  • Closing unnecessary accounts
  • Reporting the death to banks and creditors
  • Securing digital accounts and passwords

Mail theft and fraudulent credit applications can occur if accounts remain open.

Emotional Decisions Should Be Avoided

Financial advisors frequently caution widows and widowers against making major financial decisions immediately after a loss.

Avoid rushing decisions involving:

  • Selling the home
  • Large investments
  • Giving money to family members
  • Cashing out retirement accounts
  • Major relocations

Taking time to evaluate options with trusted professionals may help prevent long-term financial setbacks.

Survivor Protection Checklist

Checklist with green checkmarks, shield icon with house and car, documents, and house and car illustrations
A checklist symbolizing home and car insurance coverage and protection.

Immediate Tasks (First Few Days)

  • Obtain certified death certificates
  • Notify close family members
  • Contact funeral home and clergy
  • Secure home, vehicles, and valuables
  • Locate will, trust, and insurance documents
  • Notify employer of death

Financial & Legal Tasks

  • Contact life insurance companies
  • Meet with estate attorney if necessary
  • Notify banks and investment firms
  • Review mortgage and loan obligations
  • Update beneficiaries on accounts
  • Review retirement and pension benefits
  • Notify Social Security Administration
  • Monitor credit reports

Insurance Tasks

  • Update homeowners insurance
  • Review auto insurance policies
  • Confirm health insurance continuation
  • Review umbrella liability coverage
  • Verify flood, windstorm, or specialty coverage
  • Update named insured information

Property & Asset Tasks

  • Transfer vehicle titles if necessary
  • Update deeds and property ownership
  • Inventory valuables and collectibles
  • Secure firearms, jewelry, and important documents
  • Review safe deposit boxes

Digital & Identity Protection

  • Close unused online accounts
  • Update passwords
  • Preserve important photos and files
  • Notify credit bureaus
  • Monitor for identity theft

Family & Long-Term Planning

  • Review household budget
  • Meet with financial advisor
  • Update your own estate plan
  • Reevaluate retirement strategy
  • Review tax filing requirements
  • Create an emergency contact file

Final Thoughts

The loss of a spouse can feel overwhelming, especially when legal and financial responsibilities suddenly fall on one person. While every situation is unique, staying organized and addressing insurance, estate, and financial matters early can help protect surviving family members from unnecessary hardship.

Professionals recommend building a trusted support team that may include an estate attorney, financial advisor, accountant, and insurance professional to help navigate the transition with confidence and stability.

About the Author:

David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
Ensuring Financial Security in the Face of Unforeseen Challenges

In a world filled with uncertainties, one aspect that often goes overlooked is the potential for unexpected health challenges that can impact our ability to work. Disability insurance emerges as a crucial safeguard, offering a financial safety net to individuals facing unforeseen circumstances.

Disability insurance provides protection for workers who find themselves unable to perform their job duties due to illness or injury. While many individuals recognize the importance of life insurance, the significance of disability insurance is often underestimated.

Here are some key reasons why disability insurance should be a priority for everyone:

Financial Stability During Health Challenges

Imagine a scenario where an unexpected accident or illness leaves you unable to work for an extended period. Disability insurance steps in to provide a portion of your income, ensuring that you can meet your financial obligations, such as mortgage payments, utility bills, and daily living expenses.

Protecting Your Most Valuable Asset – Your Income

For most individuals, their ability to earn a living is their most valuable asset. Disability insurance acts as a shield for your income, offering peace of mind knowing that, even in challenging times, you can maintain a certain level of financial stability.

Peace of Mind for You and Your Loved Ones

Knowing that you have a safety net in place can alleviate the stress and anxiety that often accompany unexpected health challenges. Disability insurance not only benefits you but also provides reassurance to your loved ones that their financial well-being is secured in the event of unforeseen circumstances.

Employer Coverage Might Not Be Enough

While some employers offer disability coverage as part of their benefits package, it’s crucial to assess whether the provided coverage is sufficient for your needs. Personal disability insurance allows you to tailor coverage to your specific circumstances, ensuring that you have the protection you require.

Planning for the Long Term

Disability insurance is not just a short-term solution; it provides long-term support if you face a disabling condition that requires an extended period away from work. This long-term perspective makes disability insurance an integral part of your overall financial planning.

In conclusion, disability insurance is a valuable investment in your financial security and well-being. It offers a safety net that can make a significant difference in your ability to navigate unforeseen health challenges without compromising your financial stability. As the saying goes, “hope for the best, but prepare for the worst.” Disability insurance is a proactive step towards securing a stable and worry-free future. If you need help picking the right disability insurance plan please feel free to reach out, drop me a line, or give me a call and we can find you the best plan. Otherwise and as usual keep smiling cause it really looks good on you!

A New Chapter: The Remarkable Benefits of Turning 65

As individuals reach the milestone of turning 65, they embark on a journey filled with numerous benefits and opportunities that come with this significant age. Far from just a number, reaching 65 opens doors to a range of advantages that can enhance one’s quality of life and well-being.

1. Financial Freedom: One of the most notable perks of turning 65 is eligibility for Medicare, the federal health insurance program primarily for seniors. This coverage helps alleviate the financial burden of medical expenses, ensuring access to essential healthcare services without the worry of exorbitant bills. Additionally, seniors may enjoy other financial benefits, such as pension plans, Social Security, and senior discounts, providing a sense of economic security.

2. Leisure and Travel Opportunities: Retirement often accompanies the age of 65, offering newfound freedom and time to explore the world. Seniors can take advantage of discounted travel options, ranging from cruises to airfare and accommodations. Whether it’s a dream vacation or a spontaneous getaway, the age of 65 grants individuals the chance to indulge in leisurely pursuits they may not have had the time for earlier in life.

3. Pursuing Passions and Hobbies: With the demands of work life behind them, individuals at 65 have the luxury of dedicating more time to their passions and hobbies. Whether it’s painting, gardening, writing, or learning a new skill, the retirement years provide an opportunity for self-discovery and personal fulfillment.

4. Community Engagement and Volunteering: Many retirees find immense joy and purpose in giving back to their communities through volunteering. At 65, individuals can explore various volunteer opportunities, contributing their skills and experiences to make a positive impact on society. Engaging in community service not only benefits others but also enhances the retiree’s sense of fulfillment and connection.

5. Lifelong Learning: Age is no barrier to learning, and turning 65 opens doors to educational opportunities. Many universities and institutions offer discounted or even free courses for seniors, allowing them to pursue intellectual interests and continue learning throughout their retirement years.

6. Emotional Well-Being: The age of 65 often brings a sense of accomplishment and the opportunity to reflect on a life well-lived. This introspection can contribute to improved emotional well-being and a greater appreciation for the simple pleasures of life. Seniors may find themselves more focused on relationships, personal growth, and overall happiness.

.

Turning 65 is not just a chronological marker; it represents a gateway to a multitude of benefits and opportunities. From financial security and travel perks to pursuing passions and giving back to the community, the age of 65 is truly a time to savor the rewards of a life well spent. Embracing these opportunities can make the golden years truly golden for individuals entering this exciting chapter of life.