I am a very strong man who is also a proud parent (my son is my world) something that you do not find too often (sort of like those people lucky enough to earn a Doctoral Degree). I love competitive sports "March Madness," as I believe they help foster competition in the workplace. I am continually looking for new challenges and hold myself accountable for all my actions at home and in the workplace. I love to talk (who in sales doesn't), read & conduct research. Finally, through various work and educational experiences I hope someday to become an established & full-time writer.
When it comes to protecting wealth and passing it on to loved ones, many families are discovering that a simple will may not be enough. Increasingly, individuals are turning to trusts as a more effective way to manage their assets and provide security for beneficiaries. While wills remain common, trusts offer unique advantages that make them an essential tool in modern estate planning.
A trust is a legal arrangement in which a trustee manages assets on behalf of beneficiaries. Unlike a will, which becomes public during probate, a trust can keep family financial matters private while ensuring assets are distributed according to the grantor’s wishes.
Avoiding Probate Delays and Costs One of the main reasons individuals choose a trust is to avoid probate—the court-supervised process of distributing an estate after death. Probate can take months or even years, and legal fees can significantly reduce what heirs actually receive. With a trust, assets are transferred more quickly and with fewer administrative costs.
Tax Efficiency and Asset Protection Certain types of trusts can also provide tax advantages. For high-net-worth individuals, this can mean minimizing estate taxes, while others use trusts to shield assets from creditors or lawsuits. Parents of minor children often create trusts to ensure their children’s financial needs are met in the event of an untimely death.
Control Over Distribution Unlike a will, which typically results in a lump-sum transfer of assets, a trust allows for customized distribution. For example, beneficiaries can receive funds at certain ages, in installments, or for specific purposes such as education or healthcare. This level of control provides peace of mind for those worried about heirs’ financial responsibility.
Peace of Mind for Families “Trusts aren’t just for the wealthy,” says estate planning attorney Sarah Mitchell. “They’re tools that provide structure, protection, and clarity—things every family can benefit from. For many clients, it’s about peace of mind knowing their loved ones are taken care of.”
As life expectancy increases and wealth is passed down through generations, experts predict that more families will explore trusts as part of their financial planning. Whether it’s avoiding probate, protecting assets, or ensuring responsible inheritance, trusts are becoming a cornerstone of modern estate planning.
About the Author:
David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
Some quantitative models project a steep upward trajectory. One forecasting service estimates an average December 2025 price of $34.67, with a low of $32.18 and a high of $35.72—implying over 100% upside from current levels (StockScan). If investor sentiment catches up with this model, the stock could indeed flirt with $40 before year-end.
2. Financing Strength and Cash Position
As of March 31, 2025, Oscar Health reported a fortified balance sheet: $4.86 billion in cash, equivalents, and investments, up from $3.97 billion at the end of 2024. Total assets rose 21% YoY, while operating cash flow increased 38% (Michael Burry’s Insights). This cash cushion gives Oscar flexibility to invest in growth, navigate regulatory headwinds, and drive further value.
3. Strategic Expansion Through New Partnerships
Oscar’s deal with Hy-Vee to launch “Hy-Vee Health with Oscar” in Des Moines, covering about 400,000 employees in the individual marketplace starting Jan 1, 2026, signals a bold move into employer-backed coverage. The ICHRA model aims to save businesses 20–30% and deliver substantial cost-savings to employees-this could create significant scale and margin tailwinds (Benzinga).
4. Accelerating Revenue Growth
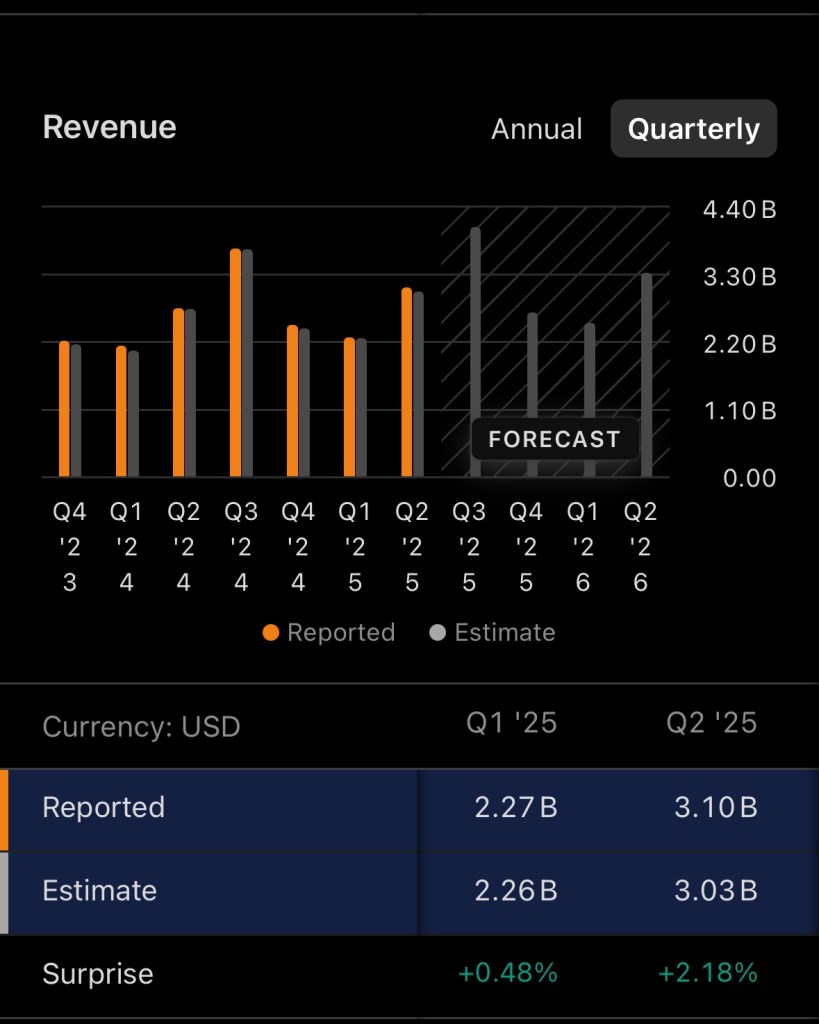
While Q2 revenue of $2.86 billion fell slightly short of the $2.91 billion estimate, it still marked a 29% increase YoY. The company reaffirmed its full-year 2025 revenue guidance at $12–12.2 billion (versus Wall Street’s $11.32 billion estimate), underscoring underlying growth momentum (BenzingaYahoo FinanceStockAnalysis).
5. Valuation Appears Undervalued for Growth Potential
Oscar trades at over 101x forward EV/EBITDA, a lofty multiple—but some analysts argue this valuation is justified by its “quality characteristics” and disruptive business model (StockStory). Others see it as deeply undervalued despite near-term uncertainty tied to ACA policy risks (Seeking Alpha+1).
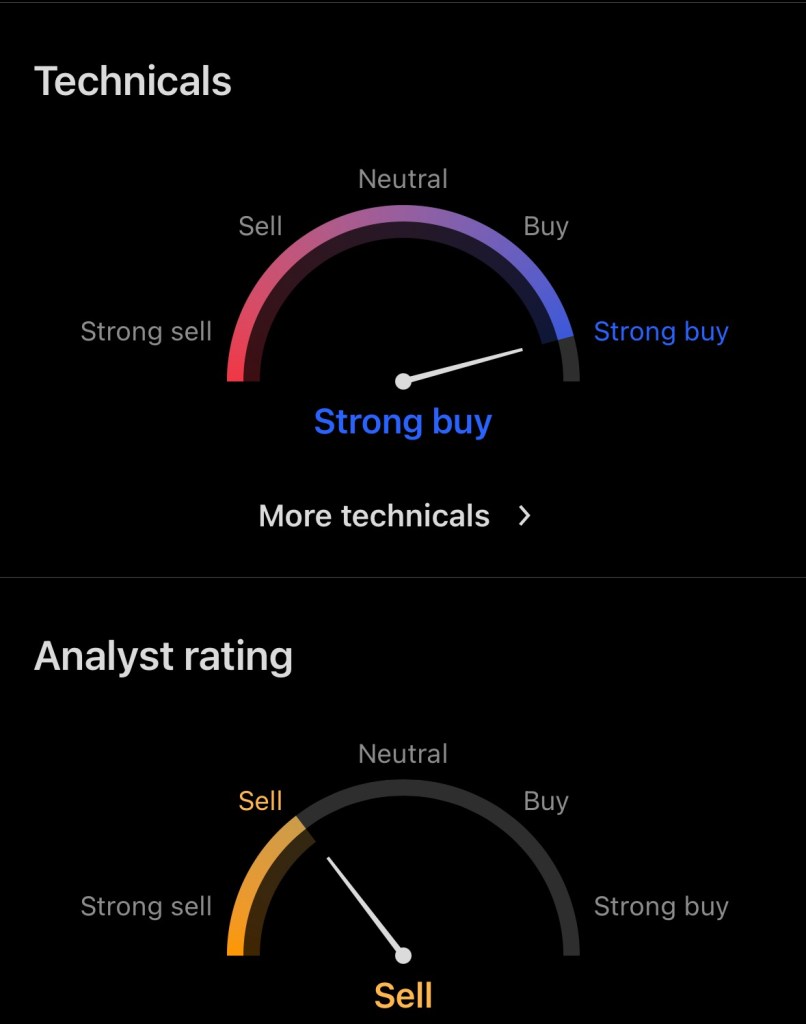
Skeptical Market Sentiment: Many brokerages hold “Sell,” “Hold,” or “Neutral” ratings. Notably, Piper Sandler cut its target from $14 to $13, citing uncertainties around risk adjustments and path to profitability (Benzinga). MarketBeat’s consensus is “Strong Sell,” and TipRanks flags a “Downside potential” of ~30% (MarketBeat).
Profitability Still Out of Reach in 2025: OSCR is expected to operate at a loss—losses projected around $200–300 million for the year (Yahoo Finance). Its Q2 GAAP loss was $0.89/share, and medical loss ratio (MLR) swelled from 79% in 2024 to 91.1% in Q2 2025 (BenzingaStockAnalysis). These factors dampen bullish expectations.
Headlines-Style Article: “Oscar Health: Can It Make the Leap to $40 by Christmas 2025?”
New York, August 23, 2025 – Oscar Health Inc. (NYSE: OSCR) currently trades near $16.98, buoyed by stellar revenue growth, robust liquidity, and a landmark new partnership but Wall Street’s confidence remains tepid.
Why $40 isn’t implausible:
Long-term algorithmic forecasts place December 2025 prices in the low-$30s, including a possible high of $35.72 (StockScan).
Strengthened cash position of $4.86 billion, coupled with rising operating cash flows, enhances the company’s financial flexibility (Michael Burry’s Insights).
Innovative ventures like the Hy-Vee collaboration, targeting 400,000 employees, position Oscar to disrupt cost structures and tap new revenue streams (Benzinga).
A confirmed revenue guidance of $12–12.2 billion highlights strong underlying demand despite macro-healthcare headwinds (Yahoo FinanceStockAnalysis).
Profitability is still elusive: projected operational losses of up to $300 million in 2025, and increased medical loss ratios (MLR) eroding margins (BenzingaYahoo FinanceStockAnalysis).
Sentiment skews negative, with ratings from “Hold” to “Strong Sell” prevailing, reflecting elevated policy-related and insurance-market risks (MarketBeat).
Final Thoughts: While consensus targets place Oscar Health under $15, a confluence of strong cash reserves, growth initiatives, and bullish long-term models could propel the stock into the low $30s by Christmas-though doing so would require sustained execution and favorable market sentiment in the face of continued near-term challenges.
Disclaimer: The author holds a position in $OSCR Oscar Healthcare and this article should not be considered financial advice. Always conduct your own research before making any investment decisions.
When it comes to motorcycles, boats, golf carts, and ATVs, most people think about the thrill of the ride, the open water, or a sunny day on the course-not the financial risks. But accidents, theft, and unexpected liabilities don’t take a holiday, and that’s why insurance for your recreational “toys” is worth serious consideration.
Required vs. Optional Coverage
The first step in understanding toy insurance is knowing what’s required by law and what’s optional.
Motorcycles: Like cars, most states require liability insurance if you’re taking your motorcycle on public roads. This covers injury or damage you may cause to others, but not your own bike. Collision and comprehensive coverage—protecting your motorcycle against accidents, theft, or weather damage are optional but highly recommended.
Boats: While boat insurance isn’t federally mandated, some states and marinas require proof of coverage. Even if it’s not required, carrying liability and property protection can shield you from costly repairs or lawsuits if an accident occurs on the water.
ATVs & Dirt Bikes: If you’re riding on private land, insurance is usually optional. However, many state parks, trails, and off-road areas require proof of coverage to operate. Considering the high rate of ATV accidents and theft, insuring your four-wheeler is a smart move.
Golf Carts: Most neighborhoods and golf courses don’t require golf cart insurance, but if you’re using the cart on public roads-or even just around your community-liability coverage can protect you if an accident happens. Some homeowners’ policies provide limited coverage, but standalone golf cart insurance can fill the gaps.
Why You Should Insure Even When It’s Optional
Just because coverage isn’t required doesn’t mean it isn’t essential. Repair costs, medical bills, or liability lawsuits can quickly outweigh the value of your toy itself. Theft is another growing concern-ATVs, motorcycles, and even boats are among the most commonly stolen recreational vehicles.
Insurance not only protects your investment but also your financial stability. For many, the peace of mind of knowing that a fun weekend won’t turn into a financial nightmare is worth the modest premium.
A Smarter Way to Protect Your Fun
Your recreational vehicles are more than just “toys”-they’re part of your lifestyle. Adding the right insurance ensures that your good times don’t come with unnecessary risks. Before the next ride, round of golf, or day on the water, check your coverage and make sure your adventures are backed by protection as strong as your passion.
About the Author:
David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
Life in our home just got a little more exciting. We recently welcomed a new cat into the family, which now brings us to three cats and one dog. It’s a full house, and while it means more food dishes, more fur on the couch, and a bit more chaos, I can already feel the positive impact on my mental health.
For me, pets are more than just companions-they’re a steady source of comfort and joy. On stressful days, there’s something grounding about a cat curling up in my lap or the dog nudging me for a walk. Each animal adds a different type of support. The cats bring a sense of calm, their quiet purrs easing my anxiety, while the dog encourages me to stay active and present.
I’ve noticed that with multiple pets, the benefits seem to multiply. There’s always a warm presence in the house, always a reminder that I’m not alone. It keeps me connected, responsible, and often laughing at their playful antics. Science backs this up too-studies show pets can reduce stress, ease depression, and even help create structure in daily life.
Of course, caring for four animals comes with challenges. It requires patience, time, and commitment. But the rewards-companionship, unconditional love, and a boost to my overall well-being-far outweigh the effort.
As I adjust to life with our newest cat, I’m reminded how much these animals give back. In a world that can feel overwhelming at times, their presence is a gentle reminder that joy can be found in small, furry packages. For me, a purr or a wagging tail isn’t just cute… it’s therapy.
Airbnb delivered $11.1 billion in revenue for 2024, marking a 12% year-over-year increase, driven by higher booking volume and sustained average daily rates. Gross booking value surged to $81.8 billion (+10.6% YoY), while free cash flow hit $458 million in Q4 (18% margin) (AInvest).
Moreover, Airbnb’s global market share in short-term rentals climbed to 44% in 2024, up from 28% in 2019—far ahead of Booking.com (18%) and Expedia/Vrbo (9%) (AInvest).
2. Efficient Asset-Light Business Model
Airbnb’s strategy avoids owning properties, enabling high-margin operations. Their gross margin soared to approximately 83% in early 2024 (The Motley Fool), and their asset utilization metrics demonstrate tightening efficiency. Notably, the net fixed-asset turnover leaped from 12.5 in 2020 to 75.5 in 2024, reflecting strong revenue delivery with minimal asset base (Stock Analysis on Net).
3. Strategic Diversification into Services & Experiences
In recent quarters, Airbnb has repositioned itself beyond homestays into an integrated travel ecosystem-offering localized experiences, services like spa treatments, personal training, and lodging alternatives-all within its revamped app ecosystem (AInvestMarketWatch).
This diversification is not trivial: management projects that the “Services & Experiences” vertical could generate $1 billion in annual revenue within 3–5 years, backed by a $200–250 million investment earmarked for 2025 (AInvestMarketWatch).
4. Recent Strong Earnings Momentum
Airbnb outperformed expectations in Q2 2025:
Earnings per share: $1.03 (+99% YoY vs. $0.94 expected)
Revenue: $3.1 billion (+13% YoY)
Gross bookings: $23.5 billion (+11% YoY)
Despite these strong results, caution around margin trajectory and investment pace weighed on sentiment, causing a ~7% dip in premarket trading Investors.
Simultaneously, long-term confidence remains steady-Akre Capital boosted its Airbnb allocation by 10%, signaling belief in the company’s growth trajectory (AInvest).
5. Favorable Industry Trends
In the broader travel space, analysts remain positive. A recent Barron’s feature highlights secular travel growth outpacing GDP and the rising demand for experiences. Although other travel players like hotels and airlines benefit, OTAs and platforms like Airbnb must adapt and diversify to stay competitive-something Airbnb is actively doing (Barron’s).
Industry Positioning: How Airbnb Compares
Here’s a snapshot comparing Airbnb to its main competitors in the travel lodging and experiences sector:
Company
Market Share (2024)
Business Model
Key Differentiator
Airbnb
44%
Asset-light platform
Large host network, high margins, diversified services
Booking.com
18%
Hybrid (hotels + rentals)
Strong hotel partnerships, AI integration
Expedia/Vrbo
9%
Hybrid OTA
Bundle offerings, traditional OTA presence
Airbnb leads clearly in short-term rental share and continues to build stronger differentiation through vertical integration and digital enhancements (AInvest+1MarketWatchBarron’s).
Points of Caution
Valuation: Forward P/E sits above 30x (e.g., ~34.5x), relatively high compared to peers like Expedia (~10x) or Booking (~18x) (The Motley FooleToro).
Regulatory Headwinds: Local restrictions (e.g., New York City) and evolving laws could curtail growth in certain markets (eToroMarketWatch).
Execution Risk: Scaling new offerings and achieving the $1 billion services target will take time—short-term margins may remain under pressure (AInvestInvestorsMarketWatch).
Final Take
Airbnb demonstrates the hallmarks of a high-upside, long-term growth stock:
Strong financials, efficient operations, and leading share in a growing market.
Expanding revenue streams beyond traditional listings.
Strategic execution evidenced by earnings beats and fund manager conviction.
That said, elevated valuation and near-term execution risks suggest that patient investors may benefit from disciplined entry points or staged allocation.
Disclaimer: The author holds a position in $ABNB AIR BNB and this article should not be considered financial advice. Always conduct your own research before making any investment decisions.
When you hand over your car keys to a friend or family member, you might not think twice. But in the world of auto insurance, that moment is about more than just trust-it’s about something called permissive use.
What Is Permissive Use?
Permissive use simply means you’ve allowed someone else to drive your vehicle with your permission. That permission can be:
Express – You clearly told them they could drive your car.
Implied – It’s understood based on your relationship or past behavior (e.g., your spouse or roommate regularly uses your car without asking each time).
In most standard auto insurance policies, permissive users are covered under the vehicle owner’s liability coverage. That means if the driver gets into an accident while using your car with your consent, your policy can help pay for damages or injuries to others.
Why Understanding Permissive Use Matters
You Could Be Financially Responsible Even if you weren’t behind the wheel, your insurance may still be the first to pay if a permissive user causes an accident. If damages exceed your policy limits, you could be responsible for the difference.
Coverage Isn’t Always Unlimited Some insurance companies provide reduced coverage limits for permissive drivers-especially if they’re not listed on your policy. Others might exclude certain drivers altogether.
Not All Situations Are Covered If the person using your car is engaging in excluded activities-like delivering food for a rideshare app, racing, or using the vehicle without permission—your insurance might not apply.
Claims Can Affect Your Record An accident caused by a permissive user can still appear on your insurance history and may impact your premiums.
How to Protect Yourself When Sharing Your Vehicle
Know Your Policy – Check your policy documents or talk to your agent to understand how your insurer handles permissive use.
Be Selective – Only allow responsible, licensed drivers to use your vehicle.
Clarify Restrictions – If you don’t want someone driving for certain purposes (like work deliveries), make that clear.
List Regular Drivers – If someone uses your car often, consider adding them to your policy to avoid coverage gaps.
Key Takeaway for Drivers
Permissive use may feel like a small favor, but it carries big insurance implications. By knowing the rules, choosing drivers wisely, and keeping your policy updated, you can avoid unpleasant surprises and keep both your car and your finances protected.
About the Author:
David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.
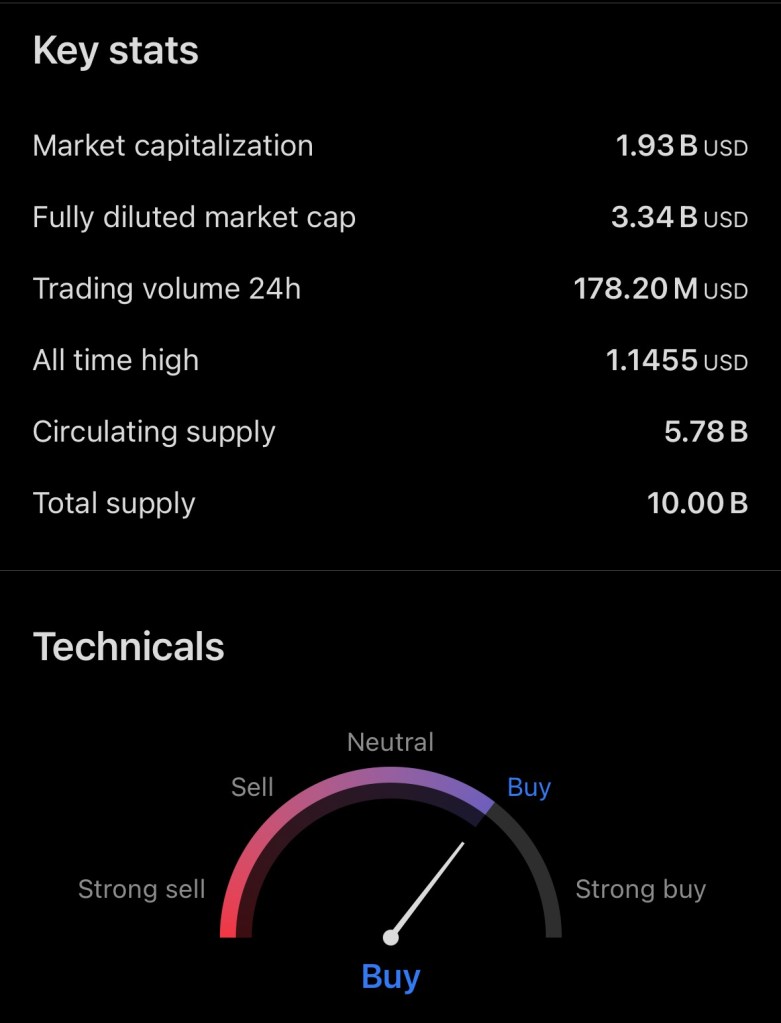
Breakouts & Price Rally: SEI recently broke above the pivotal $0.33–$0.34 resistance, delivering a nearly 40% surge in price within a week. A 10% spike over 24 hours further amplifies growing interest in the token. (The Market Periodical)
Stable Support, Upward Targets: As of August 8, 2025, SEI is holding steady around the key $0.285 support level. Should bullish momentum continue, investors are eyeing Fibonacci resistance targets at $0.48, $0.56, and even $0.67. But a dip below $0.285 could bring a pullback risk. (Blockonomi)
On-Chain Adoption & Ecosystem Growth
Transaction Volume & User Activity: The network is seeing explosive activity. Daily transactions have topped 1.5 million, while active wallets now exceed 616,000. (The Currency analytics)
TVL & DeFi Expansion: Total Value Locked (TVL) has climbed dramatically-from $500M to $680M+ in recent updates, and, according to some reports, has soared to as high as $1.13B. This doubles early-2025 levels, underlining robust DeFi growth. (The Market PeriodicalCryptodamusCoinCentral)
Institutional & Regulatory Recognition: A wave of institutional interest is tied to an ETF filing; SEI’s user base has ballooned to over 8.1 million addresses, placing it as the #2 EVM-compatible chain by user count. TVL jumped 24% to above $535M. (Cryptonews)
Technical and Sentiment Indicators
Technical tools are flashing bullish signals: RSI and MACD suggest further upside potential, particularly if SEI maintains position above its 200-day EMA. (OneSafe)
Analysts highlight a possible higher-low formation, reminiscent of past wave patterns, potentially marking the start of a broader “Wave C” rally. (Blockonomi)
Short-Term: SEI is in a critical zone-holding support at ~$0.285 could drive a breakout toward $0.48 or beyond. High trading volume and technical momentum support this scenario. However, watch for potential pullbacks if the support fails.
Long-Term: Strong ecosystem fundamentals, increasing TVL, active users, and institutional interest (ETF-based momentum) give SEI solid traction. Continued infrastructure development and adoption could support sustained growth, especially as token unlocks are phased in without sudden floods of supply.
Risks to Note:
Supply unlocks (e.g., mid-August) may generate selling pressure.
Over-reliance on DeFi and gaming applications may limit ecosystem diversification. (Gate.com)
Final Take
Sei Network is gaining serious traction, backed by strong on-chain growth, technical momentum, and institutional recognition. For short-term traders, current support zones and bullish setups offer attractive opportunities, so long as key levels hold. For long-term investors, SEI’s expanding ecosystem, increasing utility, and vesting transparency suggest meaningful upside as the chain matures. Always balance optimism with awareness of unlocking events and ecosystem concentration risks.
Disclaimer: The author holds a position in $SEI Network and this article should not be considered financial advice. Always conduct your own research before making any investment decisions.
As August rolls on, I’m preparing for a major life shift-sending not one, but two kids off to college.
This fall, my daughter will begin her journey as a freshman at Florida Gulf Coast University (FGCU), ready to explore a new chapter in the sunshine-filled town of Fort Myers. Meanwhile, my son is entering his second year at the University of South Florida (USF), well on his way toward earning his degree and carving out his own path.
I’m incredibly proud of both of them. But I’d be lying if I said it wasn’t bittersweet.
The house that once echoed with teenage chatter, shared meals, and last-minute school deadlines is starting to feel a little quieter-and emptier.
I’ve been bracing for the ‘empty nest’ for a while. And now that it’s actually happening, it feels surreal.
Watching Their Independence Take Flight
One of the most rewarding parts of parenting-yet also the most emotional-is watching your kids grow into their independence. It’s happening right before my eyes. They’re making decisions for themselves, solving their own problems, setting their own goals. And while I’ll always be their biggest cheerleader, I know this next stage is about them leading their own lives.
My daughter is eager to make new friends, figure out her place in the world, and maybe even learn how to do laundry without help. My son is more confident this year-he’s navigating his classes, campus life, and adulthood with a little more ease. It’s a beautiful thing to witness, even if it tugs at my heart.
This growing independence doesn’t mean I’m any less involved. It just means I’m learning how to support them from a different seat-more in the stands now than on the field.
While emotions are running high, so is the excitement. My daughter is already shopping for dorm supplies and dreaming of beachside study breaks, while my son is eager to reunite with friends and dive deeper into his major at USF.
Still, the looming quiet at home is a reality that’s setting in fast.
Everything is changing-the routines, the conversations-it’s all shifting. I’ll miss them deeply, but this is their time to soar.
As the suitcases pile up and the goodbyes draw near, one thing is clear: while my nest may be emptying, my heart is fuller than ever-with love, pride, and hope for what’s ahead.
Apple remains a compelling long-term investment, thanks to its robust ecosystem, accelerating AI strategy, and disciplined capital returns.
🏛️ Reliable Business Model & Ecosystem Moat
Apple now supports over 2.3 billion active devices, forming one of the most durable customer ecosystems in tech. This massive footprint reinforces high switching costs and recurring revenue streams via services like the App Store, Apple Pay, and suite of subscriptions (now over 38% of gross profit) (Forbes). Its strategy of integrating hardware, software, and services creates a differentiation moat that’s hard to replicate.
🚀 Catalysts Behind Future Growth
▪ Apple Intelligence: A Privacy-First AI Pivot
At WWDC 2025, Apple unveiled its “Apple Intelligence” initiative—20+ AI-powered features like real-time translation and email summarization designed for on-device performance and privacy. A major upgrade to Siri is expected in 2026. While it’s lagging peers in sheer AI spend, Apple is now investing aggressively and open to strategic M&A, having acquired at least seven AI startups in 2025..
▪ iPhone Refresh Cycles & Hardware Upside
Morgan Stanley projects a 12% rebound in iPhone shipments by fiscal 2026 as AI features boost upgrade demand. The favorable reception to new iPhone 16 models ahead of the holiday season supports this optimistic view (marketwatch.com).
🌍 Strategic Resilience Amid Geopolitical Risks
Apple’s architecture strategy includes over $500 billion in U.S. investment over four years—from expanding chip-making capacity to creating manufacturing academies and AI server production facilities to help offset tariff risks. At the same time, it has shifted much iPhone production for U.S. markets to India, diversifying supply chain risk away from China.
💰 Financial Strength & Shareholder Returns
Apple posted $94 billion in Q3 2025 revenue—a 10% year-over-year gain—and services revenue reached a record $27.4 billion. EPS came in above expectations, and despite $800 million+ in tariff impacts, Apple demonstrated operational resilience.
It continues to return capital aggressively, with $15.2 billion paid in dividends in 2025 and a long-term track record of dividend increases and share repurchases. Analysts expect this capital discipline to endure, offering downside protection and steady income (The Motley FoolForbes).
📉 Valuation: Discount with Upside Potential
Despite its strengths, Apple is currently down roughly 20% year-to-date, underperforming other major tech names amid tariff fears, AI lags, and macro uncertainty (Business Insider). Its forward P/E sits at around 33.6×, above the S&P 500 average (~23×), making valuation relative to its growth prospects a mixed story (Forbes). Still, analysts at BofA, Goldman Sachs, Wedbush, and others issue “Buy” ratings with 12–18 month targets of $235–300, implying double-digit upside from today’s ~$200 price levels.
🧭 Risks to Watch
While Apple’s fundamentals remain solid, investors should monitor:
Delays or execution risk in AI deployment or acquisitions
Regulatory scrutiny around antitrust, App Store rules, and global expansion
U.S.–China relations and implications for supply chain resilience
📈 Final Verdict: Long-Term Buy, Tactical Caution
Apple’s dominant ecosystem, balanced growth from hardware and high-margin services, disciplined capital returns, and accelerated AI pivot position it as a long-term winner. While near-term volatility and tariff uncertainty add caution, the current valuation discount provides an attractive entry point for investors with a multiyear horizon.
Disclosure:
I do not own any stock or have any financial interest in Apple Inc. (NYSE: AAPL). This article is for informational purposes only and should not be considered financial or investment advice. Investing in stocks carries risks, and past performance is not indicative of future results. Always conduct your own research and consult with a qualified financial professional before making any investment decisions.
When was the last time you looked at your homeowners insurance policy? Many homeowners set it and forget it often paying premiums for years without comparing rates or coverage. But in today’s changing insurance landscape, shopping your policy could make a big difference to your wallet and your peace of mind.
Why You Might Want to Shop Your Homeowners Insurance One of the biggest reasons to shop around is simple: savings. Insurance markets change constantly, and different companies assess risk in different ways. You may find the same coverage elsewhere for a lower premium, or better coverage for the same price. Additionally, shopping your policy gives you the chance to update your coverage. Maybe you’ve renovated, added a home office, installed a security system, or made energy-efficient upgrades—these can affect your premium or even qualify you for discounts. Finally, shopping around lets you evaluate customer service and claims satisfaction. Not all insurers handle claims equally, and a few bad experiences can turn a cheap policy into an expensive headache when you need it most.
Why You Might Not Want to Shop Your Homeowners Insurance Staying put with your current insurer can have benefits, too. Loyalty discounts can add up over time, and bundling your homeowners insurance with auto or other policies often unlocks extra savings that you might lose if you switch. If you have a history of claims or live in a high-risk area, your current company may be offering you more favorable terms than a new insurer would… especially if you’ve built trust over years without filing major claims. Finally, switching companies can be time-consuming and confusing. If your current agent or company provides excellent service, quick claims resolution, and clear communication, that peace of mind might be worth more than a small annual savings.
Bottom Line Shopping your homeowners insurance doesn’t mean you have to switch, but it does mean you’re informed. Compare rates every few years, check for discounts, and make sure your policy still fits your home and lifestyle. Whether you stay or go, you’ll know you’re making the best choice for your coverage and your wallet.
About the Author:
David Dandaneau is a client relations analyst that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.













 Health to Wealth Ventures
