Cerebras Systems (CBRS): Could This AI Chip Challenger Be One of the Next Big AI Growth Stories?

Cerebras Systems Inc. (NASDAQ: CBRS) has emerged as one of the more intriguing and volatile public companies attempting to reshape how artificial intelligence models are trained and, increasingly, how quickly they can perform inference.

Cerebras went public in May 2026 in one of the year’s most closely watched technology IPOs. Shares were priced at $185, and the completed offering raised approximately $6.38 billion in gross proceeds.

Four months later, the investment thesis is becoming clearer: Cerebras has extraordinary growth opportunities, but investors are paying a substantial valuation for that opportunity.

The artificial-intelligence infrastructure race is no longer simply about NVIDIA and GPUs.
Rows of illuminated server racks in a large data center with two workers
Rows of illuminated servers and overhead cabling power this expansive modern data center.

What Makes Cerebras Different?

Cerebras attacks the AI computing problem differently from traditional GPU manufacturers.

Its core technological innovation is the Wafer Scale Engine (WSE). Rather than cutting a semiconductor wafer into numerous individual chips and connecting those processors together, Cerebras essentially turns an enormous portion of the wafer itself into one processor.

The objective is straightforward: eliminate many of the communication bottlenecks associated with moving information between individual chips.

Cerebras has increasingly focused this technology on high-speed AI inference the process of actually running trained AI models and generating answers for users and applications.

That distinction is important.

As AI moves from experimentation toward widespread commercial deployment, inference could become an enormous recurring infrastructure market. Every AI search, coding agent, autonomous workflow, enterprise chatbot and reasoning system consumes inference compute.

Cerebras wants to supply a meaningful portion of that compute.

Revenue Growth Is Accelerating

The company’s financial trajectory illustrates why investors are paying attention.

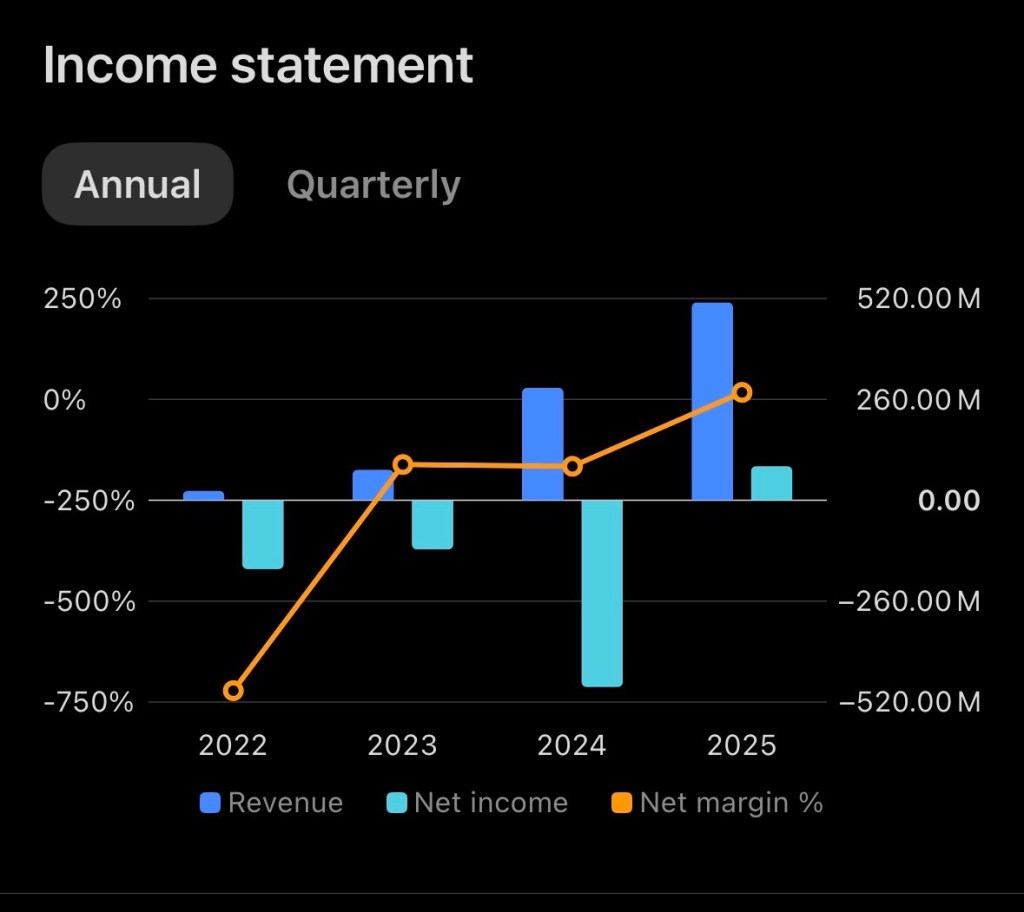
Cerebras generated approximately $290.3 million of revenue in 2024, increasing to roughly $510 million in 2025, representing 76% year-over-year growth.

Growth accelerated further during 2026.

First-quarter core revenue reached $191.3 million, up 92% year over year, including $111.6 million of hardware revenue and $79.8 million from cloud and other services.

Then came Q2.

Cerebras reported approximately $210 million of core revenue, while its core cloud business grew 287% year over year. The company also reported that it had secured approximately 600 megawatts of data-center capacity and planned to expand manufacturing capacity by more than tenfold during 2026.

Management subsequently increased its full-year outlook.

Cerebras now expects 2026 core revenue of approximately $880 million to $890 million, with core gross margins between 41% and 43% and core operating margins between negative 19% and negative 17%.

At the midpoint, $885 million would represent roughly 74% growth over 2025 revenue.

That is serious growth.

But it comes with an important caveat: Cerebras is still spending heavily to build the infrastructure necessary to capture that opportunity.
The $20+ Billion OpenAI Opportunity

Potentially the biggest component of the Cerebras growth story is its relationship with OpenAI.

Cerebras announced a multi-year agreement involving 750 MW of capacity valued at more than $20 billion. The company has also announced a multi-year partnership with Amazon to bring Cerebras inference technology to AWS.

These relationships potentially accomplish something extremely important for Cerebras: validation.

Competing against entrenched semiconductor and cloud-computing ecosystems requires more than superior benchmark performance. Customers need confidence that Cerebras can deploy its technology reliably and at enormous scale.

Large AI customers and cloud partners can help establish that credibility.

Cerebras has additionally disclosed customers or relationships involving companies such as Cognition, Lovable, Block, Figma, AlphaSense, GSK and CrowdStrike.

The company is therefore beginning to look less like an experimental AI-chip developer and more like an emerging AI infrastructure platform.

The CS-4 Could Be the Next Catalyst

Cerebras unveiled its next-generation CS-4 system in August, claiming performance of up to 30 times faster than GPU-based alternatives in certain workloads. The company is simultaneously expanding its global infrastructure footprint, including a recently announced 165 MW AI data center in Finland.

Those developments are worth watching closely.

AI infrastructure ultimately becomes an economics problem. Performance matters, but customers also care about cost per token, power consumption, latency, reliability and scalability.

If Cerebras can consistently demonstrate materially better inference economics—not merely impressive benchmark speeds—it could capture a meaningful piece of the rapidly expanding inference market.

The Financial Risk Investors Shouldn’t Ignore

The bull case is compelling, but CBRS isn’t a low-risk semiconductor investment.

First, profitability remains a work in progress.

Although Cerebras reported GAAP net income of $237.8 million during 2025, its filing shows a non-GAAP net loss of approximately $75.7 million, and the company explicitly warns investors that it has a history of generating losses.

Management’s 2026 guidance still calls for a substantially negative core operating margin.

Second, gross margins deserve close attention.

Q1 core gross margin was an impressive 47%, but Cerebras has been investing aggressively in cloud infrastructure and data-center capacity. The company currently expects full-year core gross margin of approximately 41%-43%.

Third, customer concentration has historically been significant. Large contracts can produce extraordinary revenue growth, but dependence on a relatively small number of enormous customers can also create significant volatility if deployments are delayed, renegotiated or canceled.

Finally, there is competition.

Cerebras isn’t operating in an empty market. NVIDIA dominates AI accelerators, while AMD, hyperscale cloud providers and custom silicon developers are all pursuing the same enormous AI-compute opportunity.

Cerebras doesn’t necessarily need to defeat NVIDIA to succeed.

It does, however, need to prove that wafer-scale computing occupies a sufficiently valuable niche within the broader AI infrastructure ecosystem.

Valuation: This Is Where Things Get Interesting

CBRS currently trades around $184, putting the company near its original $185 IPO price after experiencing substantial volatility since its May debut.
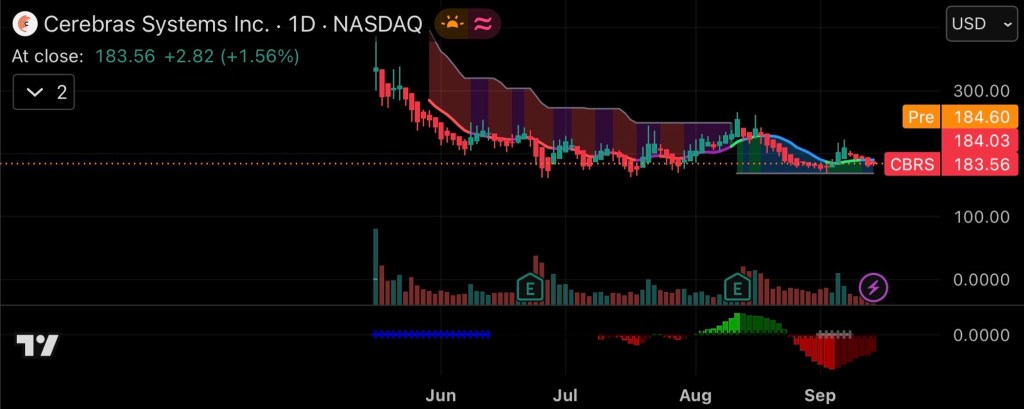
That matters psychologically, but the more important question is valuation.

With management forecasting approximately $885 million of 2026 core revenue, investors are already assigning Cerebras a substantial premium based on expectations of continued hypergrowth.

In other words, today’s CBRS valuation isn’t primarily based on what Cerebras earns today.

Investors are buying expectations for what the company could become several years from now.

That makes execution extremely important.

A company growing revenue 60%-80% annually can grow into a seemingly expensive valuation remarkably quickly. But if growth falls toward 20%-30% while profitability remains elusive, valuation compression can be equally dramatic.

My 12-Month CBRS Scenario Analysis

Forecasting a recently public, high-growth AI semiconductor company to a single price would create a false sense of precision. A scenario framework is more useful.

Bear Case: $120-$150

This scenario could develop if revenue growth decelerates, cloud margins deteriorate, major capacity deployments are delayed, customer concentration becomes problematic or investors broadly reduce the multiples they are willing to pay for AI infrastructure companies.

From approximately $184 today, that represents meaningful downside.

Base Case: $240-$300

This scenario assumes Cerebras continues producing strong revenue growth, approaches or exceeds its current guidance, demonstrates improving operating leverage and successfully converts its enormous infrastructure commitments into recurring cloud revenue.

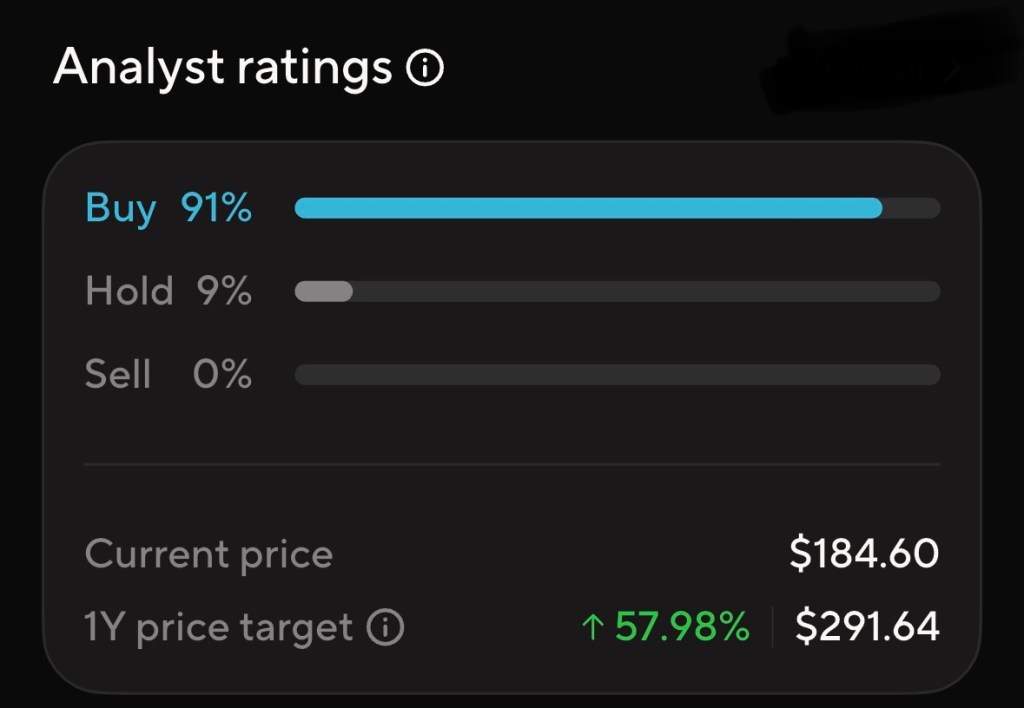
Interestingly, current Wall Street research sits in roughly this neighborhood. Needham reiterated a $300 price target following the company’s first-quarter results.

Aggregated analyst data recently showed an average target around $292, although analyst targets should always be viewed as estimates rather than predictions.

Bull Case: $350-$425

For Cerebras to reach this range, I would want to see several things happen simultaneously: revenue expectations moving materially above $1 billion, continued triple-digit or near-triple-digit cloud growth, successful OpenAI capacity deployments, evidence of attractive CS-4 economics, improving gross margins and a credible path toward operating profitability.

A sustained AI infrastructure spending cycle could provide an additional tailwind.

This is the highest-risk scenario because it requires both strong fundamental execution and investors continuing to award CBRS a premium valuation.
What I’m Watching Next

For investors holding CBRS, I believe five metrics deserve particular attention over the coming quarters:

  1. Cloud revenue growth: arguably the most important long-term metric because recurring inference revenue could eventually be more valuable than one-time hardware sales.
  2. Gross margin: rapid revenue growth means much less if infrastructure costs consume the economics.
  3. OpenAI deployment progress: successful conversion of the announced $20+ billion relationship into actual revenue could fundamentally alter Cerebras’ financial profile.
  4. Operating losses: Cerebras needs to demonstrate that revenue can eventually grow considerably faster than operating expenses.
  5. Customer diversification: additional enterprise and hyperscale customers would reduce dependence on a handful of massive relationships.

The Bigger Picture

Cerebras represents a particularly interesting kind of AI investment.

This isn’t simply another company adding artificial intelligence to an existing product.

Cerebras is building the physical infrastructure required to run AI itself.

The company increased revenue from just $24.6 million in 2022 to $510 million in 2025, and management now expects approximately $880-$890 million in core revenue during 2026.

Meanwhile, cloud revenue is growing at nearly 300%, manufacturing capacity is expanding dramatically, hundreds of megawatts of data-center capacity are under contract, and Cerebras is developing relationships with some of the most important companies in artificial intelligence.

That’s the opportunity.

The risk is that investors already recognize much of it.

At approximately $184 per share, CBRS remains a high-growth, high-expectation investment where quarterly execution can produce enormous price swings, as demonstrated when shares dropped sharply following the company’s August earnings release despite management raising its annual outlook.

My working 12-month framework therefore puts $240-$300 as a reasonable base-case range, with approximately $120-$150 representing a bearish execution/valuation scenario and $350-$425 representing a strong-execution bull scenario.

Those ranges aren’t price targets or guarantees. They are a framework for measuring future results against the expectations embedded in the stock.

For investors already holding Cerebras, the central question isn’t simply whether artificial intelligence will continue growing.

It almost certainly will.

The more important question is whether Cerebras can convert its technological advantage, enormous customer agreements and rapidly expanding infrastructure footprint into durable revenue growth and ultimately durable profits.

If it can, CBRS could become one of the more important publicly traded AI infrastructure companies to emerge from this generation of the technology boom.

Disclosure: I currently hold a position in Cerebras Systems (NASDAQ: CBRS). This article reflects personal research and analysis and is provided for informational purposes only. It is not financial advice or a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal.
CoreWeave (NASDAQ: CRWV): AI Infrastructure Powerhouse or High-Risk Growth Story?

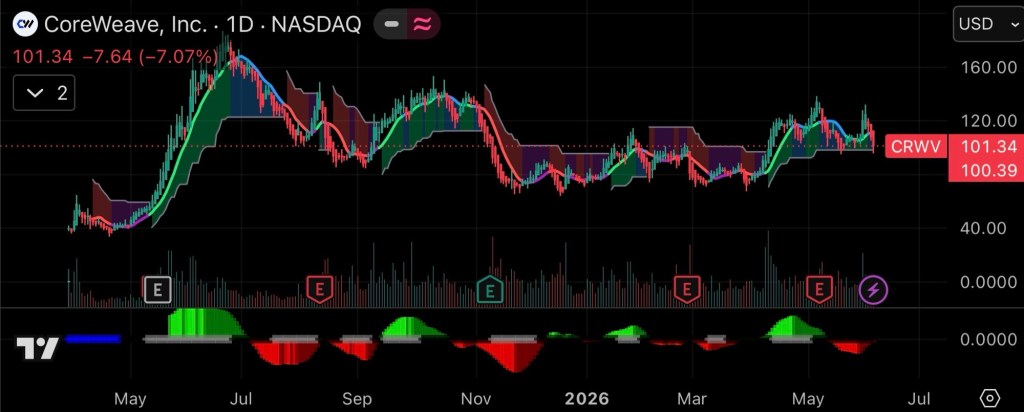
The artificial intelligence revolution has created a new generation of technology winners, and few companies have captured investor attention as quickly as CoreWeave (NASDAQ: CRWV). Since its public debut in 2025, CoreWeave has transformed from a niche cloud computing provider into one of the most closely watched AI infrastructure companies in the market.

As demand for artificial intelligence computing continues to accelerate, investors are asking a simple question: Does CoreWeave still have room to run?

Two technicians walking in a large data center with rows of illuminated AI server racks
Two technicians walk through a massive AI data center filled with illuminated server racks.

A Brief History of CoreWeave

CoreWeave was founded in 2017 and originally focused on cryptocurrency mining infrastructure. As demand for high-performance computing evolved, management pivoted toward providing specialized cloud infrastructure powered by NVIDIA graphics processing units (GPUs). That decision would prove transformational.

The company went public on the Nasdaq under the ticker CRWV in March 2025, pricing its initial public offering at $40 per share and raising approximately $1.5 billion to expand its AI cloud platform.

Since then, CoreWeave has become one of the leading providers of AI-focused cloud infrastructure, serving customers that require enormous amounts of computing power for training and operating large language models and other AI applications.

What’s Driving the Stock?

Several developments have fueled investor enthusiasm during 2026.

Most notably, CoreWeave became the first cloud provider to deploy NVIDIA’s new Vera Rubin NVL72 AI systems, reinforcing its position at the forefront of next-generation AI infrastructure. The announcement helped drive a significant rally in the stock and further strengthened the company’s strategic relationship with NVIDIA.

Earlier this year, NVIDIA expanded its partnership with CoreWeave and invested an additional $2 billion in the company. The two firms announced plans to accelerate the development of large-scale AI infrastructure and AI factories over the coming decade.

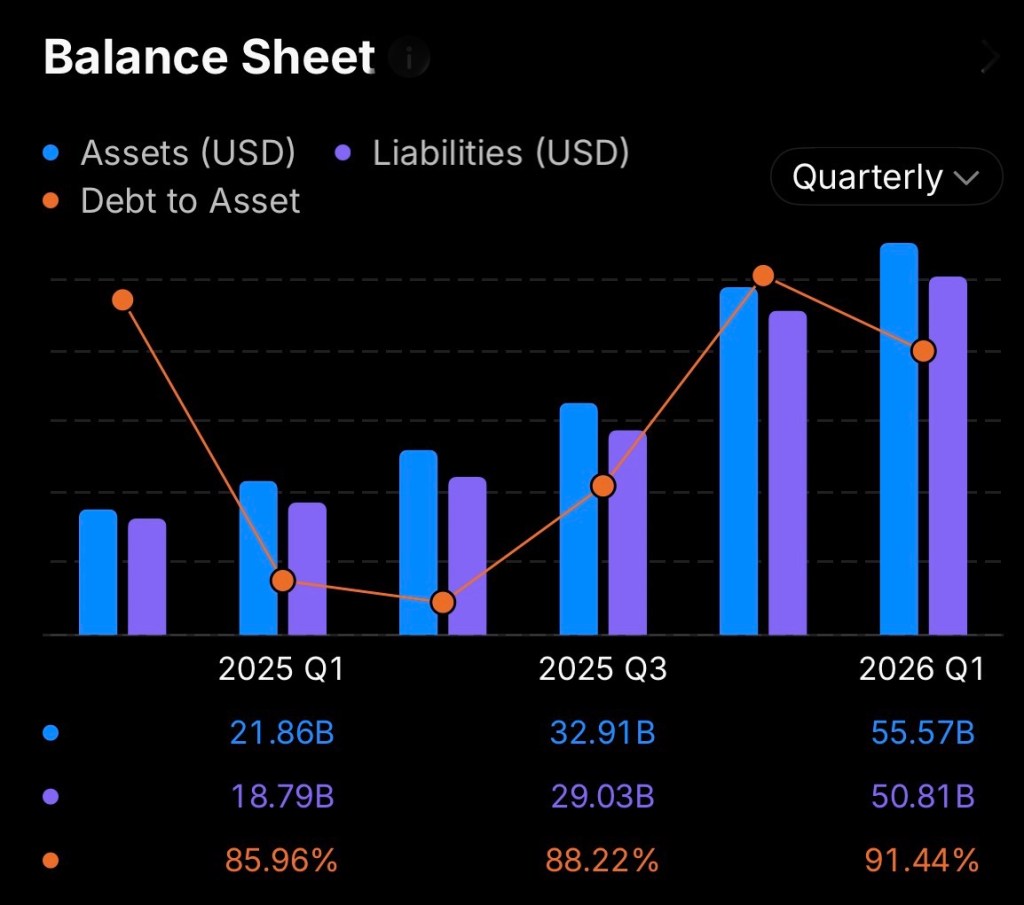
The company has also reported remarkable growth in customer demand. CoreWeave disclosed a revenue backlog of approximately $99.4 billion as of March 31, 2026, providing significant visibility into future revenue streams. Major customers include some of the largest names in artificial intelligence and cloud computing.

The Bull Case: Why Investors Remain Excited

Several factors support the bullish argument for CoreWeave.

Explosive AI Demand

Artificial intelligence remains one of the fastest-growing sectors in technology. Companies are racing to build increasingly sophisticated AI models, and all of them require massive amounts of computing power. CoreWeave’s infrastructure is specifically designed to meet that demand.

Strategic NVIDIA Relationship

Few companies have a closer relationship with NVIDIA than CoreWeave. Access to next-generation hardware before competitors could provide a significant advantage as AI workloads continue to grow.

Massive Revenue Backlog

A backlog approaching $100 billion gives investors confidence that demand remains strong despite concerns about the broader economy. Few newly public companies can point to this level of contracted business.

Industry Leadership

CoreWeave has established itself as one of the premier “AI-native” cloud providers. As enterprises increasingly adopt AI, the company may be positioned to capture a growing share of infrastructure spending.

The Bear Case: Risks Investors Should Consider

Despite its impressive growth, CoreWeave is not without risks.

Capital Intensive Business Model

Building AI infrastructure is extraordinarily expensive. CoreWeave continues to spend billions on data centers, GPUs, and power capacity. Management recently increased its capital expenditure outlook as demand for AI hardware continues to surge.

Profitability Remains a Challenge

Although revenue growth has been exceptional, the company continues to report significant net losses. Investors are betting that future scale will eventually generate substantial profits. If growth slows before profitability improves, valuation concerns could emerge.

Customer Concentration

A meaningful portion of CoreWeave’s business comes from large AI companies and hyperscale cloud providers. Any reduction in spending from major customers could affect future growth rates.

Valuation Risk

Many AI-related companies trade at premium valuations based on expectations of future growth. If the AI spending cycle cools or investors become more cautious, high-growth stocks like CoreWeave could experience significant volatility.

Is There Still Upside Ahead?

The answer largely depends on whether investors believe AI infrastructure demand will continue expanding over the next decade.

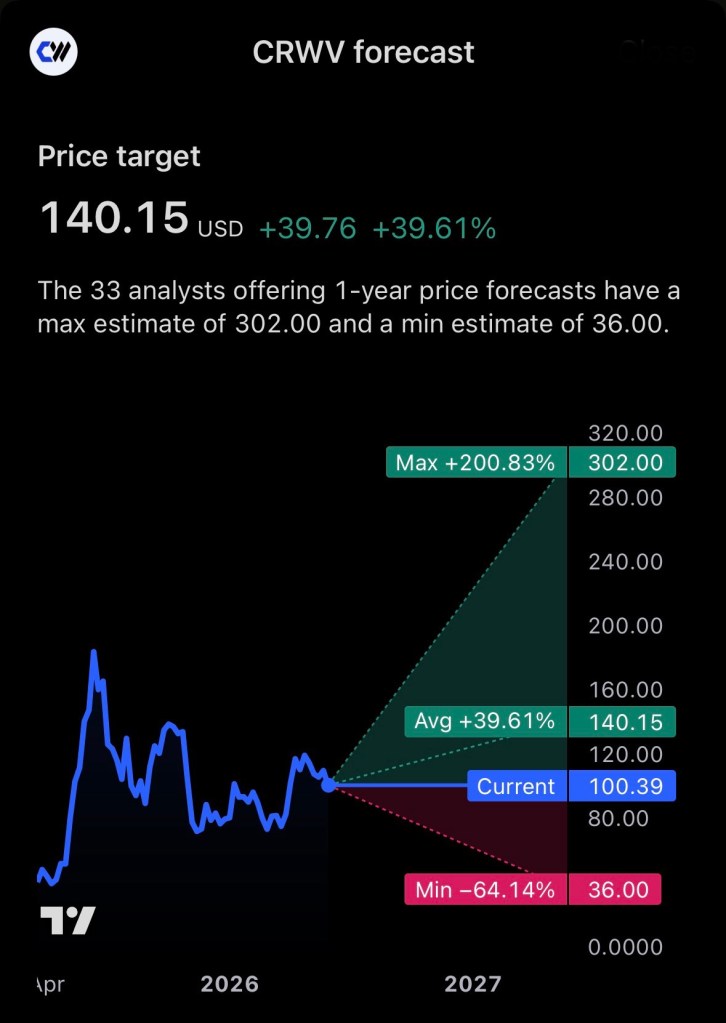
Supporters argue that artificial intelligence is still in its early innings and that the demand for compute power will continue to grow exponentially. If that thesis proves correct, CoreWeave could remain one of the primary beneficiaries of the AI buildout. Recent analyst targets and market commentary suggest many on Wall Street still see meaningful upside potential from current levels.

However, investors should recognize that CoreWeave remains a high-growth, high-risk company. The business must continue executing flawlessly while managing enormous capital expenditures and eventually demonstrating sustained profitability.

Bottom Line

CoreWeave has rapidly emerged as one of the most important infrastructure providers powering the AI revolution. The company’s strategic relationship with NVIDIA, enormous revenue backlog, and leadership position in AI cloud computing have helped fuel investor enthusiasm.

While the stock may continue to benefit from the expanding AI ecosystem, investors should remember that rapid growth often comes with substantial volatility. CoreWeave represents both the promise and the risks of investing in one of the market’s most exciting sectors.

For investors willing to tolerate uncertainty, CRWV remains one of the purest publicly traded plays on the future of artificial intelligence infrastructure.

Disclosure

The author owns shares of CoreWeave (NASDAQ: CRWV). This article is for informational and educational purposes only and should not be considered investment advice. Investors should conduct their own research and consult a qualified financial advisor before making investment decisions.

References

  1. CoreWeave. (2025, March 27). CoreWeave announces pricing of initial public offering. Retrieved from CoreWeave Investor Relations
  2. CoreWeave. (2026, May 7). CoreWeave reports strong first quarter 2026 results. Retrieved from CoreWeave Investor Relations
  3. CoreWeave. (2026). Investor relations overview. Retrieved from CoreWeave Investor Relations Overview
  4. NVIDIA. (2026, January 26). NVIDIA and CoreWeave strengthen collaboration to accelerate buildout of AI factories. Retrieved from NVIDIA Newsroom
  5. Reuters. (2026, May 7). CoreWeave signals higher capex as component costs rise, shares fall.
  6. Reuters. (2026, May 13). Nvidia CEO’s foundation buys $108 million of AI computing from CoreWeave, donates it to researchers.
  7. Barron’s. (2026, June 2). CoreWeave is first to offer NVIDIA’s newest AI system. The stock rises.
  8. Yahoo Finance. (2026). CoreWeave, Inc. (CRWV) stock price, news, quote & history. Retrieved from Yahoo Finance CRWV Page
  9. Stock Analysis. (2026). CoreWeave (CRWV) stock price & overview. Retrieved from Stock Analysis CRWV Overview
  10. MarketWatch. (2026, May 7). CoreWeave shares plunge. Revenue doubles but AI costs are rising.

Ondas Holdings ($ONDS): A High-Risk, High-Reward Play on Autonomous Defense and AI Infrastructure

Ondas Holdings has rapidly emerged as one of the more closely watched small-cap companies in the autonomous systems and defense technology sector. The company operates through its Ondas Autonomous Systems division, focusing on AI-powered drone platforms, counter-drone defense technologies, and private wireless infrastructure designed for critical industries and government agencies.

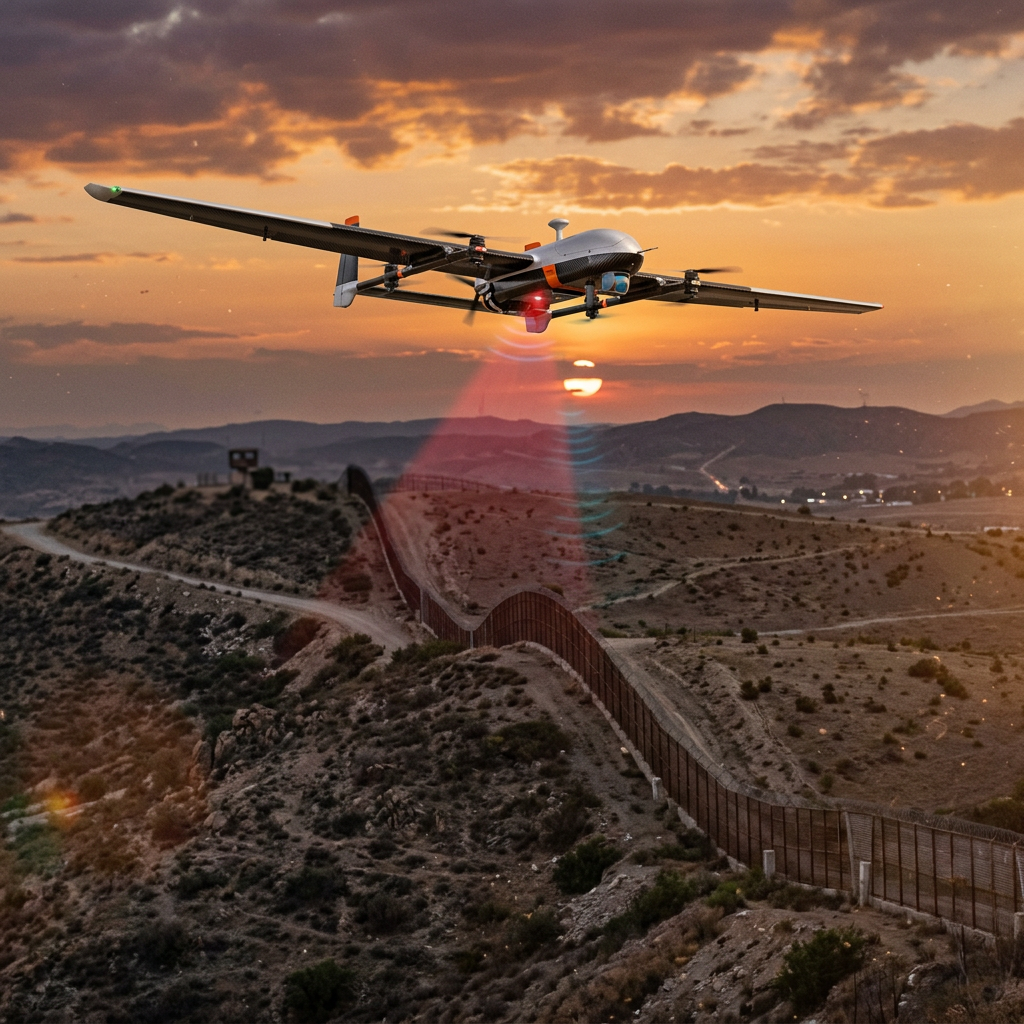
Drone flying over a border fence scanning the area with sensors at sunset
A drone scans a border fence at sunset using advanced sensors.

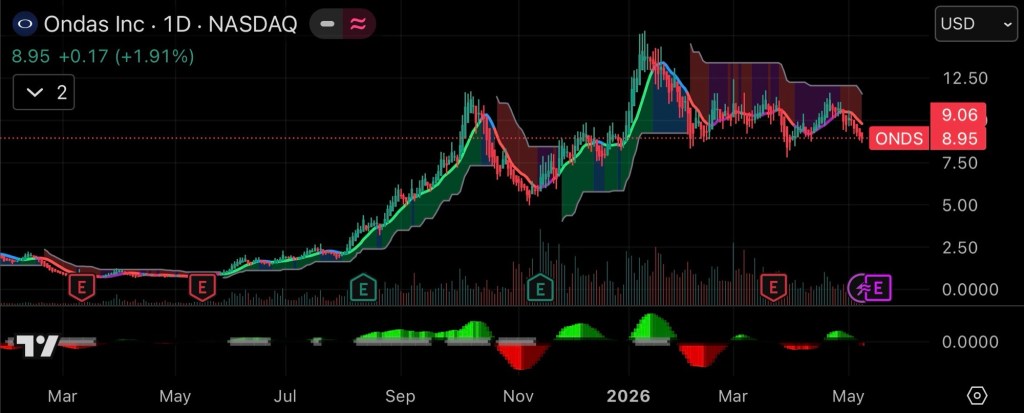
Over the past year, investor interest in ONDS has accelerated as geopolitical tensions, rising defense spending, and demand for autonomous security systems have expanded globally. The company’s partnerships, acquisitions, and expanding backlog have positioned it as a speculative growth stock with significant upside potential but also elevated volatility and execution risk.

According to recent company updates, Ondas reported preliminary 2025 revenue between $49.7 million and $50.7 million, substantially ahead of prior guidance. Management also increased its 2026 revenue outlook to as much as $375 million, supported by growing defense contracts and autonomous drone deployments.

The Core Investment Thesis

Ondas is attempting to build an integrated autonomous intelligence ecosystem combining:

  • Autonomous drones
  • Counter-UAS defense systems
  • AI-driven operational software
  • Remote wireless communications infrastructure
  • Border and critical infrastructure monitoring systems

Its flagship technologies include:

  • Optimus drone systems
  • Iron Drone Raider counter-UAS platforms
  • Scout autonomous systems
  • AI-enabled command-and-control architecture

The company has increasingly focused on military, homeland security, and infrastructure applications where demand has accelerated globally.

One of the most notable developments for investors was Ondas’ partnership with Palantir Technologies to integrate Palantir’s AI and data fusion capabilities into Ondas autonomous systems. Analysts believe this partnership could improve scalability and strengthen Ondas’ positioning in next-generation defense operations.

Short-Term Growth Outlook

In the short term, ONDS remains heavily momentum-driven. Several catalysts could impact the stock over the next 6–12 months:

1. Expanding Defense Contracts

Ondas recently announced:

  • Multi-million-dollar European airport security contracts
  • New Middle East counter-drone orders
  • A $20 million autonomous border security program

These announcements suggest accelerating commercial adoption of autonomous security systems.

2. Revenue Acceleration

Management forecasts dramatic year-over-year growth in 2026 revenue, supported by an expanding backlog and defense demand. Revenue growth has become one of the primary bullish arguments for the stock.

3. Retail and Institutional Interest

ONDS has gained traction among retail traders and defense-focused growth investors. Increased trading volume and short interest could continue to create sharp price swings.

4. Upcoming Earnings

Investors are closely watching the company’s next earnings release scheduled for May 14, 2026, which may provide additional guidance and contract updates.

Long-Term Opportunities

The longer-term opportunity for Ondas centers on becoming a major provider of autonomous infrastructure systems.

Potential long-term drivers include:

  • Global expansion of autonomous defense systems
  • AI-enabled battlefield coordination
  • Smart city and critical infrastructure monitoring
  • Border protection technologies
  • Autonomous aviation and robotics
  • NATO and allied defense modernization

The company also benefits from broader trends in:

  • Defense digitization
  • Drone warfare evolution
  • AI-enhanced surveillance
  • Critical infrastructure protection

If management successfully scales operations and improves profitability, Ondas could evolve from a speculative small-cap into a more established defense technology company over the next 3–5 years.

However, risks remain substantial.

Key Risks Investors Should Monitor

Despite its growth story, ONDS carries elevated risk factors:

  • Continued net losses
  • Potential shareholder dilution
  • Dependence on government contracts
  • Execution risk on scaling production
  • Competitive pressure from larger defense firms
  • High stock volatility
  • Heavy reliance on future growth projections

The company is still in an aggressive expansion phase and has not yet established consistent profitability.

Competitive Landscape

CompanyPrimary FocusMarket PositionRelative Financial Strength
Ondas HoldingsAutonomous drones, counter-UAS, AI systemsEmerging small-cap disruptorSpeculative / growth-stage
AeroVironmentMilitary drones and loitering munitionsEstablished defense contractorStrong
Palantir TechnologiesAI defense software and analyticsAI infrastructure leaderVery strong
Kratos Defense & Security SolutionsAutonomous defense systemsMid-cap defense innovatorModerate to strong
DroneShieldCounter-drone defense technologySpecialized counter-UAS playerModerate

ONDS Stock Performance Snapshot

MetricData
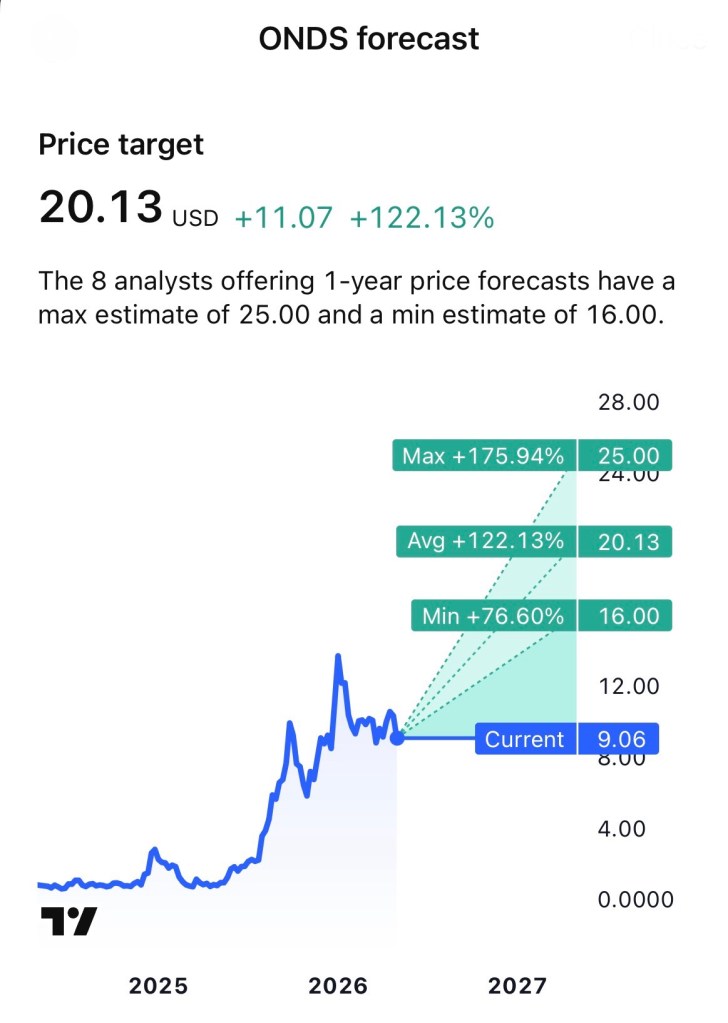
Current Share PriceApproximately $9
52-Week PerformanceSignificant volatility with major upside swings
Market CapApproximately $2.35 billion
SectorAerospace & Defense Technology
ProfitabilityCurrently unprofitable
Revenue TrendRapid growth trajectory
Analyst SentimentBullish but speculative

Market data current as of May 2026.

Financial Strength Overview

CategoryAssessment
Revenue GrowthStrong
Cash PositionImproving
Debt ManagementModerate risk
ProfitabilityWeak currently
Backlog GrowthStrong
Institutional InterestIncreasing
Share Dilution RiskElevated

Final Analysis

Ondas Holdings represents one of the more aggressive speculative opportunities in the autonomous defense and AI-enabled drone market. The company is benefiting from powerful macro trends including rising defense budgets, geopolitical instability, and increased demand for autonomous systems.

For aggressive growth investors, ONDS may offer substantial upside if management successfully executes on revenue expansion and large-scale deployment opportunities. However, the stock remains highly volatile and should likely be viewed as a speculative position within a diversified portfolio rather than a conservative core holding.

Investors considering ONDS should closely monitor:

  • Earnings growth
  • Contract execution
  • Cash burn
  • Share dilution
  • Defense spending trends
  • AI partnership developments

Disclosure

The author currently owns a position in Ondas Holdings $ONDS. This article reflects personal opinions and is intended for informational purposes only. It should not be considered financial advice or a recommendation to buy or sell securities. Investors should conduct their own due diligence and consult a licensed financial advisor before making investment decisions.

References

Why NVIDIA Stock is a Smart Long-Term Investment

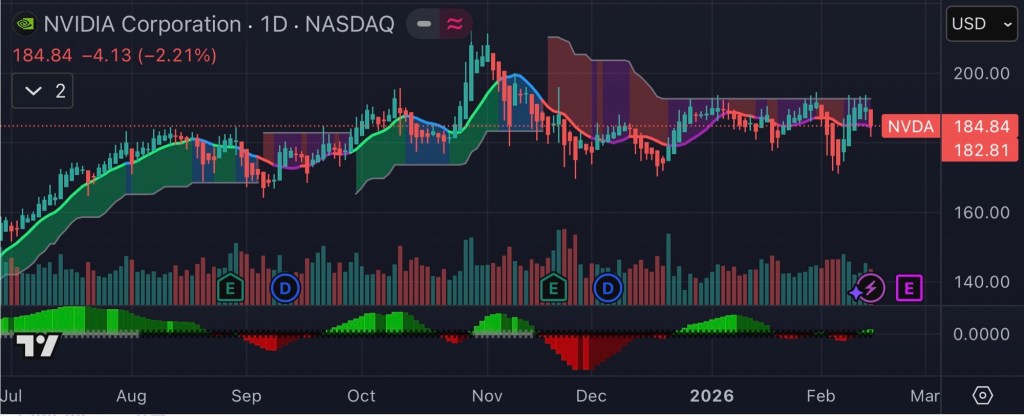
Despite recent volatility and short-term investor hesitation, NVIDIA (NASDAQ: NVDA) remains one of the strongest long-term investment opportunities in the global equity market. While the stock has experienced periods of consolidation and suppressed price action relative to its explosive growth, its financial performance, industry dominance, and forward cash flow trajectory suggest that current levels could represent a compelling entry point for long-term investors.


NVIDIA’s Financial Strength Remains Unmatched

NVIDIA’s growth over the past two years has been historic. The company reported $130.5 billion in fiscal 2025 revenue, up 114% year-over-year, along with net income of $72.9 billion, demonstrating extraordinary profitability.

This growth has accelerated further into fiscal 2026:

  • Q3 FY2026 revenue reached $57.0 billion, up 62% year-over-year.
  • Quarterly net income surged to $31.9 billion, representing exceptional margin strength.
  • NVIDIA expects continued momentum, projecting approximately $54 billion in quarterly revenue, indicating sustained demand.

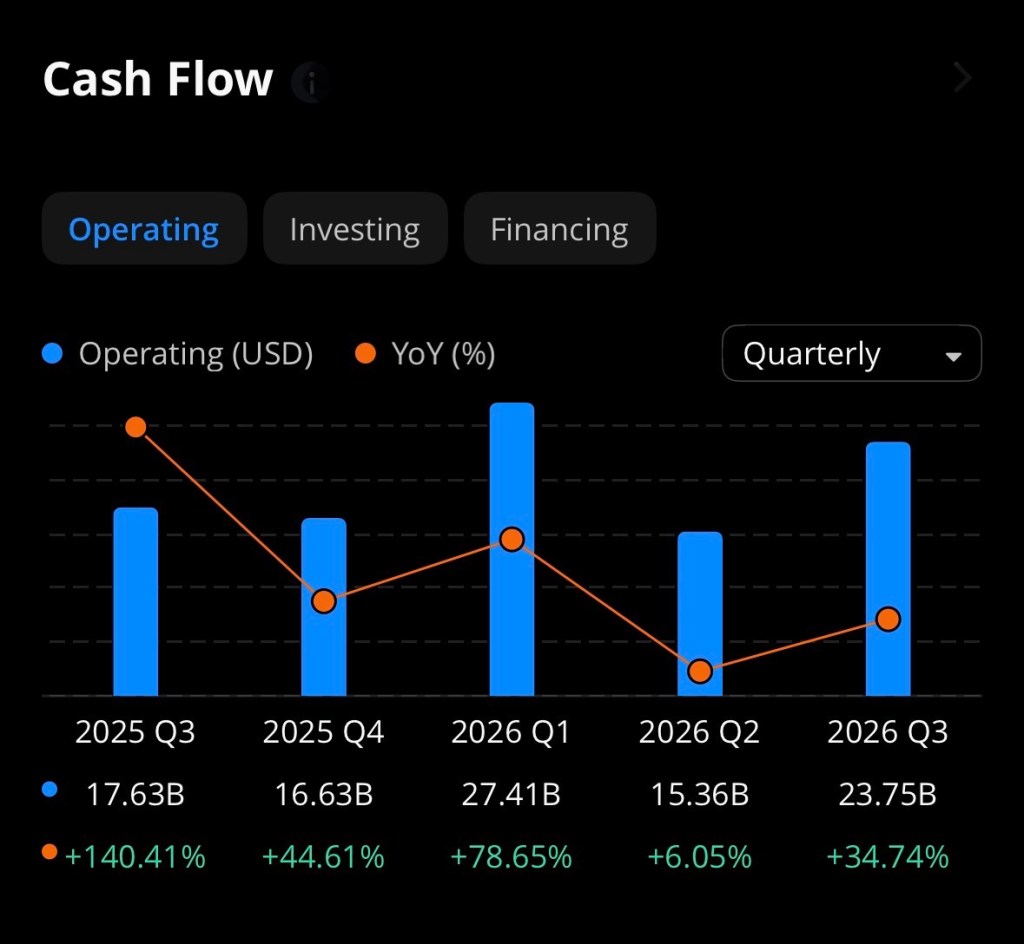
This performance translates directly into massive operating cash flow potential. With operating margins above 60% in recent quarters and explosive AI-related demand, NVIDIA is converting an unusually high percentage of revenue into free cash flow.


AI Demand Is Still in Its Early Stages

The most critical investment thesis for NVIDIA is its central role in powering artificial intelligence infrastructure globally.

Major technology companies are expected to spend over $650 billion on AI infrastructure in 2026, benefiting NVIDIA directly as the primary supplier of advanced GPUs.

Additionally:

  • NVIDIA’s data center segment generated over $51 billion in quarterly revenue, driven primarily by AI demand.
  • Analysts project NVIDIA’s data center revenue alone could reach $300 billion annually by fiscal 2027, reflecting extraordinary long-term growth potential.

This positions NVIDIA not simply as a semiconductor company, but as the foundational infrastructure provider for the global AI economy.


Why the Stock Appears “Suppressed” Despite Strong Fundamentals

NVIDIA’s stock consolidation is primarily driven by macro and investor psychology not deteriorating fundamentals.

Key factors include:

1. Massive Prior Gains Created Consolidation Period

After rising over 1,000% in recent years, periods of sideways movement are normal as valuation multiples normalize.

2. Investor Concerns About AI Spending Sustainability

Some investors worry large capital expenditures from tech giants could reduce near-term cash flow.

However, these investments are directly fueling NVIDIA’s revenue growth.

3. Emerging Competition

Companies like AMD, Broadcom, and custom chips from hyperscalers are increasing competition, but NVIDIA maintains a dominant performance and software ecosystem advantage.


Estimated Cash Flow Comparison: NVIDIA vs Competitors (2026 Projection)

Based on revenue guidance, historical free cash flow margins, and analyst projections, NVIDIA is expected to dramatically outperform competitors in absolute cash flow generation.

CompanyEstimated 2026 RevenueEstimated FCF MarginEstimated 2026 Free Cash FlowAI Market Position
NVIDIA$240B–$280B45%–55%$110B–$150BDominant leader
AMD$45B–$60B20%–25%$9B–$15BStrong competitor
Broadcom$65B–$75B35%–40%$23B–$30BGrowing AI custom chips
Intel$55B–$65B10%–20%$6B–$12BRecovery phase
Qualcomm$42B–$48B25%–30%$11B–$14BMobile AI niche

Methodology:
Estimates derived from:

  • Company financial statements
  • Forward guidance
  • Historical free cash flow conversion ratios
  • AI growth projections

Competitive Advantage: NVIDIA’s True Moat Is Software, Not Just Chips

NVIDIA’s competitive edge extends beyond hardware into software ecosystems such as CUDA, which creates lock-in effects across millions of developers.

Additionally:

  • NVIDIA’s GPUs remain superior for training large AI models.
  • The company continues rapid innovation with new Blackwell and next-generation AI architectures.

This creates extremely high switching costs for customers.


Valuation Opportunity: Cash Flow Suggests Undervaluation

If NVIDIA generates $130 billion in annual free cash flow within the next 2–3 years, even a conservative valuation multiple of 30x FCF would imply:

Potential future valuation:

$130B × 30 = $3.9 trillion market cap

Compared to today’s lower valuation levels, this represents substantial upside potential.


Long-Term Investment Thesis: Why NVIDIA Remains a Buy

Key bullish factors:

1. AI Demand Is Still in Early Stages
Global AI adoption is accelerating, not slowing.

2. Massive Free Cash Flow Generation
Few companies in history have generated cash flow at NVIDIA’s scale.

3. Dominant Market Position
NVIDIA remains the undisputed leader in AI computing infrastructure.

4. Strong Shareholder Returns
The company has already returned $37 billion to shareholders through buybacks and dividends in FY2026 alone.

5. Long-Term Secular Tailwind
AI is expected to reshape every industry over the next decade.


Risks Investors Should Monitor

No investment is risk-free. Key risks include:

  • Increased competition from AMD, Broadcom, and hyperscalers
  • Government export restrictions
  • Potential slowdown in hyperscaler spending
  • Valuation volatility due to macroeconomic conditions

However, none of these risks currently undermine NVIDIA’s dominant position.


Conclusion: Suppressed Prices May Represent a Rare Opportunity

NVIDIA remains one of the most financially powerful and strategically positioned companies in the world. Despite short-term stock volatility, its explosive revenue growth, dominant AI position, and unprecedented free cash flow generation suggest that current price consolidation may represent one of the most attractive long-term entry opportunities available.

For investors with a multi-year horizon, NVIDIA remains a cornerstone asset in the AI-driven future economy.


Disclosure:
The author does not currently own, directly or indirectly, any shares, options, or other financial interests in NVIDIA Corporation (NASDAQ: NVDA) at the time of publication. This article is provided for informational and educational purposes only and does not constitute financial, investment, or trading advice. Investors should conduct their own research and consult with a licensed financial professional before making any investment decisions.

References

Barron’s. (2026, February). Nvidia stock rises. Broadcom is closing the AI chips gap. Retrieved from https://www.barrons.com

Barron’s. (2026, February). Nvidia stock pops. It should benefit from OpenAI spending. Retrieved from https://www.barrons.com

MarketWatch. (2026, February). Microsoft’s stock is cheaper than IBM’s for the first time in a decade. Retrieved from https://www.marketwatch.com

NVIDIA Corporation. (2025). NVIDIA announces financial results for fourth quarter and fiscal 2025. Retrieved from https://nvidianews.nvidia.com

NVIDIA Corporation. (2025). NVIDIA announces financial results for second quarter fiscal 2026. Retrieved from https://nvidianews.nvidia.com

NVIDIA Corporation. (2025). NVIDIA announces financial results for third quarter fiscal 2026. Retrieved from https://nvidianews.nvidia.com

NVIDIA Corporation. (2025). NVIDIA announces financial results for first quarter fiscal 2026. Retrieved from https://nvidianews.nvidia.com

Tom’s Hardware. (2025, December). Nvidia’s revenue skyrockets to record $57 billion per quarter. Retrieved from https://www.tomshardware.com


ServiceNow Navigates Market Volatility With Strong Fundamentals and AI Momentum

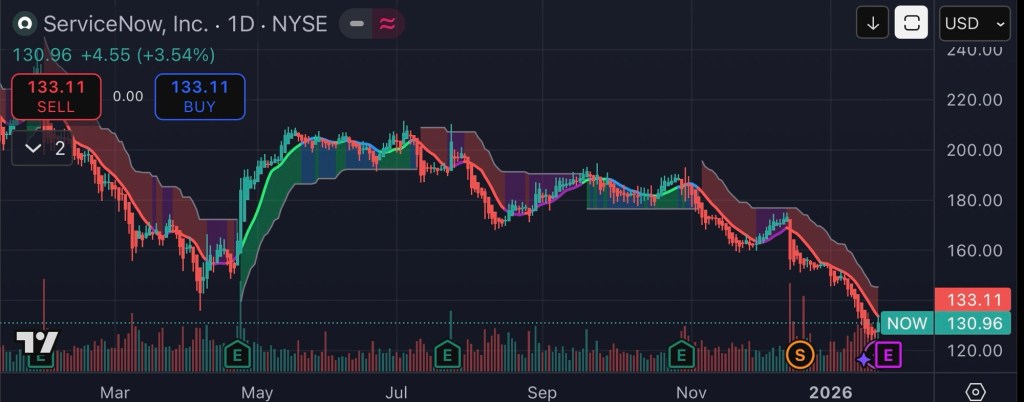
ServiceNow, Inc. (NYSE: NOW), the enterprise workflow automation and AI-driven software company, is attracting renewed investor attention as it enters its next earnings period with mixed signals from the market. After a prolonged sell-off in 2025 and early 2026, shares have shown signs of stabilization ahead of quarterly results due this week, while analysts revise forecasts on both the upside and downside.

Market Context:
As of the most recent close, ServiceNow’s stock price finished at $133.11, up 3.5% on positive sentiment ahead of earnings week. (TechStock²) The company’s shares have experienced significant pressure over the past year, falling roughly 30–50 percent from prior highs, signaling broader investor caution within the enterprise software sector. (TradingView+1)


Recent Financial Performance

ServiceNow’s underlying financial performance remains robust despite stock price challenges:

MetricMost Recent Reported
Q3 2025 Revenue$3.407 billion (+22% YoY) (GuruFocus)
Subscription Revenue$3.299 billion (+21.5% YoY) (GuruFocus)
Q3 2025 EPS$2.40 (beats expectations) (GuruFocus)
Q2 2025 Subscription Revenue$3.113 billion (+22.5% YoY) (ServiceNow Investor Relations)
Performance Obligations (RPO)$23.9 billion (+29% YoY) (ServiceNow Investor Relations)

ServiceNow also continues to expand its customer base, with strong demand in large enterprises and sustained growth in contract value obligations. (ServiceNow Investor Relations)

Financial Chart (Selected Historical & Forecast Data):

Metric / Timeframe2024 Actual2025 ActualAnalyst 2026 Avg Target
Revenue Growth~21% YoY~22% YoY— (Estimated Stable Growth)
Stock Price (Year-End)~$239.62 (52-wk high) (MarketWatch)~$128–134 range (MarketWatch)Consensus ~ $209.07 Avg (MarketBeat)
Analyst Price Target Range$170–$263 (TipRanks)Consensus Moderate Buy$209.07 Average 12-mo (MarketBeat)

Catalysts and Risks

Positive Drivers:

  • AI Integration and Partnerships: The company’s strategic deployment of AI capabilities particularly through deepening enterprise AI products and partnerships positions it within one of the fastest-growing segments of enterprise software. (The Wall Street Journal)
  • Earnings Beats: Recent quarters have seen revenue and EPS exceed consensus estimates, reinforcing the company’s pricing power and durability even in more cautious macro environments. (Nasdaq)
  • Stock Split Authorization: A board-approved 5-for-1 stock split aims to improve liquidity and broaden retail investor ownership. (Yahoo Finance)

Challenges:

  • Valuation Compression: Analysts have trimmed price targets in light of broader software sector rotation, leading to downward revisions that reflect caution ahead of earnings and uncertain macro conditions. (Ad Hoc News)
  • Market Sentiment: Software stocks broadly have underperformed amid shifting investor preferences toward semiconductors and AI infrastructure names, contributing to valuation pressure for ServiceNow. (Investopedia)

Analyst Forward Outlook & Stock Price Forecast (Next 12 Months)

Market forecasts reflect a moderate buy consensus for NOW with meaningful upside potential despite short-term volatility:

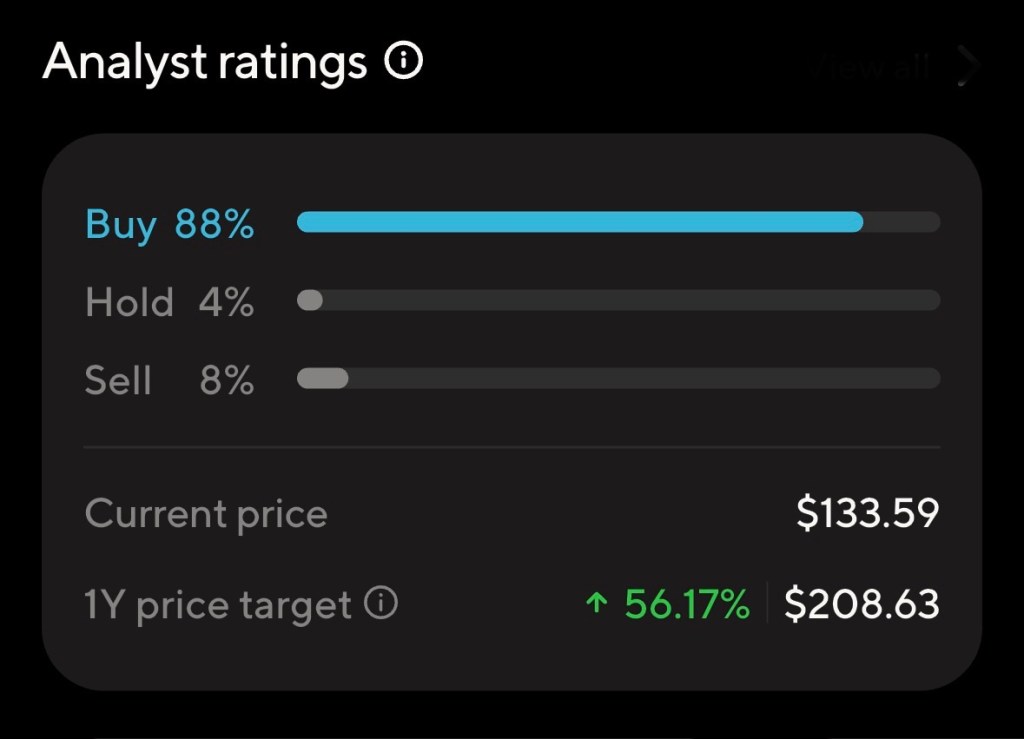
  • MarketBeat Consensus: Average 12-month price target of $209.07 — implying approximately 57% potential upside from current levels. (MarketBeat)
  • TipRanks Data: Average analyst target range of $170 to $263, with a “Strong Buy” consensus overall. (TipRanks)
  • Bullish Scenarios: Some analysts project further expansion toward historical peer valuations if growth and AI monetization accelerate. (TIKR.com)

Projected Price Range in One Year: $180–$250, contingent upon execution of AI initiatives, macro stability, and continued enterprise software demand.


Disclosure

I currently hold a position in ServiceNow (NYSE: NOW). This article is for informational purposes only and does not constitute financial advice. Investors should conduct independent research before making investment decisions.


References

Investing.com. (2025, October 30). Wells Fargo raises ServiceNow stock price target to $1,275 on higher estimates. Retrieved from Investing.com. Investing.com
MarketBeat. (2026). ServiceNow (NOW) Stock Forecast & Price Target. Retrieved from MarketBeat. MarketBeat
MarketWatch. (2026, January). ServiceNow Inc. stock data. Retrieved from MarketWatch. MarketWatch
TradingView/ Invezz. (2026). Here’s why the ServiceNow stock price is tanking. Retrieved from TradingView. TradingView
TechSite (TS2.Tech). (2026, January 24). ServiceNow stock price jumps 3.5% into earnings week. Retrieved from TS2.Tech. TechStock²
Tikr (2026). After a 31% fall in the last 12 months, can ServiceNow recover in 2026? Retrieved from Tikr. TIKR.com
WSJ. (2026). OpenAI and ServiceNow Strike Deal to Put AI Agents in Business Software. Retrieved from The Wall Street Journal. The Wall Street Journal
ServiceNow Investor Relations. (2025). ServiceNow Reports Second Quarter 2025 Financial Results. Retrieved from ServiceNow IR. ServiceNow Investor Relations
GuruFocus News. (2025, October 30). ServiceNow Inc (NOW) Q3 2025 Earnings: EPS of $2.40 Beats Estimates. Retrieved from GuruFocus. GuruFocus

Five9, Inc. (NASDAQ: FIVN): Evaluating a Cloud Communications Leader Heading Into 2026

Five9, Inc. is a leading provider of cloud-based contact center software, operating within the rapidly expanding Contact Center as a Service (CCaaS) market. As enterprises continue to modernize customer engagement through artificial intelligence and cloud infrastructure, Five9’s platform positions the company at the intersection of digital transformation and customer experience optimization (Five9, Inc., 2025).


Company Overview

Founded in 2001, Five9 delivers cloud-native contact center solutions that integrate voice, digital channels, workforce optimization, and AI-powered automation. The company’s offerings are designed to help enterprises improve customer satisfaction while reducing operational complexity and costs. Five9 primarily serves mid-market and large enterprise customers, with a business model heavily weighted toward recurring subscription revenue (Trefis, 2025).

The CCaaS market continues to benefit from long-term secular tailwinds, including remote work adoption, omnichannel customer engagement, and enterprise investment in AI-driven customer support solutions (Seeking Alpha, 2025).


Financial Performance and Health Snapshot

Revenue and Growth

Five9 reported record full-year revenue exceeding $1 billion, reflecting consistent double-digit growth driven by enterprise adoption and expanding AI-enabled services (Five9, Inc., 2024). Recent quarterly results show revenue growth in the low double-digit range, signaling moderation from prior hypergrowth years but still outperforming many legacy contact center competitors (Investing.com, 2025a).

Profitability and Margins

Operational efficiency has improved as the company scales. Adjusted EBITDA margins have expanded into the low-to-mid 20% range, supported by higher software margins and disciplined cost management (Seeking Alpha, 2025). While GAAP profitability remains pressured by stock-based compensation, non-GAAP earnings and free cash flow generation have shown steady improvement (NASDAQ, 2025).

Balance Sheet Strength

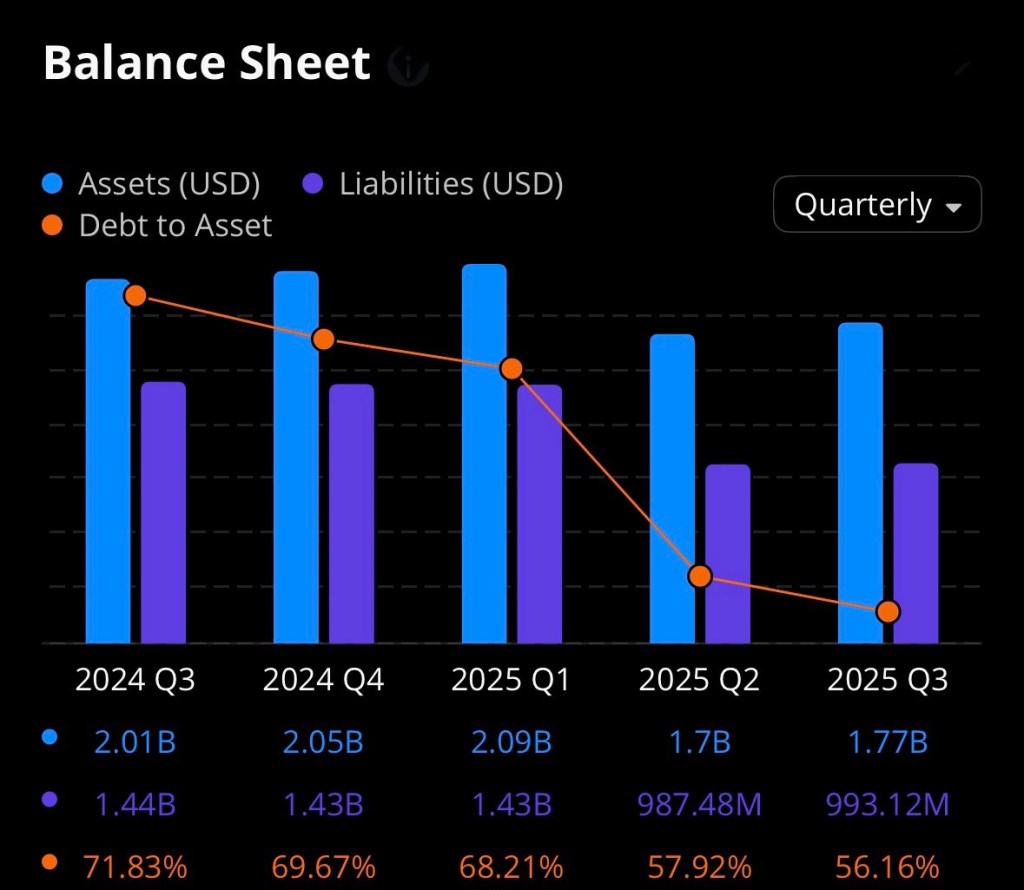
Five9 maintains a solid liquidity position, supported by cash reserves and manageable debt levels. The company has also authorized share repurchase activity, signaling management confidence in long-term value creation despite near-term stock volatility (Investing.com, 2025b).


Stock Price and Market Performance

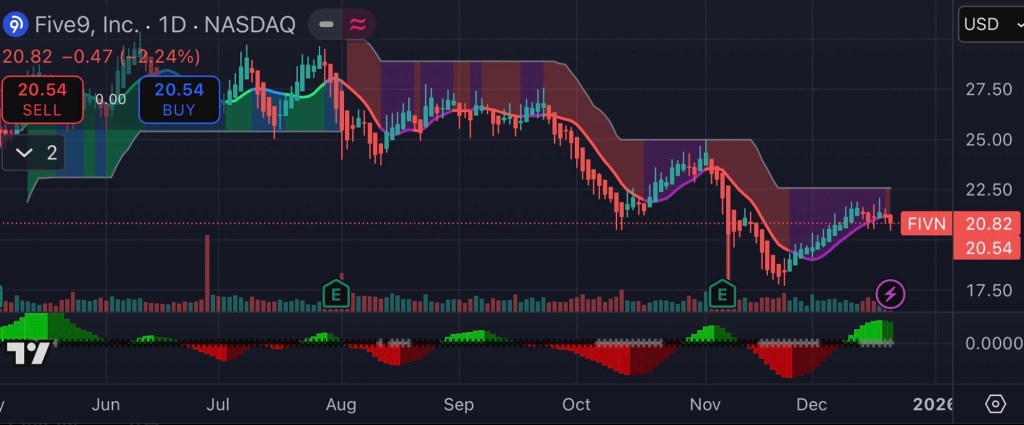
As of late 2025, Five9 shares have experienced significant price compression, trading well below prior cycle highs. The stock recently touched a 52-week low, reflecting broader SaaS sector multiple contraction, investor caution around growth deceleration, and macroeconomic uncertainty (Investing.com, 2025c).

Despite the decline, valuation metrics such as price-to-sales and enterprise-value-to-revenue ratios now sit below historical averages for high-quality SaaS peers, suggesting the market may be discounting future growth more aggressively than current fundamentals justify (NASDAQ, 2025).


Why Five9 May Be an Attractive Investment Heading Into 2026

1. AI-Driven Product Expansion

Five9 continues to embed artificial intelligence across its platform, including intelligent virtual agents, real-time analytics, and automation tools. AI-related revenue has grown faster than the company’s core business, positioning Five9 to benefit from rising enterprise demand for scalable, automated customer engagement (Seeking Alpha, 2025).

2. Recurring Revenue Visibility

A substantial majority of Five9’s revenue is derived from subscriptions, providing predictable cash flows and improved earnings visibility. This recurring model is a key attribute investors seek in mature SaaS companies navigating economic cycles (Trefis, 2025).

3. Margin Expansion Potential

As growth stabilizes and operating leverage improves, Five9 has the potential to further expand margins, particularly if AI-driven products command premium pricing and reduce customer churn (NASDAQ, 2025).

4. Strategic Optionality

Ongoing consolidation within the cloud communications and enterprise software space creates potential upside through partnerships, acquisitions, or strategic interest from larger technology firms seeking to expand their customer experience portfolios (Investing.com, 2025b).


Risks and Considerations

While the long-term outlook remains constructive, investors should remain mindful of several risks. These include intensified competition from well-capitalized rivals, potential delays in enterprise spending, and the possibility that revenue growth continues to decelerate more rapidly than expected (Investing.com, 2025a). Additionally, broader market sentiment toward technology stocks could continue to influence valuation multiples independent of company performance.


Conclusion

Five9 enters 2026 as a financially stable, AI-focused SaaS company operating in a structurally growing market. Although near-term growth has moderated and share price volatility remains elevated, improving margins, recurring revenue strength, and expanding AI capabilities provide a foundation for potential long-term value creation. For investors willing to tolerate short-term uncertainty, Five9 represents a company where fundamentals and market valuation may diverge heading into the next phase of the cloud communications cycle (Five9, Inc., 2025; Seeking Alpha, 2025).

Disclosure:
I do not hold, directly or indirectly, any equity position in Five9, Inc. (NASDAQ: FIVN) at the time of writing. This article is provided for informational and educational purposes only and should not be construed as investment advice, a recommendation to buy or sell securities, or a solicitation of any investment strategy. Readers should conduct their own due diligence and consult a qualified financial professional before making any investment decisions.


References (APA Format)

Five9, Inc. (2024). Five9 reports record full-year revenue exceeding $1 billion. Five9 Investor Relations.
https://investors.five9.com

Five9, Inc. (2025). Quarterly earnings and financial results. Five9 Investor Relations.
https://investors.five9.com/financials

Investing.com. (2025). Five9 stock hits 52-week low amid market volatility.
https://www.investing.com

Investing.com. (2025). Cantor Fitzgerald lowers Five9 price target citing growth moderation.
https://www.investing.com

NASDAQ. (2025). Five9, Inc. (FIVN) stock quote, financials, and performance data.
https://www.nasdaq.com

Seeking Alpha. (2025). Five9: AI-driven contact center growth and margin expansion.
https://www.seekingalpha.com

Trefis. (2025). Five9 business model, revenue mix, and valuation analysis.
https://www.trefis.com

Zeta Global: A High-Growth Martech Investment Opportunity

Quick take: Zeta Global, the AI-driven marketing cloud, has delivered a string of better-than-expected quarters, is guiding to another year of strong revenue growth, and just made a big acquisition to expand its loyalty and enterprise footprint. That combination accelerating revenue, improving profitability guidance, and strategic M&A is why some investors are re-rating the stock. Below: the facts, the catalyst, a compact risk view, and a chart/table that show the growth story.


Headlines and the data points you need

  • Zeta reported Q2 2025 revenue of $308.4 million, a ~35% year-over-year increase vs. the prior year quarter. (Nasdaq)
  • For full-year 2024 Zeta generated about $1.01 billion in revenue. (Zeta Global)
  • Management has repeatedly “beat and raise” most recently increasing full-year 2025 revenue guidance to $1,258–$1,268 million (midpoint ~$1.263B) and raising Adjusted-EBITDA and free-cash-flow ranges as well. Those revisions reflect faster growth and improving margins. (Zeta Global+1)
  • Zeta announced a large acquisition (Marigold’s enterprise business — including Cheetah Digital, Selligent, Sailthru and other assets) to strengthen loyalty and enterprise offerings, a move management says accelerates international reach and cross-sell opportunities. (Zeta Global+1)
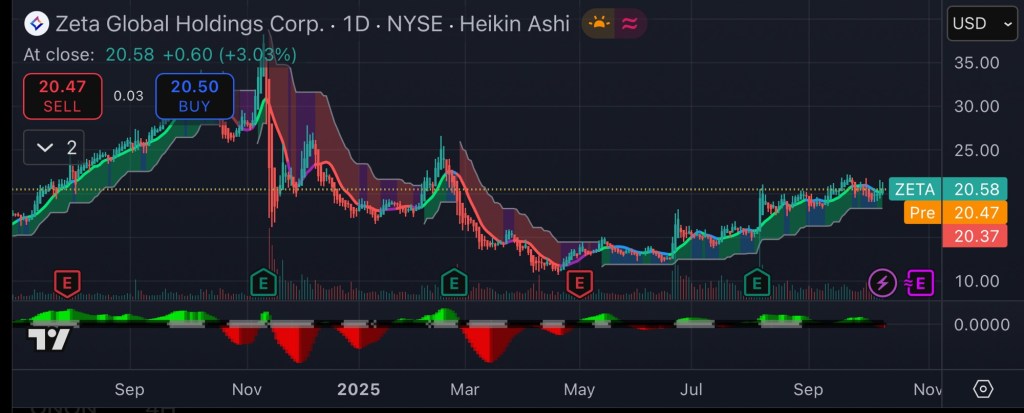
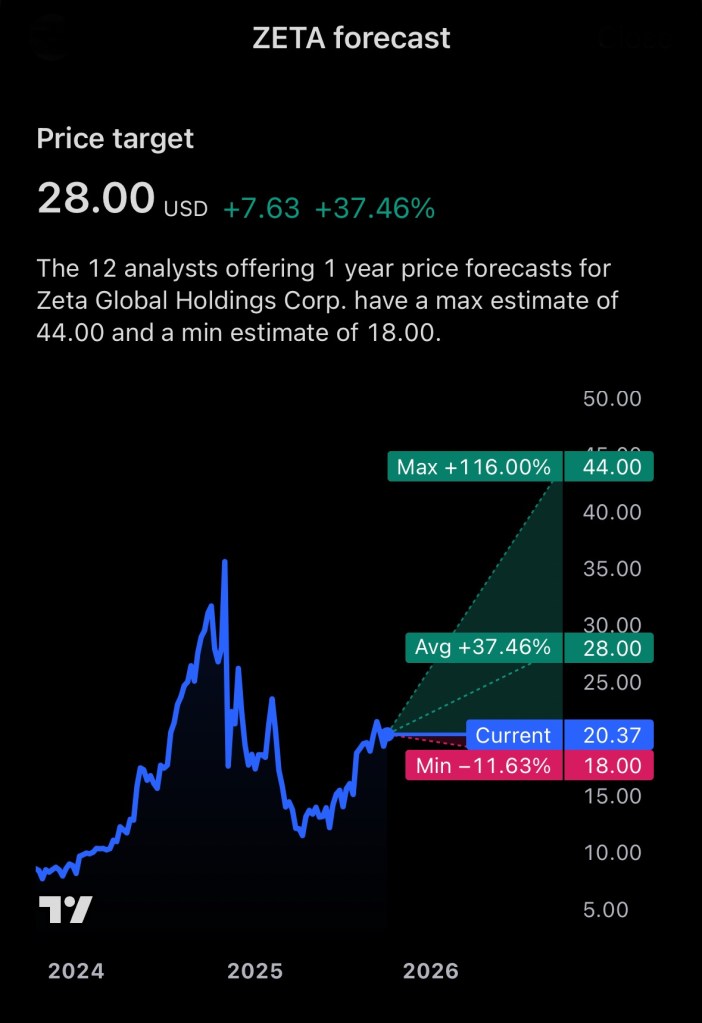
  • Market snapshot (at time of writing): share price ≈ $20.37 and market cap in the mid-$4 billion range investors are paying for fast growth but also a path to profitability. (Yahoo Finance)

Why this could be an attractive investment (the bull case)

  1. High single- to double-digit top-line growth that’s accelerating. Zeta’s recent quarters show consistent revenue acceleration (Q2 ’25 +35% YoY), a key signal for growth investors in the martech/adtech space. Management’s upward guidance for FY-2025 reinforces that it’s not just one quarter of outperformance. (Nasdaq+1)
  2. Improving operating leverage and cash generation. The company has raised Adjusted-EBITDA and free-cash-flow guidance, pointing to margin expansion. That’s important: investors reward companies that can turn revenue growth into sustainable profits and cash. (Zeta Global)
  3. Strategic M&A that fills capability gaps and expands addressable market. The Marigold enterprise business deal adds loyalty platforms and prominent enterprise customers (and EMEA coverage), enabling more cross-sell inside an existing customer base and a larger recurring revenue pool. If integration goes smoothly, this can boost both revenue and churn resilience. (Zeta Global+1)
  4. Compelling unit economics at scale. Zeta reports improving ARPU (average revenue per scaled customer) and strong net revenue retention metrics, which suggest existing customers are spending more, a powerful multiplier for SaaS-like businesses. (Company disclosures highlight rising Scaled and Super-Scaled customer ARPU.) (Zeta Global+1)
  5. Positive technical / market interest. Stock research outlets have recently upgraded technical scores (e.g., IBD RS rating rise), indicating renewed investor interest that can amplify returns if fundamentals keep improving.( Investors.com)

Compact table: key metrics (source notes below)

MetricValue (most recent / guidance)Source
Q2 2025 revenue$308.4M (+35% YoY)Company results / press release. (Nasdaq)
FY 2024 revenue$1,006M (≈$1.01B)FY 2024 report. (Zeta Global)
FY 2025 revenue guidance$1,258–$1,268M (midpoint ≈ $1.263B)Company guidance (beat & raise). (Zeta Global)
Adjusted-EBITDA guidance (FY-25)~$263.6–$265.6MCompany guidance. (Zeta Global)
Share price (snapshot)~$20.37Market quote (timestamped).
Market cap (approx.)Mid ~$4B–$4.8BMarket data providers. (Yahoo Finance+1)

Visual: revenue comparison (Q2 vs prior year, FY 2024 vs FY 2025 guidance)

I created a compact chart and table comparing:

  • Q2 2024 (estimate) vs Q2 2025 actual, and
  • FY 2024 actual vs FY 2025 guidance midpoint.

(Chart and table were prepared from the company reporting and guidance figures cited above).

Sources for the plotted numbers: Q2 2025 revenue and YoY change, FY 2024 totals, and FY 2025 guidance. (Nasdaq+2Zeta Global+2)


Risks — what could go wrong

  • Execution risk on M&A and integration. The Marigold enterprise assets are substantial; integration issues, customer churn, or higher-than-expected costs could blunt the benefits. (Zeta Global)
  • Valuation vs. growth tradeoff. The stock price reflects future growth expectations. If revenue growth slows or margin expansion stalls, multiples can compress quickly. (Yahoo Finance)
  • Adtech / martech competition and cyclicality. The market is competitive (large incumbents and many specialists). Ad/spend cyclicality could affect revenue. Company performance depends on continued client spend and retention. (Zeta Global)
  • Profitability not yet fully GAAP positive. Zeta has narrowed losses but still reports GAAP net losses; investors should watch sustained EBITDA and free-cash-flow conversion. (Zeta Global)

Bottom line (concise)

Zeta Global presents a classic high-growth martech investment case: accelerating revenue, improving profitability guidance, and strategic M&A that extends its product footprint and international reach. That combination can create durable revenue expansion and margin improvement — the ingredients growth investors pay for. But the stock still carries execution and integration risk and depends on preserving high retention and ARPU. If you like fast growth with a clear path to margin expansion and accept the M&A/integration risk, Zeta is a name to research further; if you are risk-averse or need immediate GAAP profitability, it may not fit.

Disclosure:

I do not own any stock or have any financial interest in Zeta Global Holdings (NYSE: $ZETA). This article is for informational purposes only and should not be considered financial or investment advice. Investing in stocks carries risks, and past performance is not indicative of future results. Always conduct your own research and consult with a qualified financial professional before making any investment decisions.

References

Zeta Global Holdings Corp. (2025, August 8). Zeta reports second quarter 2025 financial results; raises full-year 2025 guidance. Zeta Global Investor Relations. Retrieved from https://investors.zetaglobal.com/

Zeta Global Holdings Corp. (2024, February 28). Zeta reports fourth quarter and full-year 2024 results. Zeta Global Investor Relations. Retrieved from https://investors.zetaglobal.com/

Investor’s Business Daily. (2025, September). Zeta Global stock analysis and relative strength update. Investor’s Business Daily. Retrieved from https://www.investors.com/

Reuters. (2025, September). Zeta Global Holdings Corp. company profile and financial summary (ZETA.O). Reuters Markets. Retrieved from https://www.reuters.com/

MarketWatch. (2025, October). Zeta Global Holdings Corp. stock quote & financials (ZETA). MarketWatch. Retrieved from https://www.marketwatch.com/

Business Wire. (2025, July 31). Zeta Global announces acquisition of Marigold’s enterprise business to expand loyalty and EMEA presence. Business Wire. Retrieved from https://www.businesswire.com/

Yahoo Finance. (2025, October 9). Zeta Global Holdings Corp. (ZETA) stock price and market cap data. Yahoo Finance. Retrieved from https://finance.yahoo.com/

Beamr Imaging (BMR): A Speculative Bet with Potential Upside

Herzliya, Israel / U.S. Markets — Beamr Imaging Ltd. (NASDAQ: BMR) is a tiny, high-volatility tech play in the video compression / optimization space. In recent months, it has attracted attention from speculative investors betting on its ability to break into high-growth verticals like autonomous vehicles (AV). Below is a breakdown of its recent developments, risks, and upside potential.


What Does Beamr Do?

Beamr provides software and hardware-accelerated video encoding, transcoding, and optimization solutions. Its product lineup includes:

  • Beamr 4 / 5 (H.264, HEVC) content-adaptive encoders
  • Beamr Cloud (SaaS offering)
  • Beamr IP blocks (for integration into ASICs / GPUs / application processors)
  • JPEGmini photo optimization technology

Its customer base spans streaming platforms, media companies, content distributors, and now increasingly, autonomous vehicle and machine-vision use cases. (Yahoo Finance+2investors.beamr.com+2)

In 2025, the company has doubled down on pushing into the AV market by unveiling a GPU-accelerated video compression solution designed to handle petabyte-scale video data generated by autonomous vehicle fleets. (Investing.com+2Stock Titan+2)

A key value proposition: its compression technology reportedly delivers 20%–50% savings in storage and data transfer costs for customers, without degrading model accuracy in machine vision applications. (Stock Titan+1)


Recent Financials & Metrics

Below is a simplified financial snapshot based on the public disclosures (primarily for 1H 2025). Because Beamr is small and reporting is limited, the data should be taken as directional rather than precise.

Metric1H 2025YoY Change / Notes
Revenue~$1.07 million+7% vs 1H 2024 (Stock Titan+3Investing.com+3Quiver Quantitative+3)
Gross Margin~86%Down from ~91.5% (due to amortization of internal software) (Investing.com+2Quiver Quantitative+2)
R&D Expense~$2.04 million+104% YoY (hiring, subcontractors, cloud costs) (Investing.com+2Quiver Quantitative+2)
Sales & Marketing Expense~$1.06 million+242% YoY (expanding marketing, conferences) (Investing.com+2Stock Titan+2)
Net Loss~$3.18 millionvs $1.96 million loss in 1H 2024 (Investing.com+2Quiver Quantitative+2)
Cash & Equivalents~$13.9 millionRepresents a substantial cushion for a microcap (Investing.com+2Stock Titan+2)

From alternative data sources, Reuters lists Beamr’s total assets at USD 22.095M (latest) and notes negative cash flows from operations, consistent with a growth / development stage firm. (Reuters)

Caveats & caveats:

  • The company is unprofitable and burning cash.
  • Operating expenses are rising aggressively.
  • Revenue scale is still extremely modest.
  • Reporting is limited, making forecasting uncertain.
  • The stock is highly volatile and likely illiquid in many trading periods.

Recent Developments & Catalyst Events

  • AV Market Push: In mid-2025, Beamr formally launched its GPU-accelerated video compression solution for autonomous vehicles, executing multiple proof-of-concept (PoC) deals and aiming to position itself as a bridge between AV fleets (which generate enormous video data) and cost-efficient storage/processing infrastructure. (Yahoo Finance+4Investing.com+4Stock Titan+4)
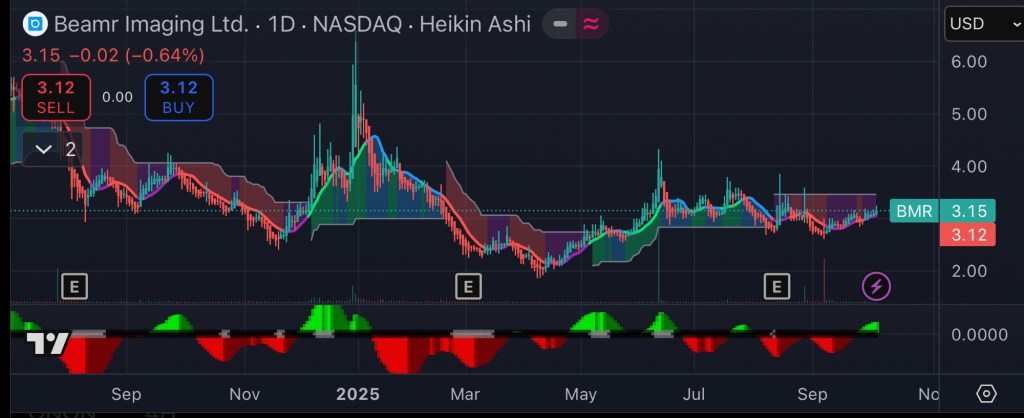
  • Strong Price Movement on Announcement: When Beamr announced the AV compression launch at the NVIDIA GTC Paris event, the stock spiked ~17% intraday. (RTT News)
  • Oracle Cloud Marketplace Listing & Recognition: Beamr’s product became available in Oracle’s Marketplace (earning “Powered by Oracle Cloud Expertise” status), driving a stock move of ~48% on that news. (The Wall Street Journal)
  • Partnership & Ecosystem Moves: The company joined AWS’s ISV Accelerate program, participated in major industry events (NVIDIA GTC, NAB Show), and secured awards (e.g. NAB Show Product of the Year) for its video technology. (Quiver Quantitative+3Stock Titan+3investors.beamr.com+3)
  • Strong Liquidity Ratio: Reports suggest Beamr had a current ratio (current assets / current liabilities) of ~17.77 in H1 2025, indicating a solid short-term liquidity buffer. (Investing.com)

Why Some Speculators Believe Upside Is Possible

Here’s the bullish thesis (with caveats) for why investors might view Beamr as a high-risk, high-reward play:

  1. Large addressable markets
    • The explosion of video data (streaming, 5G, ML/AI, edge computing) presents tailwinds for efficient compression/optimization.
    • The AV industry is a nascent but rapidly expanding consumer of video/vision data; any solution that materially reduces cost could attract high-value contracts.
  2. Technical differentiation (if proven)
    • If Beamr’s compression can deliver promised 20–50% reductions in storage + network cost without compromising model accuracy or visual quality, that’s a compelling ROI proposition for customers.
    • Their GPU-accelerated and content-adaptive approach may be more scalable and future-forward than legacy compression tools.
  3. Low valuation / optionality
    • As a microcap trading near its cash value, much of the upside is tied to growth and execution (i.e., if they convert PoCs to commercial contracts).
    • If one or two large AV or cloud customers adopt their technology, the “optional upside” is significant.
  4. Momentum & narrative-driven upside
    • In small, speculative tech stocks, favorable press, partnerships, and media hype can drive rapid re-rating.
    • Their association with big names (NVIDIA, AWS, Oracle) lends credibility and can accelerate business traction.
  5. Liquidity cushion
    • Having nearly $14M in cash for a company of this size gives it runway to invest in growth, product development, and marketing (assuming no major execution failure).

Risks That Temper the Speculation

To balance the bullish perspective, here are key risks:

  • Execution risk: Converting PoCs into recurring, large-scale revenue is harder than it looks.
  • Competitive risk: Many large players (cloud providers, codec developers, chipmakers) might replicate or undercut.
  • Burn & dilution risk: Continued losses may force equity raises, which could dilute existing holders.
  • Thin trading / volatility: Stock may swing wildly on news (or lack thereof).
  • Dependence on marquee wins: A few large contracts must validate the model.
  • Technology risk: Compression for human vision is a different problem than “machine vision / AV grade” compression; errors or compromises in accuracy could kill the value proposition.

Outlook & Scenarios

  • Base Case (moderate success): Beamr secures a handful of mid-sized AV or cloud contracts over the next 1–2 years; revenue grows meaningfully, losses narrow, and the stock re-rates modestly (e.g. 2×–3× current valuation).
  • Bull Case (breakthrough): A marquee deal or partnership (e.g. with a top AV OEM or cloud provider) turns into a large recurring revenue stream. The market begins to value Beamr as a strategic infrastructure play, leading to 5×+ upside.
  • Bear Case: Execution falters, PoCs don’t convert, cash burns down, and the company faces liquidity or solvency challenges, dragging the stock back toward cash value (or below).

Disclosure: I currently hold a position in Beamr Imaging Ltd. (NASDAQ: BMR). This article reflects my personal opinions and analysis, and is not intended as financial advice. Please conduct your own research or consult a financial advisor before making any investment decisions.

References

Investing.com. (2025, August 22). Beamr reports 7% revenue growth in first half 2025; launches AV solution. Investing.com. https://www.investing.com/news/company-news/beamr-reports-7-revenue-growth-in-first-half-2025-launches-av-solution-93CH-4187902

Reuters. (2025). Beamr Imaging Ltd (BMR.OQ) company profile & facts. Reuters. https://www.reuters.com/markets/companies/BMR.N/

RTTNews. (2025, March 19). Beamr Imaging stock soars 17% on launch of video compression tech for autonomous vehicles. RTTNews. https://www.rttnews.com/3545934/beamr-imaging-stock-soars-17-on-launch-of-video-compression-tech-for-autonomous-vehicles.aspx

StockTitan. (2025, July 1). Beamr in Q2 2025: Demonstrating the validation of its solution for autonomous vehicles. StockTitan. https://www.stocktitan.net/news/BMR/beamr-in-q2-2025-demonstrating-the-validation-of-its-solution-for-kfcmamrn7nhw.html

The Wall Street Journal. (2025, May 12). Beamr Imaging shares surge 48% on Oracle recognition. The Wall Street Journal. https://www.wsj.com/articles/beamr-imaging-shares-surge-48-on-oracle-recognition-85584b6a

Yahoo Finance. (2025). Beamr Imaging Ltd. (BMR) stock price & news. Yahoo Finance. https://finance.yahoo.com/quote/BMR/

The Impact of 5G on Everyday Life: Faster, Smarter, and More Connected

The rollout of 5G networks is transforming the way we live, work, and connect—ushering in a new era of speed, responsiveness, and innovation. As more cities, towns, and rural areas gain access to fifth-generation wireless technology, the effects are becoming increasingly visible in our daily routines.

Speed and Efficiency at Your Fingertips
At its core, 5G promises data speeds up to 100 times faster than 4G. For the average user, this means smoother video streaming, faster downloads, and nearly instant web page loading. But the real transformation goes far beyond entertainment. With ultra-low latency, 5G enables real-time communication between devices, opening the door to new possibilities in healthcare, transportation, and education.

Remote workers and students benefit from stronger, more stable video conferencing with fewer glitches and lags. Cloud-based tools respond almost instantly, making collaboration more efficient. Businesses, from small startups to large corporations, can operate with a level of agility and responsiveness previously unattainable.

A Smarter World
The true power of 5G lies in its ability to support billions of connected devices simultaneously. This is fueling the growth of the Internet of Things (IoT)—from smart thermostats and connected cars to wearable health monitors and automated factories.

For instance, smart homes equipped with 5G-enabled devices can respond more quickly and accurately to user commands, improving energy efficiency and security. In cities, 5G supports smart infrastructure like traffic control systems that adapt to real-time conditions, reducing congestion and improving safety.

Healthcare Revolution
Telemedicine, already on the rise, has taken a major leap forward with 5G. Doctors can now conduct remote examinations with HD video clarity and access large medical imaging files without delays. Emergency response teams benefit from real-time data sharing en route to hospitals, and remote surgeries powered by robotics and 5G are now a reality in some parts of the world.

Challenges and Considerations
Despite its promise, the transition to 5G is not without challenges. Infrastructure upgrades are costly and time-consuming, especially in rural or less-developed regions. Concerns about data privacy and cybersecurity are also growing, as more devices become interconnected and reliant on real-time data.

There are also health and environmental concerns—though no conclusive evidence has shown that 5G poses any greater risk than previous generations of wireless technology, public debate continues.

What Lies Ahead
The full potential of 5G is still unfolding, but one thing is clear: it’s reshaping everyday life in profound ways. As the technology matures and access becomes more widespread, it will serve as a backbone for innovations yet to come—fueling autonomous vehicles, augmented reality, and a more connected global economy.

For now, 5G is not just about faster smartphones. It’s about building a smarter, more efficient, and more responsive world.

Mastering Team Building for Organizational Success

Effective team building is essential for organizational success. Whether in startups or multinational corporations, high-performing teams drive innovation, enhance productivity, and cultivate a culture of collaboration. But what does it take to build such teams? Experts agree that it goes far beyond icebreakers and team outings.

  1. Define Clear Goals and Roles
    One of the cornerstones of effective team building is clarity. Teams function best when each member understands the group’s objectives and their individual responsibilities. Setting measurable goals ensures alignment and provides a shared sense of purpose. Leaders should also communicate how each role contributes to the bigger picture, which fosters accountability and motivation.
  2. Foster Open Communication
    Creating a safe space for honest dialogue is vital. Open communication builds trust, helps resolve conflicts quickly, and allows for the free exchange of ideas. Techniques such as regular team check-ins, one-on-one meetings, and anonymous feedback tools can promote transparency and inclusivity. Active listening is equally important leaders should not only speak clearly but also make a concerted effort to hear and respond to team concerns.
  3. Encourage Diversity and Inclusion
    Diverse teams bring a wealth of perspectives, leading to more creative and effective problem-solving. Inclusion ensures that every team member feels valued and empowered to contribute. Organizations should strive to hire for diversity and then create systems that support equitable collaboration, such as mentorship programs and bias training.
  4. Invest in Professional Development
    Great teams are made of individuals who are constantly learning and growing. Offering training opportunities, workshops, and access to online learning platforms helps employees develop both hard and soft skills. This investment not only strengthens the team’s capabilities but also boosts morale and retention.
  5. Celebrate Success and Learn from Failure
    Recognizing achievements both big and small reinforces positive behaviors and builds team morale. Whether through formal awards or informal shout-outs, appreciation goes a long way. At the same time, addressing failures with a growth mindset encourages resilience and innovation. Post-project reviews and lessons-learned sessions can turn setbacks into stepping stones.
  6. Leverage Team-Building Activities Thoughtfully
    While traditional team-building exercises like retreats or trust falls have their place, the most effective activities are those that align with the team’s culture and objectives. Activities that require collaboration and problem-solving such as escape rooms, hackathons, or volunteer projects can strengthen interpersonal bonds and mirror real workplace dynamics.
  7. Lead by Example
    Ultimately, team culture is shaped by leadership. Managers who demonstrate empathy, integrity, and a commitment to teamwork set the tone for the entire group. Authentic leadership inspires loyalty and fosters a sense of psychological safety, which is essential for risk-taking and innovation.


Team building is a continuous process that requires intention, strategy, and adaptability. As the workplace continues to evolve driven by remote work, AI integration, and generational shifts organizations that prioritize strong team dynamics will be better positioned to thrive.

As management consultant Patrick Lencioni famously said, “Not finance. Not strategy. Not technology. It is teamwork that remains the ultimate competitive advantage.”