
Cerebras Systems Inc. (NASDAQ: CBRS) has emerged as one of the more intriguing and volatile public companies attempting to reshape how artificial intelligence models are trained and, increasingly, how quickly they can perform inference.
Cerebras went public in May 2026 in one of the year’s most closely watched technology IPOs. Shares were priced at $185, and the completed offering raised approximately $6.38 billion in gross proceeds.
Four months later, the investment thesis is becoming clearer: Cerebras has extraordinary growth opportunities, but investors are paying a substantial valuation for that opportunity.
The artificial-intelligence infrastructure race is no longer simply about NVIDIA and GPUs.
What Makes Cerebras Different?
Cerebras attacks the AI computing problem differently from traditional GPU manufacturers.
Its core technological innovation is the Wafer Scale Engine (WSE). Rather than cutting a semiconductor wafer into numerous individual chips and connecting those processors together, Cerebras essentially turns an enormous portion of the wafer itself into one processor.
The objective is straightforward: eliminate many of the communication bottlenecks associated with moving information between individual chips.
Cerebras has increasingly focused this technology on high-speed AI inference the process of actually running trained AI models and generating answers for users and applications.
That distinction is important.
As AI moves from experimentation toward widespread commercial deployment, inference could become an enormous recurring infrastructure market. Every AI search, coding agent, autonomous workflow, enterprise chatbot and reasoning system consumes inference compute.
Cerebras wants to supply a meaningful portion of that compute.
Revenue Growth Is Accelerating
The company’s financial trajectory illustrates why investors are paying attention.
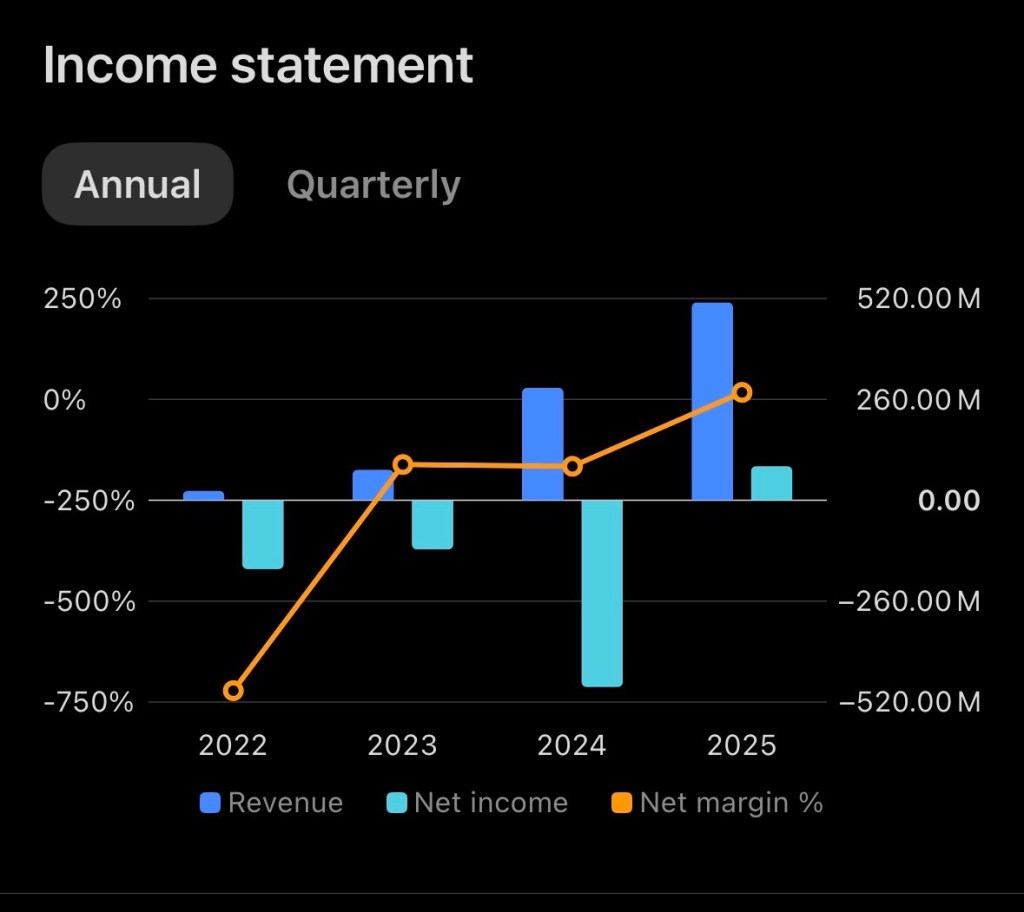
Cerebras generated approximately $290.3 million of revenue in 2024, increasing to roughly $510 million in 2025, representing 76% year-over-year growth.
Growth accelerated further during 2026.
First-quarter core revenue reached $191.3 million, up 92% year over year, including $111.6 million of hardware revenue and $79.8 million from cloud and other services.
Then came Q2.
Cerebras reported approximately $210 million of core revenue, while its core cloud business grew 287% year over year. The company also reported that it had secured approximately 600 megawatts of data-center capacity and planned to expand manufacturing capacity by more than tenfold during 2026.
Management subsequently increased its full-year outlook.
Cerebras now expects 2026 core revenue of approximately $880 million to $890 million, with core gross margins between 41% and 43% and core operating margins between negative 19% and negative 17%.
At the midpoint, $885 million would represent roughly 74% growth over 2025 revenue.
That is serious growth.
But it comes with an important caveat: Cerebras is still spending heavily to build the infrastructure necessary to capture that opportunity.
The $20+ Billion OpenAI Opportunity
Potentially the biggest component of the Cerebras growth story is its relationship with OpenAI.
Cerebras announced a multi-year agreement involving 750 MW of capacity valued at more than $20 billion. The company has also announced a multi-year partnership with Amazon to bring Cerebras inference technology to AWS.
These relationships potentially accomplish something extremely important for Cerebras: validation.
Competing against entrenched semiconductor and cloud-computing ecosystems requires more than superior benchmark performance. Customers need confidence that Cerebras can deploy its technology reliably and at enormous scale.
Large AI customers and cloud partners can help establish that credibility.
Cerebras has additionally disclosed customers or relationships involving companies such as Cognition, Lovable, Block, Figma, AlphaSense, GSK and CrowdStrike.
The company is therefore beginning to look less like an experimental AI-chip developer and more like an emerging AI infrastructure platform.
The CS-4 Could Be the Next Catalyst
Cerebras unveiled its next-generation CS-4 system in August, claiming performance of up to 30 times faster than GPU-based alternatives in certain workloads. The company is simultaneously expanding its global infrastructure footprint, including a recently announced 165 MW AI data center in Finland.
Those developments are worth watching closely.
AI infrastructure ultimately becomes an economics problem. Performance matters, but customers also care about cost per token, power consumption, latency, reliability and scalability.
If Cerebras can consistently demonstrate materially better inference economics—not merely impressive benchmark speeds—it could capture a meaningful piece of the rapidly expanding inference market.
The Financial Risk Investors Shouldn’t Ignore
The bull case is compelling, but CBRS isn’t a low-risk semiconductor investment.
First, profitability remains a work in progress.
Although Cerebras reported GAAP net income of $237.8 million during 2025, its filing shows a non-GAAP net loss of approximately $75.7 million, and the company explicitly warns investors that it has a history of generating losses.
Management’s 2026 guidance still calls for a substantially negative core operating margin.
Second, gross margins deserve close attention.
Q1 core gross margin was an impressive 47%, but Cerebras has been investing aggressively in cloud infrastructure and data-center capacity. The company currently expects full-year core gross margin of approximately 41%-43%.
Third, customer concentration has historically been significant. Large contracts can produce extraordinary revenue growth, but dependence on a relatively small number of enormous customers can also create significant volatility if deployments are delayed, renegotiated or canceled.
Finally, there is competition.
Cerebras isn’t operating in an empty market. NVIDIA dominates AI accelerators, while AMD, hyperscale cloud providers and custom silicon developers are all pursuing the same enormous AI-compute opportunity.
Cerebras doesn’t necessarily need to defeat NVIDIA to succeed.
It does, however, need to prove that wafer-scale computing occupies a sufficiently valuable niche within the broader AI infrastructure ecosystem.
Valuation: This Is Where Things Get Interesting
CBRS currently trades around $184, putting the company near its original $185 IPO price after experiencing substantial volatility since its May debut.
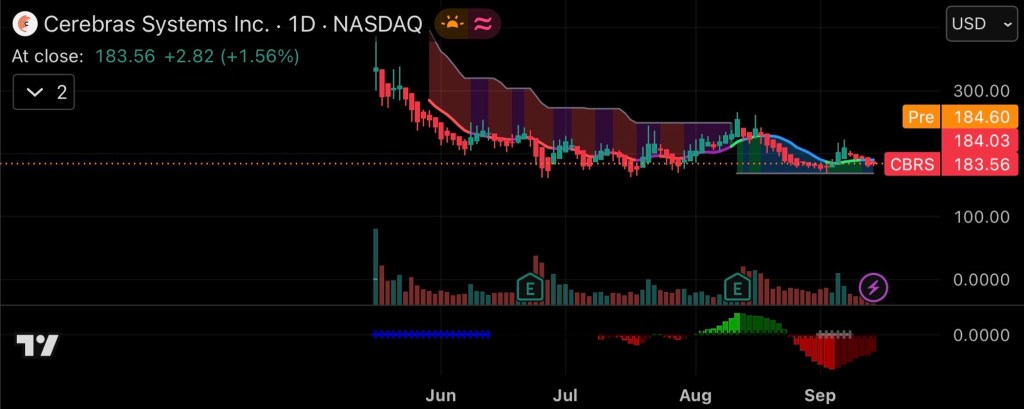
That matters psychologically, but the more important question is valuation.
With management forecasting approximately $885 million of 2026 core revenue, investors are already assigning Cerebras a substantial premium based on expectations of continued hypergrowth.
In other words, today’s CBRS valuation isn’t primarily based on what Cerebras earns today.
Investors are buying expectations for what the company could become several years from now.
That makes execution extremely important.
A company growing revenue 60%-80% annually can grow into a seemingly expensive valuation remarkably quickly. But if growth falls toward 20%-30% while profitability remains elusive, valuation compression can be equally dramatic.
My 12-Month CBRS Scenario Analysis
Forecasting a recently public, high-growth AI semiconductor company to a single price would create a false sense of precision. A scenario framework is more useful.
Bear Case: $120-$150
This scenario could develop if revenue growth decelerates, cloud margins deteriorate, major capacity deployments are delayed, customer concentration becomes problematic or investors broadly reduce the multiples they are willing to pay for AI infrastructure companies.
From approximately $184 today, that represents meaningful downside.
Base Case: $240-$300
This scenario assumes Cerebras continues producing strong revenue growth, approaches or exceeds its current guidance, demonstrates improving operating leverage and successfully converts its enormous infrastructure commitments into recurring cloud revenue.
Interestingly, current Wall Street research sits in roughly this neighborhood. Needham reiterated a $300 price target following the company’s first-quarter results.
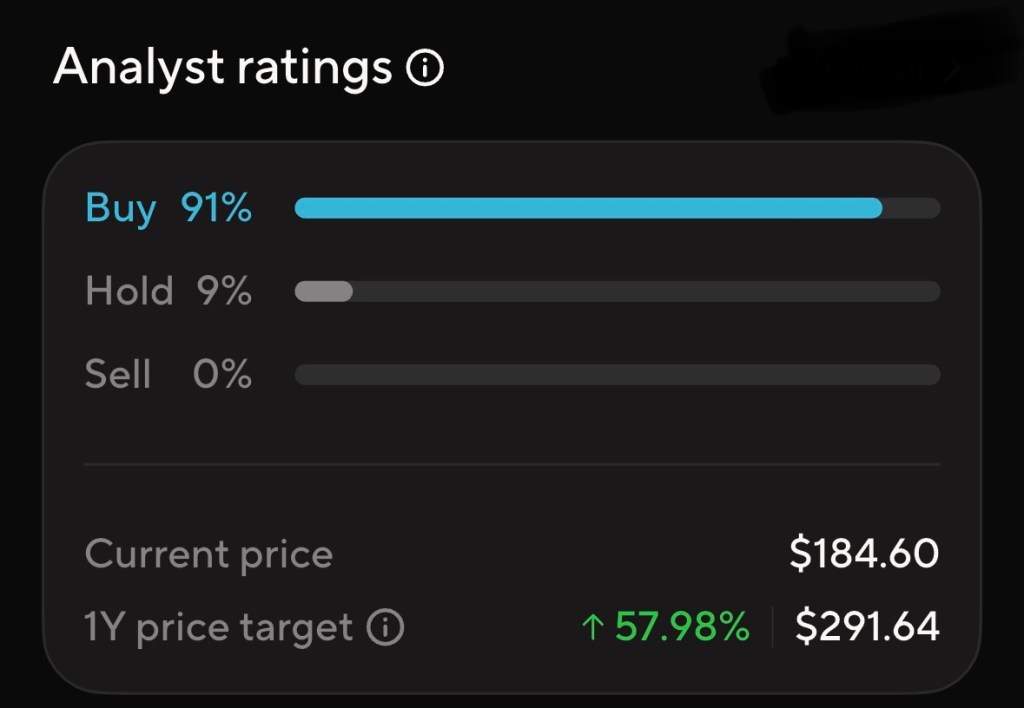
Aggregated analyst data recently showed an average target around $292, although analyst targets should always be viewed as estimates rather than predictions.
Bull Case: $350-$425
For Cerebras to reach this range, I would want to see several things happen simultaneously: revenue expectations moving materially above $1 billion, continued triple-digit or near-triple-digit cloud growth, successful OpenAI capacity deployments, evidence of attractive CS-4 economics, improving gross margins and a credible path toward operating profitability.
A sustained AI infrastructure spending cycle could provide an additional tailwind.
This is the highest-risk scenario because it requires both strong fundamental execution and investors continuing to award CBRS a premium valuation.
What I’m Watching Next
For investors holding CBRS, I believe five metrics deserve particular attention over the coming quarters:
- Cloud revenue growth: arguably the most important long-term metric because recurring inference revenue could eventually be more valuable than one-time hardware sales.
- Gross margin: rapid revenue growth means much less if infrastructure costs consume the economics.
- OpenAI deployment progress: successful conversion of the announced $20+ billion relationship into actual revenue could fundamentally alter Cerebras’ financial profile.
- Operating losses: Cerebras needs to demonstrate that revenue can eventually grow considerably faster than operating expenses.
- Customer diversification: additional enterprise and hyperscale customers would reduce dependence on a handful of massive relationships.
The Bigger Picture
Cerebras represents a particularly interesting kind of AI investment.
This isn’t simply another company adding artificial intelligence to an existing product.
Cerebras is building the physical infrastructure required to run AI itself.
The company increased revenue from just $24.6 million in 2022 to $510 million in 2025, and management now expects approximately $880-$890 million in core revenue during 2026.
Meanwhile, cloud revenue is growing at nearly 300%, manufacturing capacity is expanding dramatically, hundreds of megawatts of data-center capacity are under contract, and Cerebras is developing relationships with some of the most important companies in artificial intelligence.
That’s the opportunity.
The risk is that investors already recognize much of it.
At approximately $184 per share, CBRS remains a high-growth, high-expectation investment where quarterly execution can produce enormous price swings, as demonstrated when shares dropped sharply following the company’s August earnings release despite management raising its annual outlook.
My working 12-month framework therefore puts $240-$300 as a reasonable base-case range, with approximately $120-$150 representing a bearish execution/valuation scenario and $350-$425 representing a strong-execution bull scenario.
Those ranges aren’t price targets or guarantees. They are a framework for measuring future results against the expectations embedded in the stock.
For investors already holding Cerebras, the central question isn’t simply whether artificial intelligence will continue growing.
It almost certainly will.
The more important question is whether Cerebras can convert its technological advantage, enormous customer agreements and rapidly expanding infrastructure footprint into durable revenue growth and ultimately durable profits.
If it can, CBRS could become one of the more important publicly traded AI infrastructure companies to emerge from this generation of the technology boom.
Disclosure: I currently hold a position in Cerebras Systems (NASDAQ: CBRS). This article reflects personal research and analysis and is provided for informational purposes only. It is not financial advice or a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal.


 Health to Wealth Ventures
