The Advantages of MYGA (Multi-Year Guaranteed Annuity)

In today’s unpredictable financial climate, securing a stable and reliable source of income during retirement is a top priority for many individuals. Amidst various investment options, MYGA (Multi-Year Guaranteed Annuity) stands out as a beacon of financial security, offering a plethora of benefits that cater specifically to retirees’ needs.

MYGA, short for Multi-Year Guaranteed Annuity, is a type of fixed annuity renowned for its simplicity, stability, and predictability. Unlike other investment vehicles subject to market volatility, MYGA annuities provide a guaranteed interest rate over a specified period, typically ranging from three to ten years. This fixed-rate feature shields retirees from market fluctuations, ensuring a steady income stream throughout their golden years.

One of the primary advantages of MYGA annuities lies in their predictability. Retirees can rest assured knowing exactly how much income they will receive over the annuity’s term, regardless of economic conditions. This predictability eliminates the anxiety associated with market downturns, providing peace of mind and financial stability.

Moreover, MYGA annuities offer flexibility in terms of payout options. Retirees can choose between receiving regular income payments or opting for a lump-sum withdrawal at the end of the annuity term. This flexibility empowers retirees to tailor their income streams according to their specific financial needs and goals.

Another notable benefit of MYGA annuities is their simplicity. Unlike other retirement investment options that may involve complex fee structures and investment choices, MYGA annuities are straightforward and easy to understand. This simplicity makes them an attractive option for retirees seeking hassle-free financial planning solutions.

Furthermore, MYGA annuities often come with optional features that can enhance their value. For instance, some annuities offer inflation protection riders, which adjust income payments to account for rising living costs. Others may include death benefit provisions, ensuring that beneficiaries receive a predetermined amount upon the annuitant’s passing.

The appeal of MYGA annuities extends beyond retirees to financial advisors who recognize the importance of guaranteed income in retirement planning. These annuities provide advisors with a reliable tool to help their clients achieve long-term financial security while minimizing risk.
MYGA (Multi-Year Guaranteed Annuity) stands as a beacon of stability and security in today’s uncertain financial landscape. With its guaranteed interest rates, flexibility, simplicity, and optional features, MYGA annuities offer retirees a dependable source of income and peace of mind during their retirement years. As retirees seek to secure their financial futures, MYGA annuities emerge as a compelling option that deserves careful consideration. If you need help deciding if a MYGA or another annuity is the right investment decision give me a call, shoot me an email or drop me a line and I will give you a hand.

The World of Variable Annuities: A Closer Look at the Trends and Data

In the ever-evolving landscape of financial instruments, variable annuities have emerged as a popular choice for individuals seeking a combination of investment growth and income protection. These financial products have garnered attention for their flexibility and potential benefits, but recent data sheds light on key trends and considerations for investors.

Rising Popularity Amid Economic Uncertainty:

Variable annuities have witnessed a surge in popularity, particularly in the face of economic uncertainty. As investors seek stability and guaranteed income in retirement, variable annuities offer a unique proposition by combining investment options with insurance features. According to recent industry reports, sales of variable annuities have seen a notable uptick, with an increasing number of individuals incorporating them into their retirement planning strategies.

Customization and Investment Options:

One of the key advantages of variable annuities is the ability to customize investment portfolios based on individual risk tolerance and financial goals. Investors can allocate funds among a variety of sub-accounts, typically consisting of stocks, bonds, and other investment instruments. This flexibility allows for a tailored approach to wealth accumulation, providing an attractive option for those seeking a diversified investment strategy within the framework of an annuity.

Guaranteed Income Features:

Variable annuities often come with optional riders or features that guarantee a minimum level of income, regardless of market performance. These riders, commonly known as living benefits, provide a sense of security by establishing a baseline income stream during retirement. While these features can be appealing, investors should carefully evaluate the associated costs and understand the trade-offs involved in balancing guaranteed income against potential investment gains.

Considerations and Challenges:

Despite their appeal, variable annuities also present certain considerations and challenges. High fees and complex structures have been cited as potential drawbacks, and investors are encouraged to carefully review the terms and conditions of these products before making a commitment. Additionally, surrender charges and limitations on withdrawals may impact liquidity, making it crucial for investors to have a clear understanding of the product’s terms.

Regulatory Developments:

The variable annuities market has not gone unnoticed by regulators. Recent regulatory developments have focused on enhancing consumer protections and increasing transparency in the sale of these products. Investors should be aware of any changes in regulations that may impact the features and sales practices associated with variable annuities.

Variable annuities continue to be a noteworthy option for individuals planning their retirement. As with any financial product, it is imperative for investors to conduct thorough research, seek professional advice, and carefully assess their financial objectives before incorporating variable annuities into their portfolios. With the right approach and understanding, these products can play a valuable role in a well-rounded retirement strategy. If you need help deciding on what variable annuity best suits you give me a shout, drop me a comment, or call me directly so we can talk about your options. Until next time… keep smiling cause it really does look good on you.

About the Author:

David Dandaneau is a insurance agent that covers the insurance and financial services industry. He is known for his insightful analysis and comprehensive coverage of market trends and regulatory developments.

Navigating the Terrain: Fixed vs. Variable Annuities

When it comes to planning for retirement, individuals often seek financial instruments that provide a steady stream of income. Annuities, with their promise of regular payments, have become a popular choice. However, not all annuities are created equal. Two main types dominate the landscape: fixed and variable annuities. Understanding the differences between these two can significantly impact your financial strategy.

Fixed Annuities: The Stable Foundation

Fixed annuities are the conservative stalwarts of the annuity world. These financial instruments offer a guaranteed fixed interest rate over a specified period. The insurance company assumes the investment risk, providing policyholders with a sense of security. Here’s a closer look at some key features of fixed annuities:

  1. Steady Income: The fixed interest rate ensures a stable and predictable stream of income, making it an attractive option for those who prioritize financial security.
  2. Risk Mitigation: Policyholders are shielded from market fluctuations. The insurance company assumes the risk, offering a reliable source of income regardless of economic conditions.
  3. Principal Protection: In addition to a fixed interest rate, fixed annuities often come with a guarantee to protect the principal investment, providing an extra layer of security.

While fixed annuities provide stability, they may lag behind variable annuities in terms of potential returns, as they are generally more conservative.

Variable Annuities: Riding the Market Waves

Variable annuities, on the other hand, introduce an element of risk and reward into the annuity equation. They are linked to investment portfolios, allowing policyholders to participate in market gains. Here are some key aspects of variable annuities:

  1. Market Exposure: Variable annuities offer the opportunity for higher returns as they are linked to investment funds. This exposes policyholders to market fluctuations, potentially leading to increased income.
  2. Potential for Growth: While the returns are not guaranteed, the potential for growth is higher compared to fixed annuities. This can be appealing for those willing to take on some level of risk.
  3. Investment Choices: Policyholders can often choose from a variety of investment options, such as stocks and bonds, allowing for greater customization of their portfolio.

However, the flip side of potential growth is the risk of market downturns, which can result in lower income or even a loss of principal.

Choosing the Right Fit

Deciding between fixed and variable annuities ultimately depends on your financial goals, risk tolerance, and investment strategy. If you prioritize stability, principal protection, and a guaranteed income stream, a fixed annuity may be the right choice. On the other hand, if you are comfortable with market exposure and seek the potential for higher returns, a variable annuity might be more suitable.

It’s important to note that there are also hybrid or indexed annuities that combine elements of both fixed and variable annuities, providing a middle ground for those looking to balance risk and stability.

The choice between fixed and variable annuities is a nuanced decision that requires careful consideration of your financial objectives. Seeking advice from a financial professional can help you navigate the complexities and make an informed choice that aligns with your unique circumstances and goals.If you need help picking the right annuity give me a call, shoot me an email, or drop me a comment and I will be willing to help. Otherwise, and as usual keep smiling cause it really does look good on you.

Long-Term Care Awareness Month: The Importance of Planning your Future

Long Term Care Awareness Month is the perfect time to shed light on the importance of planning for your future well-being. As we go through life, it’s easy to overlook the possibility that we may require assistance with daily activities as we age. However, the reality is that long-term care services might become a necessity for many of us.

  • Changing Demographics: The aging population is increasing, and with longer life expectancies, the need for long-term care is becoming more prevalent. Highlighting these demographic shifts can emphasize the importance of being prepared for the potential challenges that come with aging. As of 2021, around 16.5% of the U.S. population is aged 65 and older. This number is expected to increase significantly in the coming decades.
  • Financial Protection: Long-term care can be expensive, and without proper planning, it could significantly impact your financial stability. Discussing the financial aspects of long-term care and how planning ahead can provide a safety net for your assets is crucial. While the ownership of long-term care insurance has decreased in recent years, it remains an essential tool for financial planning. In 2020, approximately 7.2 million Americans were covered by long-term care insurance policies
  • Preserving Independence: Long-term care doesn’t just mean nursing homes. It can encompass a range of services that allow individuals to age gracefully in their own homes. Emphasizing the importance of maintaining independence and the role of long-term care in enabling this can be a powerful motivator. There is a growing preference for home and community-based services. As of 2018, about 4.5 million people received these services, allowing them to age in place.
  • Family Dynamics: Long-term care can also affect your family members. Discussing the potential impact on your loved ones and how planning ahead can ease the burden on them emotionally and financially can be a persuasive argument. It is estimated that approximately 70% of individuals turning 65 will require some form of long-term care services in their lifetime.
  • Peace of Mind: Knowing that you have a plan in place for your long-term care needs can provide peace of mind. It allows you to focus on enjoying your retirement and the later stages of life without the constant worry about what might happen if you need assistance.
  • Healthcare System Considerations: Exploring the strain on the healthcare system due to the increasing demand for long-term care services can underscore the importance of individual responsibility in planning for one’s future care needs. The cost of long-term care can vary, but on average, a private room in a nursing home can cost over $100,000 per year. In-home care services can also be expensive, with costs varying based on the level of assistance needed.
  • Educational Resources: Use Long Term Care Awareness Month as an opportunity to provide educational resources. Share information about different long-term care options, how they work, and steps individuals can take to prepare for their future care.

Remember, the key is to approach the topic with a positive and proactive mindset. Long-term care planning is an investment in your future well-being, and creating awareness during this month can inspire others to take the necessary steps to ensure a secure and comfortable retirement. If you need help obtaining a policy give me a shout, drop me a line or give me a call and I would be happy to help you find the right policy..

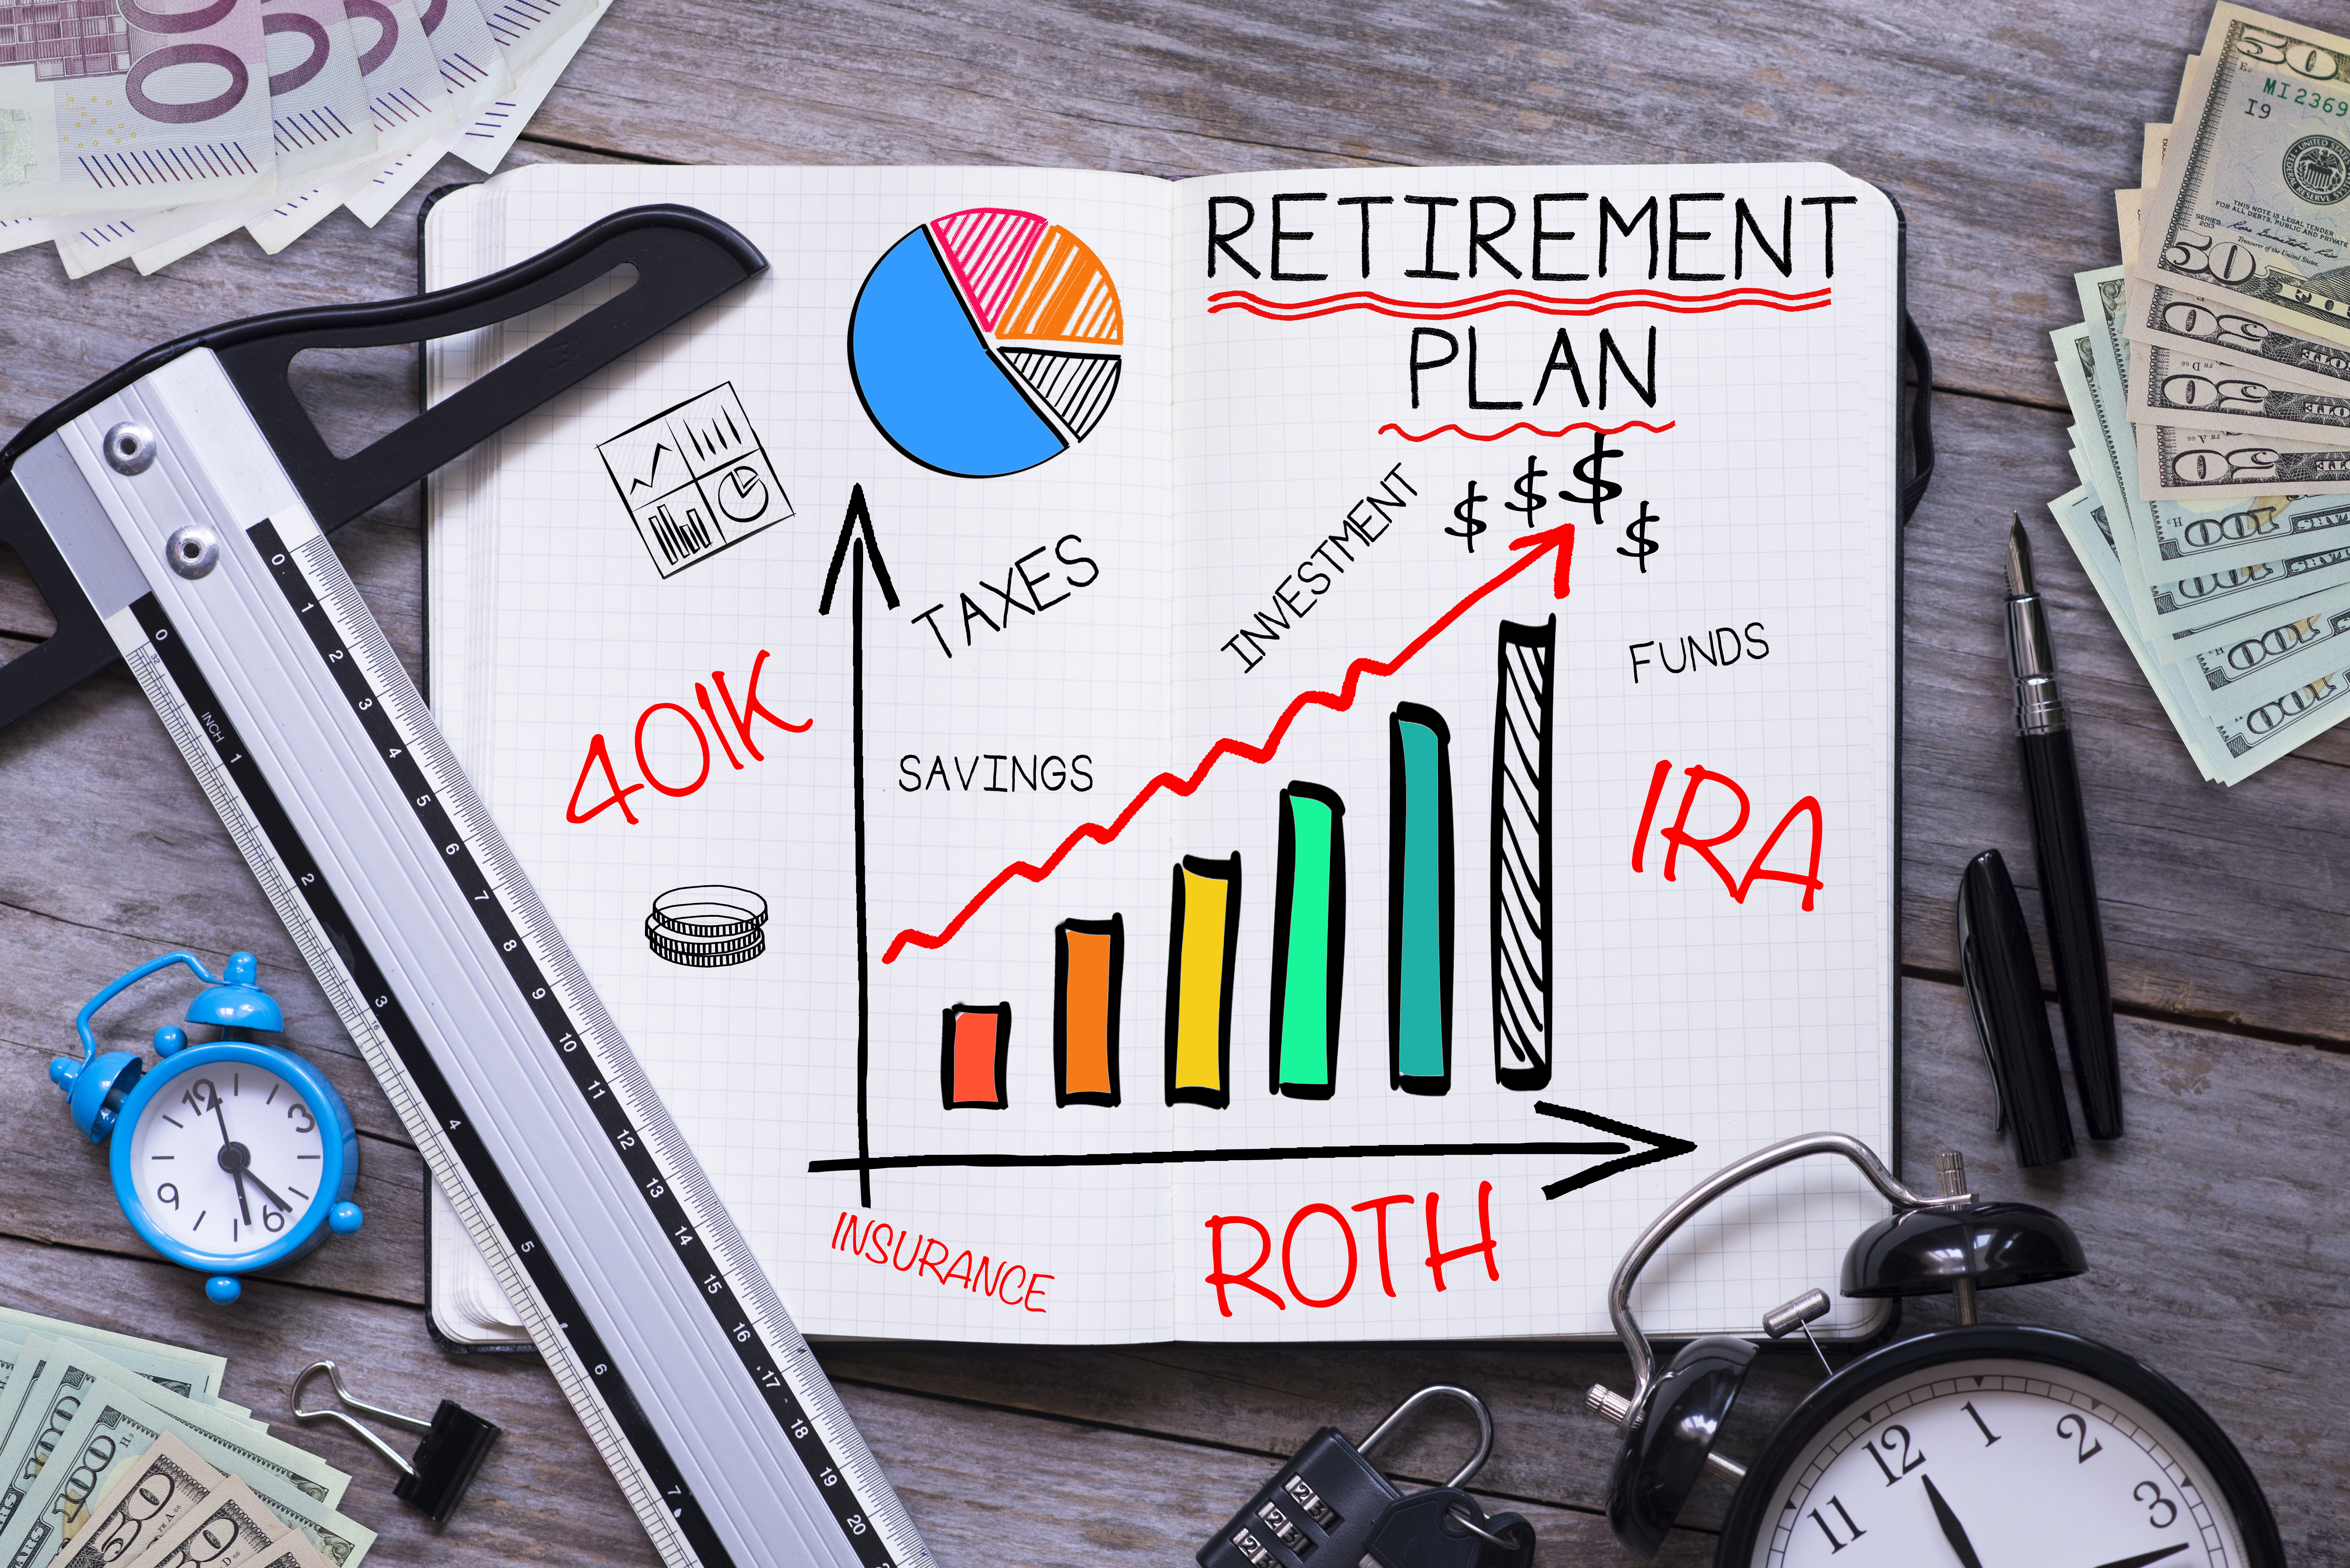
Retirement Investments: A Statistical Comparison of 401(k) and Annuities

When it comes to planning for retirement, individuals are often faced with a myriad of investment options. Two popular choices are 401(k) plans and annuities, each offering unique features and benefits. In this blog post, we’ll delve into a statistical comparison of 401(k) plans and annuities to help you make an informed decision for your retirement portfolio.

401(k) Plans:

  1. Contribution Limits:
    • In 2023, the maximum annual contribution limit for 401(k) plans is $19,500 for individuals under the age of 50, and $26,000 for those 50 and older, including catch-up contributions.
    • The ability to contribute pre-tax income to a 401(k) can significantly reduce taxable income during your working years.
  2. Employer Matching:
    • Many employers offer matching contributions to 401(k) plans, providing an instant boost to your retirement savings.
    • A common matching structure is a dollar-for-dollar match up to a certain percentage of your salary.
  3. Investment Options:
    • 401(k) plans typically offer a range of investment options, including stocks, bonds, and mutual funds.
    • Participants have control over their investment choices, allowing for a diversified portfolio based on risk tolerance and investment goals.

Annuities:

  1. Guaranteed Income:
    • Annuities are designed to provide a steady stream of income during retirement.
    • With certain types of annuities, such as immediate or fixed annuities, you can receive a guaranteed income for life.
  2. Risk Mitigation:
    • Annuities can act as a hedge against market volatility, making them appealing for individuals seeking a more stable retirement income.
    • Fixed and fixed indexed annuities protect against market downturns, providing a level of security.
  3. Liquidity and Accessibility:
    • Annuities often come with surrender charges and withdrawal restrictions.
    • Some annuities offer liquidity features, allowing partial withdrawals or access to funds under certain circumstances.

Statistical Analysis:

  1. Historical Returns:
    • 401(k) plans historically benefit from market growth, with average annual returns influenced by market conditions.
    • Annuities may offer lower returns compared to the stock market, but they provide stability and consistent income.
  2. Long-Term Growth:
    • The compounding effect of long-term investments in 401(k) plans can result in substantial growth over time.
    • Annuities focus on preserving capital and generating income, prioritizing a more conservative approach.
  3. Risk Tolerance and Diversification:
    • 401(k) plans allow for greater flexibility in managing risk through diversification across asset classes.
    • Annuities are often favored by those with lower risk tolerance, seeking a guaranteed income stream without exposure to market fluctuations.

Choosing between a 401(k) plan and annuities depends on your individual financial goals, risk tolerance, and preferences. While 401(k) plans offer growth potential through market participation, annuities provide a secure income stream with reduced market exposure. Understanding the statistical aspects of each option is crucial for crafting a well-balanced retirement strategy that aligns with your unique circumstances. If you need help moving a dormant or inactive 401(k) to an annuity, give me a shout or drop me a line, as I would love to help show you how we can make your money grow without the risk of downside. Otherwise, and like usual keep smiling cause it really does look good on you.

Life Insurance Awareness Month- Why You May Need It?

Life insurance is a crucial financial tool that provides invaluable protection and peace of mind for you and your loved ones. Firstly, one of the primary reasons to consider life insurance is to ensure the financial security of your family and dependents in case of your untimely demise. When you have life insurance coverage, your beneficiaries receive a tax-free payout, often referred to as the death benefit, which can help cover essential expenses like mortgage payments, education costs, daily living expenses, and outstanding debts. This financial support ensures that your loved ones can maintain their quality of life and avoid financial hardship during an already emotionally challenging time.

Secondly, life insurance can play a pivotal role in estate planning and wealth preservation. If you have significant assets, such as a home, investments, or a business, life insurance can help cover estate taxes and other associated costs. By doing so, it ensures that your heirs receive the full value of your estate without being burdened by hefty tax liabilities. This strategy can safeguard your legacy and ensure that your hard-earned assets benefit the people and causes you care about most.

Lastly, life insurance can serve as a powerful tool for long-term financial planning and achieving various financial goals. Some policies, like whole life or universal life insurance, offer cash value accumulation over time, which can be borrowed against or withdrawn for various purposes, such as funding your retirement, paying for your child’s education, or handling unexpected financial emergencies. By including life insurance in your financial portfolio, you not only protect your family’s future but also create opportunities for building wealth and achieving your financial aspirations.

In summary, life insurance is a critical component of a comprehensive financial plan. It safeguards your family’s financial well-being, aids in estate planning, and offers opportunities for long-term financial growth. Whether you’re a young professional starting a family or a seasoned investor looking to preserve your wealth, life insurance is a prudent investment that provides security and financial flexibility when it matters most. Of course, there are other reasons you should consider when purchasing a life insurance policy and if you have any I would love to hear them. Drop me a comment or send me a note and I would love to share your thoughts and if not, just remember to keep smiling cause it really does look good on you no matter what you do!

← Back

Thank you for your response. ✨